
Momentum Upgrade Might Change The Case For Investing In Bread Financial (BFH)
- Bread Financial Payments renewed its long-term agreement with Signet Jewelers, extending credit support across most U.S. brands and adding Blue Nile to its portfolio, with a focus on technology upgrades, analytics and tailored credit programs.
- The refreshed Signet relationship underscores Bread Financial Holdings' push into data-driven underwriting, digital customer journeys and embedded credit that aligns closely with retailer needs.
- This article examines how Bread Financial Holdings' investment narrative is shaped by this renewed, data focused credit partnership with Signet.
Scan how Bread Financial Holdings’ renewed, data heavy credit push compares with other lenders by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results).
Bread Financial Holdings Investment Narrative Recap
Bread Financial Holdings asks you to believe that tighter credit standards, tech focused card programs and deeper retailer partnerships can support earnings even if average loan growth stays muted. The Signet renewal fits that story. It expands embedded credit reach and keeps a large retail client in house, which supports fee and interest income visibility rather than transforming it.
The bigger near term swing factor is credit quality. High bad loan levels and flat to declining loan balances keep loss rates and net interest margin in focus. The Signet and Blue Nile programs add scale, but they do not change the central risk that a weaker consumer or pricing pressure on renewals could squeeze returns.
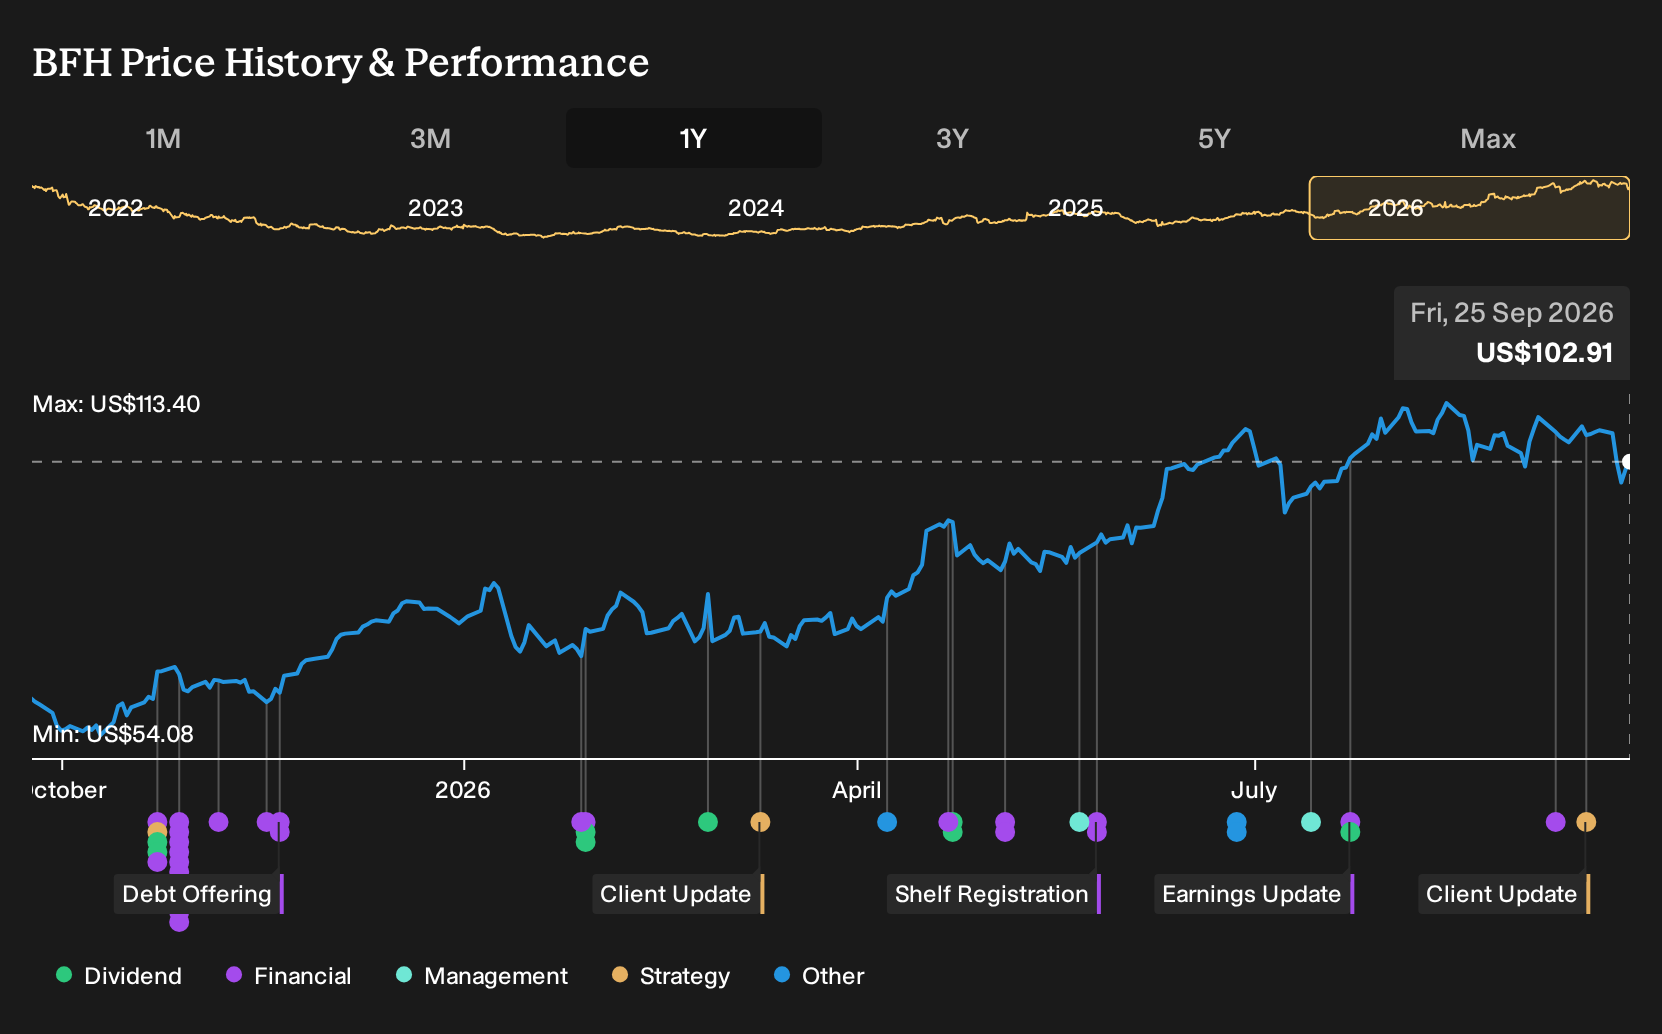
The most relevant recent datapoint for this story is Bread Financial Holdings being highlighted as a top momentum stock on September 25, 2026, with a strong Momentum Score and a Zacks Rank #1. That recognition reflects share price performance and rising earnings estimates, which often ties back to investor confidence around execution on partnerships like Signet.
For you, the link is practical. Momentum interest can amplify both upside and downside around catalysts such as large contract renewals, credit trend updates and funding cost moves. If earnings expectations or credit outcomes shift, a momentum heavy shareholder base can react quickly. That dynamic makes execution on technology upgrades, analytics, and loss control across programs like Signet even more important.
Bread Financial Holdings is currently modeled to reach about US$4.4b in revenue and US$510.9m in earnings by 2029. This lines up with analyst forecasts that imply 18.0% yearly revenue growth and an earnings decline of roughly US$54.1m from current earnings of US$565.0m.
Uncover why Bread Financial Holdings' fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You might see the Signet renewal as a win, but the lowest Bread Financial Holdings analysts focus on regulatory risk instead. They were penciling in profit margins compressing to 8.8% and earnings around US$385.0m by 2029, well below consensus. Those pre news forecasts show how sharply opinions can diverge; it pays to compare several viewpoints yourself.
Explore another Bread Financial Holdings fair value estimate, including one that suggests it could be worth just $114.47.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bread Financial Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bread Financial Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bread Financial Holdings' overall financial health at a glance.
Looking for more Bread Financial Holdings style ideas?
If the Bread Financial Holdings story has you thinking about portfolio gaps, it can help to scan other companies with different strengths and risk profiles using the Simply Wall St Screener.
- For investors who want potential upside backed by fundamentals rather than hype, check out 16 high quality undiscovered gems that may be flying under the radar.
- If resilience matters most to you, focus on 30 resilient stocks with low risk scores that score well on stability and measured volatility.
- When balance sheet strength is non negotiable, filter for companies in the list of solid balance sheet and fundamentals (24 results) that also show solid business metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com