
How Investors Are Reacting To GEO Group (GEO) $7b DHS Detention Contracts
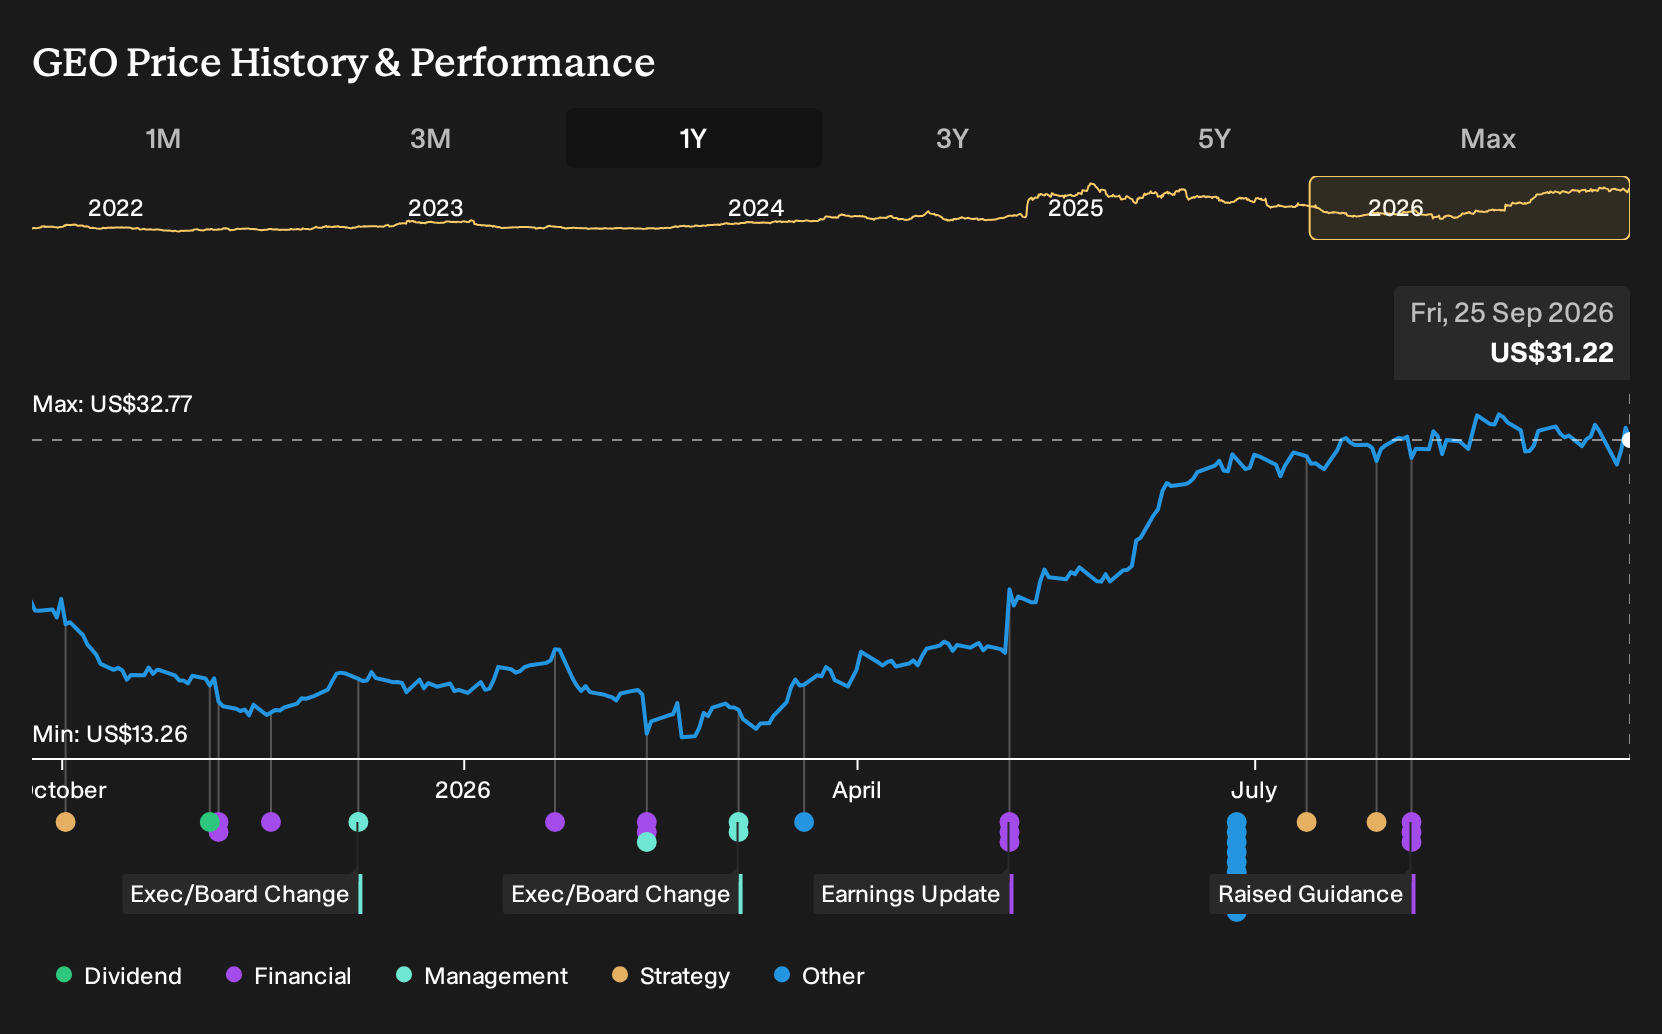
- GEO Group recently secured over $7 billion in construction contracts from the Department of Homeland Security to expand immigration detention facilities across multiple US states, including New York, Texas, Arizona, Florida, and California, with further projects planned in Colorado, Washington, and Pennsylvania.
- The new detention buildout points to a larger role for GEO Group in federal immigration infrastructure, with long-duration service obligations that could influence how investors view the stability and concentration of its government revenue base.
- This article examines how GEO Group's multibillion-dollar DHS detention expansion could affect its existing investment narrative and risk profile.
Scan how GEO Group fits into a wider government-contract theme by comparing it with hand picked list of solid balance sheet and fundamentals (24 results) that are also built around long term public sector spending.
GEO Group Investment Narrative Recap
For GEO Group, the big picture is simple. You have to believe that long term demand for secure facilities and immigration detention capacity remains firm enough for its ICE contracts to stay utilized and renewed, even as political priorities shift. The new US$7b DHS construction awards plug directly into that belief by extending visibility on facility buildout and future service contracts.
The key near term swing factor is how fast GEO turns these awards into staffed, operational sites that can support cash flow and debt service. The biggest risk remains concentration in US federal detention policy. A funding pullback, change in enforcement approach, or contract rebid outcome could quickly pressure utilization and margins.
Among recent developments, the most relevant thread is the broader surge in federal immigration enforcement funding that underpins GEO Group's pipeline of ICE projects. Existing catalysts already pointed to multi year support from higher border security appropriations and a large pool of idle or expandable beds that could be brought into service.
This fresh DHS buildout fits into that backdrop by potentially absorbing more of those unused assets over time and reinforcing GEO's role as a core federal contractor. For you as a shareholder, the focus is execution quality. Timelines, cost control, staffing, and compliance track record at new facilities will shape how much of that contracted volume turns into sustainable earnings and balance sheet improvement.
GEO Group's analyst narrative projects US$3.8b in revenue and US$137.8m in earnings by 2029, built on an assumed 9.9% yearly revenue growth rate and an earnings decline of about US$153.7m from US$291.5m today.
Uncover how GEO Group's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view on GEO Group focuses heavily on execution risk. These analysts worry that ramping so many new detention projects could stumble, and before this news they were only penciling in about US$3.6b of 2029 revenue and US$141.9m of earnings. That is a much more cautious story. Use it as a prompt to test your own assumptions as fresh information arrives.
Explore 3 other GEO Group fair value estimates, including one that suggests it could be worth just $37.75!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your GEO Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for GEO Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEO Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond GEO Group?
If the GEO Group story has you thinking about contract visibility, balance sheets, and income reliability, it can help to pressure test those same themes across a wider watchlist using the Simply Wall St Screener.
- If capital protection is top of mind, filter for stocks with more resilient financial foundations by starting with a 30 resilient stocks with low risk scores that already score well on balance sheet strength and volatility.
- If value is your priority, compare GEO Group with companies that pair stronger fundamentals with what looks like cheaper pricing through a curated set of 32 high quality undervalued stocks tailored for further research.
- If you want earlier stage stories with cleaner finances, broaden your search to smaller stocks that still show solid cash flow support by scanning a 8 elite penny stocks with strong financials that clear basic quality and funding tests.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com