
Should Traffic And Sales Growth Require Action From BJ's Restaurants Stock Investors?
- BJ's Restaurants reported Q2 traffic growth of 8.3% and same-store sales growth of 6.5%, which management linked to operational improvements, menu changes, and a tighter focus on guest experience.
- The CEO framed BJ's recent performance around "durable and disposable transactions," highlighting a targeted approach to casual dining occasions rather than broad-based discounting.
- Investors can now assess how BJ's Restaurants investment narrative may be influenced by management's focus on operational execution and guest traffic gains.
Scan for other casual dining and consumer stocks showing similar traffic and sales momentum to BJ's Restaurants with a curated list of 16 high quality undiscovered gems.
BJ's Restaurants Investment Narrative Recap
For BJ's Restaurants, you need to believe the concept can keep pulling more guests in while holding on to margin gains. The recent 8.3% traffic lift and 6.5% same-store sales growth speak directly to that. In the short term, the key swing factor is whether this momentum in visits and check builds on two years of operational fine tuning or fizzles out as promotions lapse.
The flip side is clear. A casual dining model that leans on labor intensive dine in service, comfort food, and measured unit growth still faces pressure from wage inflation, health focused eating, and crowded competition. If labor costs bite harder or digital and off premise ordering lag peers, the risk is that these strong quarterly metrics do not translate into lasting profitability.
Among recent commentary, CEO Lyle Tick’s focus on “durable and disposable transactions” is the most relevant lens for this Q2 print. Management is not chasing every visit with blanket discounting. The emphasis is on specific casual dining occasions where the brand already resonates and can justify its value proposition without heavy couponing.
For you, that framing ties directly into the catalysts around menu platforms, operational efficiency, and digital ordering. If BJ's Restaurants can keep refining those “durable” occasions while smoothing ordering and labor models around them, the traffic and same-store sales strength seen in Q2 could support the existing earnings growth narrative. Execution missteps or a slowdown in those targeted occasions would quickly test that thesis.
BJ's Restaurants' narrative projects US$1.6b revenue and US$72.0 million earnings by 2029. This aligns with analysts' assumption of 4.4% yearly revenue growth and implies an earnings increase of about US$31.1 million from current earnings of US$40.9 million.
Uncover how BJ's Restaurants' fair value indicates a 24% potential upside to its current price before the market closes that gap.
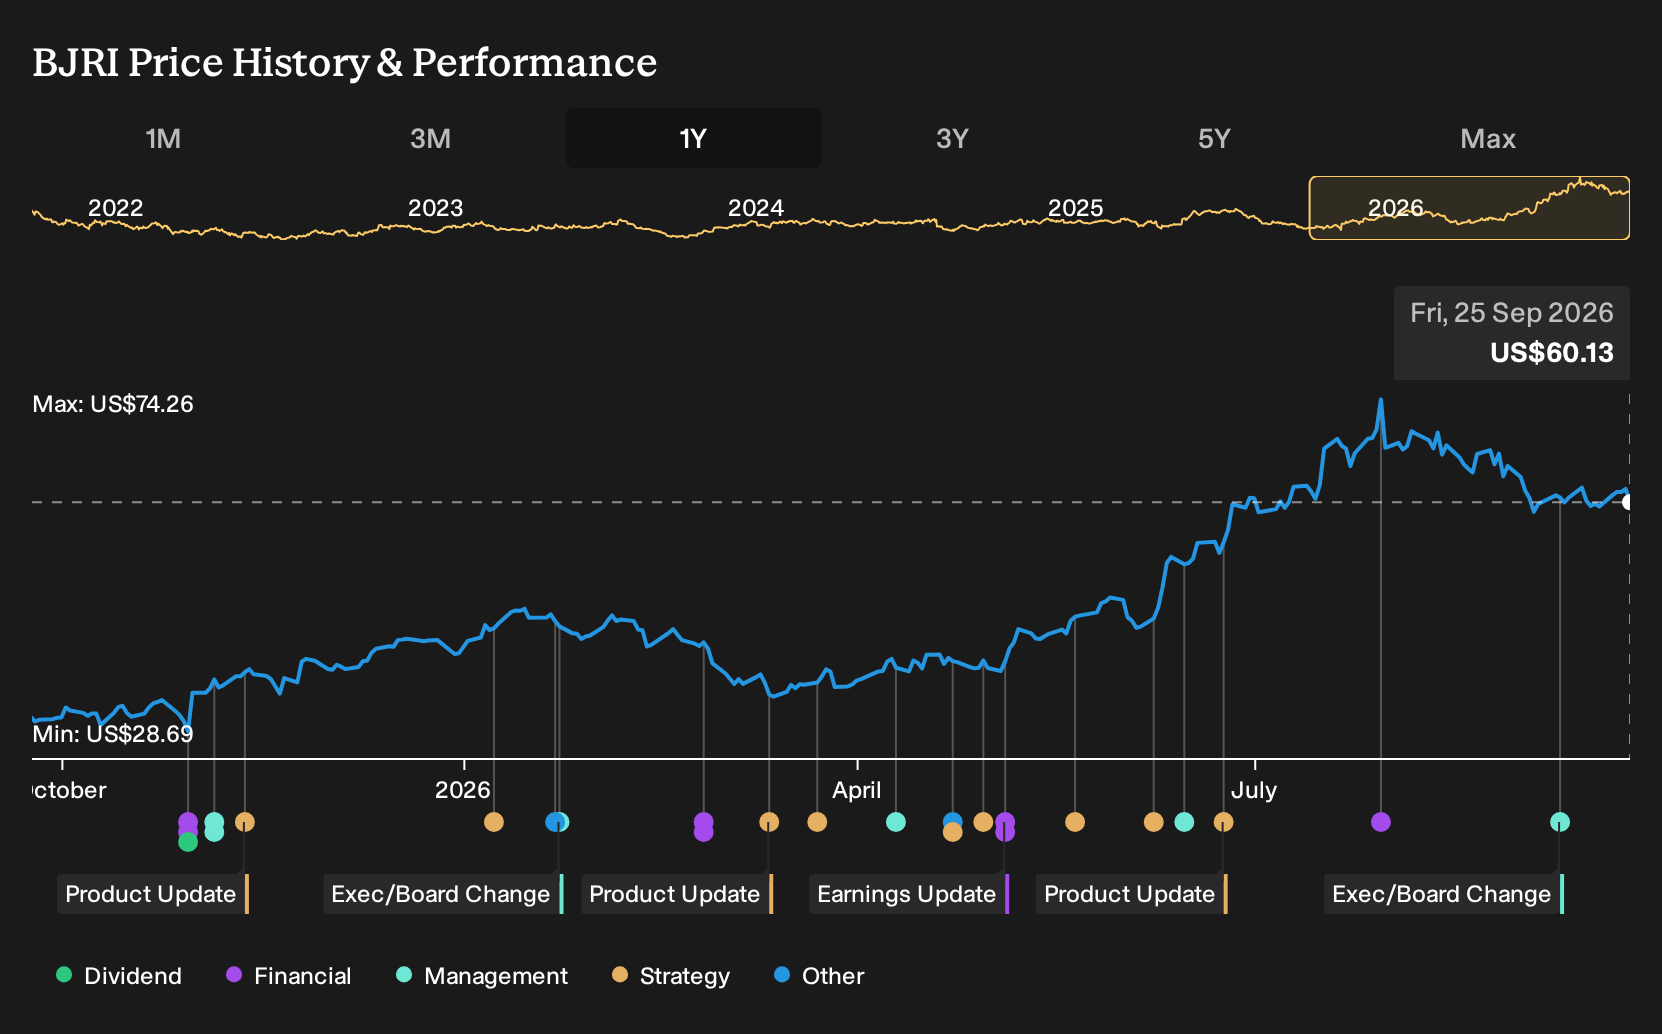
Exploring Other Perspectives
One alternate angle on BJ's Restaurants puts far more weight on labor pressure. The most cautious analysts were penciling in about US$1.6b of revenue and US$68.1 million of earnings by 2029 before this Q2 traffic surprise. That view sees tight staffing and higher wages capping upside, which your own take may challenge after this report.
Explore another BJ's Restaurants fair value estimate, including one that suggests as much as 23% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BJ's Restaurants research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BJ's Restaurants. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate BJ's Restaurants' overall financial health at a glance.
Looking For More Investment Ideas Beyond BJ's Restaurants?
If the BJ's Restaurants story has sharpened your thinking on traffic, pricing power, and execution, it can help to compare that with other businesses facing similar tests. The Simply Wall St Screener lets you quickly scan for stocks that match the kind of balance sheet strength, income profile, or risk level you want to focus on next.
- For investors who want quality first and volatility second, start with a curated 30 resilient stocks with low risk scores that aims to prioritise resilience over drama.
- If capital preservation and financial strength matter most to you, compare BJ's Restaurants with a list of solid balance sheet and fundamentals (24 results) so you can see which businesses keep their foundations tight.
- For readers building an income watchlist, supplement your work on BJ's Restaurants by scanning a set of 8 dividend fortresses that may fit a yield focused playbook.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com