
BWG (OB:BWLPG) After Its $300 Million Bond Deal And The Fair Value Debate
BWG (OB:BWLPG) is back in focus after placing $300 million in senior unsecured convertible bonds to finance eight new Panamax VLGCs. Management expects this funding move will not alter dividend plans.
BWG’s share price has eased 5.4% over the past week but still shows a 4.1% 1 month share price return and a 31.1% 3 month share price return, while the 5 year total shareholder return is very large. This points to momentum built over multiple cycles rather than a short term spike linked only to the latest bond issue.
Scan other LPG and shipping plays that show similar momentum and capital investment stories by zeroing in on the 620 high quality undiscovered gems that match the kind of profile BWG is building toward.
BWG trades only slightly below analyst targets while carrying a sharp revenue and earnings step down, and now adds fresh leverage for newbuilds. Is that modest discount a safety margin or a warning label as you weigh valuation next?
Most Popular Narrative: 1.8% Undervalued
On the narrative side, BWG is framed as slightly undervalued, with a fair value of NOK235 against the last close at NOK230.8, which keeps the conversation finely balanced between upside and caution.
with an avarage rate expected at 81.000 USD for Q2, i would expect the dividend for Q2 to be in the 0,97 to 1,05 USD range.
compared to Q1, avarage rate was at 55.000 USD in Q1 (dividend at 0,67 USD)
See why 2 investors see BWG as 2% undervalued.
Result: Fair Value of NOK235 (UNDERVALUED)
Still, the BWG story can break if freight rates reset faster than expected or if newbuild spending pressures cash flows and reduces future dividend flexibility.
Find out about the key risks to this BWG narrative.
Another View on BWG’s Valuation
The fair value narrative around BWG leans on NOK235 per share and calls the stock modestly undervalued. Our DCF model paints a different picture. On that approach, the shares trade above an estimated future cash flow value of NOK159.55, which suggests less of a cushion if conditions soften.
That split between a gentle 1.8% discount to one fair value and a premium to the SWS DCF outcome raises a blunt question. Which set of assumptions are you more comfortable leaning on when cash flows eventually normalise, and how much valuation wobble are you prepared to tolerate if freight markets cool.
Look into how the SWS DCF model arrives at its fair value.
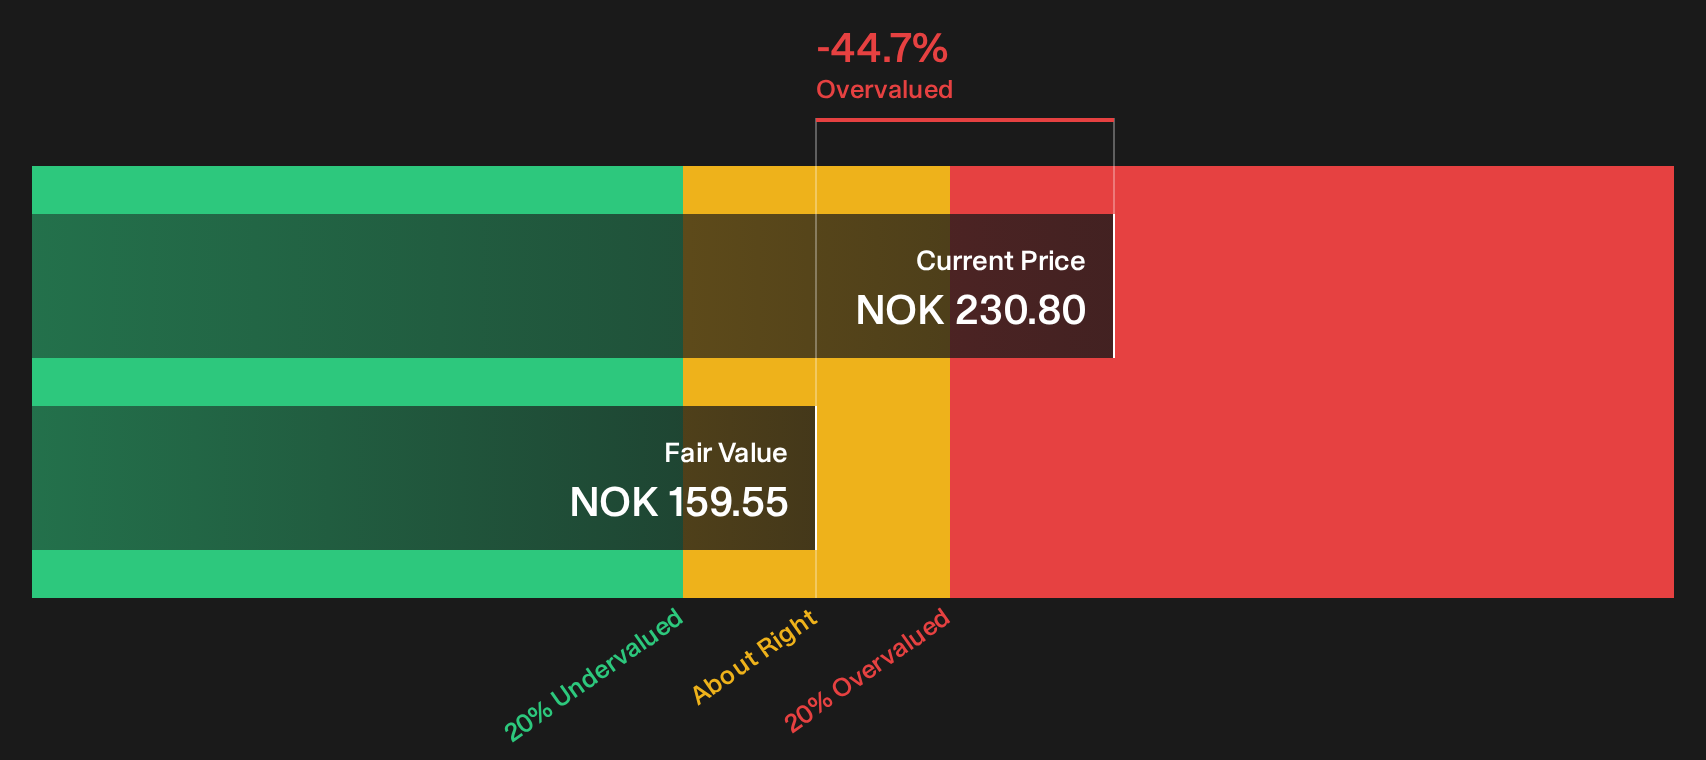
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BWG for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on BWG so far. If you see both the risk and reward threads in this story, take swift action and carefully weigh the 2 key rewards and 2 important warning signs.
Looking for more BWG-like investment ideas?
If BWG has sharpened your focus on valuation, dividends and balance sheet strength, do not stop at a single ticker when screens can widen your opportunity set.
- Target income potential by scanning steady payers with resilient yields using the 162 dividend fortresses.
- Hunt for mispriced opportunities that pair quality fundamentals with attractive entry points through the 182 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by filtering for companies that pass the 227 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com