
3 Canadian Dividend Stocks With Yield Over 3%
With US 10 year Treasury yields above 5% and borrowing costs resetting higher across global markets, many Canadian investors are paying closer attention to what actually lands in their account as cash today. Reliable dividend payers yielding more than 3% can look appealing when bond income and equity volatility are both front of mind. This article breaks down three Canadian high yield dividend stocks from this screen.
The three dividend stocks covered below are only a small sample, because the full Dividend Powerhouses screen surfaced 17 more income ideas with similarly detailed stories that are not unpacked in this article. To see the whole field and focus on what best fits your goals, head straight to the Dividend Powerhouses (3%+ Yield) screener to filter, analyze, and identify the dividend opportunities that match your highest conviction.
Sun Life Financial (TSX:SLF)
Sun Life Financial brings together a long-established insurance franchise and a sizeable asset management arm. This combination provides the type of recurring cash flow engine that can support the well covered, growing, and stable dividend profile this screener is built to highlight.
Sun Life Financial runs a broad mix of life and health insurance, retirement, and asset management operations, with Canada generating about CA$15.7b of revenue, the U.S. about CA$13.0b, Asia CA$2.6b, and its SLAM asset management arm CA$7.7b, all backed by a market value around CA$62.9b.
"Strong growth across Asian markets, particularly in Individual Protection and wealth products, is expanding Sun Life's addressable market and creating significant new revenue sources; this is reinforced by double-digit sales and CSM growth in the region year-over-year."
The real watchpoint is how one pressure on the business model ultimately filters through to earnings consistency and dividend headroom over the next few years.
That pressure point is exactly what the full narrative for Sun Life Financial unpacks in detail, including where Sun Life Financial’s dividend capacity could decouple from headline earnings volatility.

Whitecap Resources (TSX:WCP)
Whitecap Resources is a Calgary based producer that turns Western Canadian oil and gas output into a regular cash dividend stream, with its payout policy designed to keep dividends covered by production driven cash flows rather than one off financial engineering.
Whitecap Resources runs upstream oil and gas operations across Alberta, British Columbia, and Saskatchewan, generating about CA$7.2b from exploration and production activities, and carries a market value near CA$22.1b.
Income focused investors often look at Whitecap Resources for its monthly dividend record, but the more interesting story is how its growing scale and cash generation feed directly into that payout profile.
"Successful integration of Veren assets is resulting in early operational synergies, cost reductions, and improved capital efficiency, which are expected to unlock further sustainable cost savings and margin expansion over the next 6 to 12 months, directly supporting higher future earnings and free cash flow."
The real swing factor is how one shift in the balance between reinvestment needs and shareholder payouts ultimately shapes dividend headroom.
That tipping point on capital allocation is exactly what the full narrative for Whitecap Resources unpacks. It includes how Whitecap Resources balances reinvestment, dividends, and the risk of cash flow stalling.

North West (TSX:NWC)
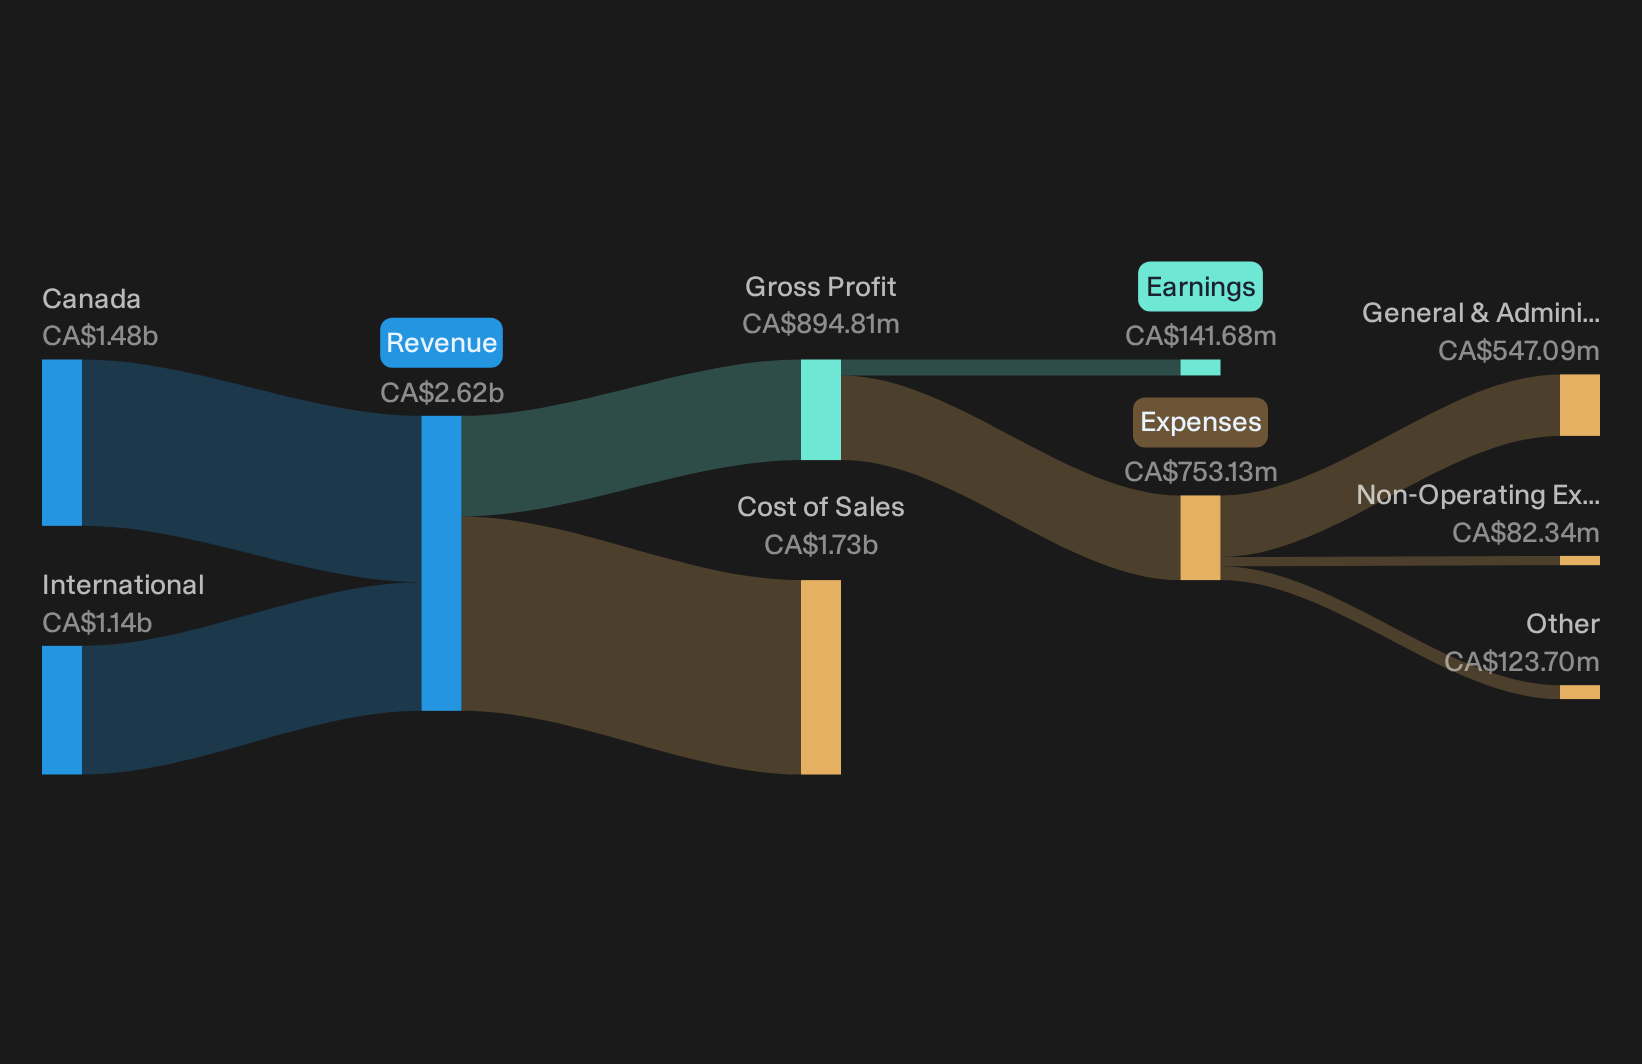
North West runs grocery, convenience, and everyday goods stores such as Northern, NorthMart, Giant Tiger, Cost-U-Less, and Alaska Commercial Company. These stores turn essential, repeat purchases in remote and rural communities into the steady cash flows needed to support a covered, consistent dividend. It generates about CA$1.5b in Canada and CA$1.1b internationally, with a market value near CA$2.5b.
North West offers a 3.13% dividend backed by essential retail cash flows, high quality earnings, and a P/E of 17.9x that looks modest versus consumer peers. Income investors get a covered payout with room for upside, although much depends on how pressure on costs and margins evolves from here.
Those cost and margin pressures are exactly why it is worth scanning the analysis report for North West to see where North West’s dividend resilience could decouple from earnings.
Seeking Fresh Alternatives Before The Crowd
Market leaders can move fast once momentum hits. Fresh ideas get picked over quickly as prices react, stories spread, and quiet opportunities start flying. Do not get caught watching; consider acting while opportunities are still emerging.
- Spot resilient balance sheets before momentum chasers notice by scanning the list of solid balance sheet and fundamentals (7 results) while these businesses remain under the radar for now.
- Track gold producers when sentiment is still mixed and before the next breakout phase by reviewing the curated 36 elite gold producer stocks.
- Position ahead of developments in industrial robotics by checking the hand picked 93 robotics and automation stocks while valuation gaps still matter.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com