
Can NetApp (NTAP) Justify Its Valuation After Record Results And Higher Guidance?
NetApp (NTAP) has been back in focus after record first quarter fiscal 2027 results, a higher outlook for the year, and strong commentary around AI driven infrastructure modernization and flash storage demand.
NetApp’s recent surge in attention sits on top of powerful price momentum, with an 88.9% year to date share price return and a 31.9% 3 month share price move that has coincided with record earnings, upgraded guidance and fresh AI focused announcements including the planned PEAK:AIO acquisition and an expanded NFL partnership. Multi year total shareholder returns above 140% show the longer term payoff investors have seen from staying invested through earlier cycles.
Scan beyond NetApp’s surge to see which other AI infrastructure players are showing similar momentum with our hand picked 87 AI infrastructure stocks today.
The sharp re rating in NetApp now raises a simple question. Are investors finally catching up with what the business is delivering, or has sentiment raced ahead of the fundamentals that support today’s valuation multiples?
Most Popular Narrative: 4% Overvalued
On the most followed narrative, NetApp screens as modestly overvalued, with a fair value of $194.19 against a last close of $201.15. This view places more emphasis on steady execution rather than on further multiple expansion.
Substantial growth in Keystone Storage-as-a-Service (up ~80% year-over-year) and increased deferred revenue (+9% year-over-year) indicate growing preference for subscription-based and as-a-service storage, supporting higher revenue visibility and margin expansion as mix continues to shift toward high-value services.
See why 49 investors see NetApp as 4% overvalued.
Result: Fair Value of $194.19 (OVERVALUED)
Still, NetApp’s reliance on hyperscaler partnerships and pressure on traditional product revenue could quickly challenge today’s valuation narrative if competitive dynamics or product mix trends shift further.
Find out about the key risks to this NetApp narrative.
Another View: NetApp Through The P/E Lens
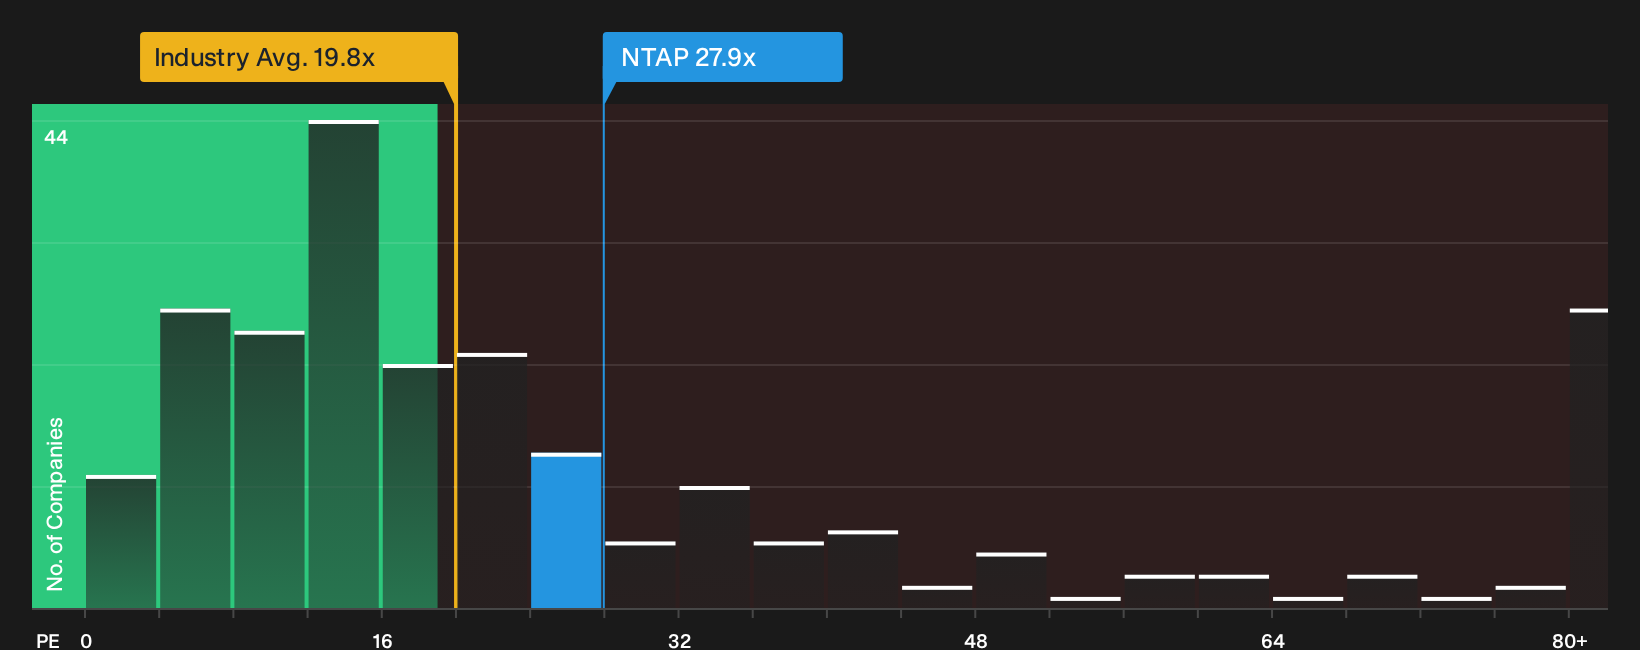
On a simple earnings multiple, NetApp tells a different story. The stock trades on a P/E of 27.9x, which sits above the Global Tech average of 19.8x, yet below the peer average of 55.4x and close to an estimated fair ratio of 28.7x. That mix of premium to the wider sector but discount to direct comparables points to a valuation that could move either toward the broader industry level or toward the fair ratio, depending on how you weigh growth and risk. Which direction do you think the market leans next?
For a closer look at what these earnings multiples imply for potential upside or downside, and how they stack up in a full breakdown, check out See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on NetApp’s value story so far. If you want to move faster than the next headline, consider both perspectives by checking 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond NetApp?
If NetApp has sharpened your focus on quality, do not stop here. The next move often comes from an idea you almost skipped past.
- Target resilient income potential by scanning for companies built to support stronger payouts using our 8 dividend fortresses.
- Hunt for mispriced opportunities where quality and valuation line up with the 32 high quality undervalued stocks.
- Zero in on financially robust businesses that can better handle shocks through the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com