
Did International ETF Launch Just Shift Invesco (IVZ) Stock Narrative?
- Invesco expanded its QQQ Innovation Suite in September 2026 by launching the Invesco Nasdaq International Innovators 100 ETF (QQI), a rules based product tracking 100 non US companies with high Innovator scores and a stated total expense ratio of 0.29%.
- The new QQI fund extends the familiar QQQ branding into international markets. It aligns Invesco’s ETF lineup with investor demand for targeted non US innovation exposure while relying on a systematic process built around research and development intensity, revenue growth and profitability.
- We will now look at how Invesco’s investment narrative could be influenced by the QQI launch and its new international innovation focus.
Scan beyond Invesco's QQI launch and compare it with a hand picked 16 high quality undiscovered gems that target similar themes across global markets.
Invesco Investment Narrative Recap
To own Invesco, you need to believe the shift toward low fee, scalable products will work in its favor, not against it. The firm already leans heavily on ETFs, index products and digital distribution, while still wrestling with pressure on margins, regulatory costs and the fact that it is currently loss making with net income of US$309.2 million in the red.
The near term swing factor is execution on product growth and cost control as assets move from higher fee active strategies into lower fee vehicles. The QQI launch adds breadth to the QQQ franchise but, by itself, does not change the central risk, which is continued fee compression and intense competition across ETFs and digital platforms.
Among recent developments, the most relevant here is Invesco’s continued emphasis on ETFs such as the Invesco S&P MidCap 400 GARP ETF and the Invesco Large Cap Value ETF. These offerings show how the business is leaning into rules based, index linked products, while the QQQ Innovation Suite, now including QQI, extends that playbook into growth and factor driven themes.
For you, the link between QQI and these other ETFs is important. It speaks to an operating focus on scale, breadth across factor, size and style segments, and potential operational efficiency if assets cluster in in house index products. The risk is that rising ETF launches across the industry and the ongoing move to low cost options keep net revenue yield under pressure just as Invesco is investing in technology and product expansion.
Invesco's narrative projects US$8.3b revenue and US$1.4b earnings by 2029. This reflects 6.4% yearly revenue growth and an earnings swing of about US$1.7b, from a loss of US$309.2 million today to the forecast level.
Discover why Invesco's fair value indicates a 10% potential upside to its current price that may not last much longer.
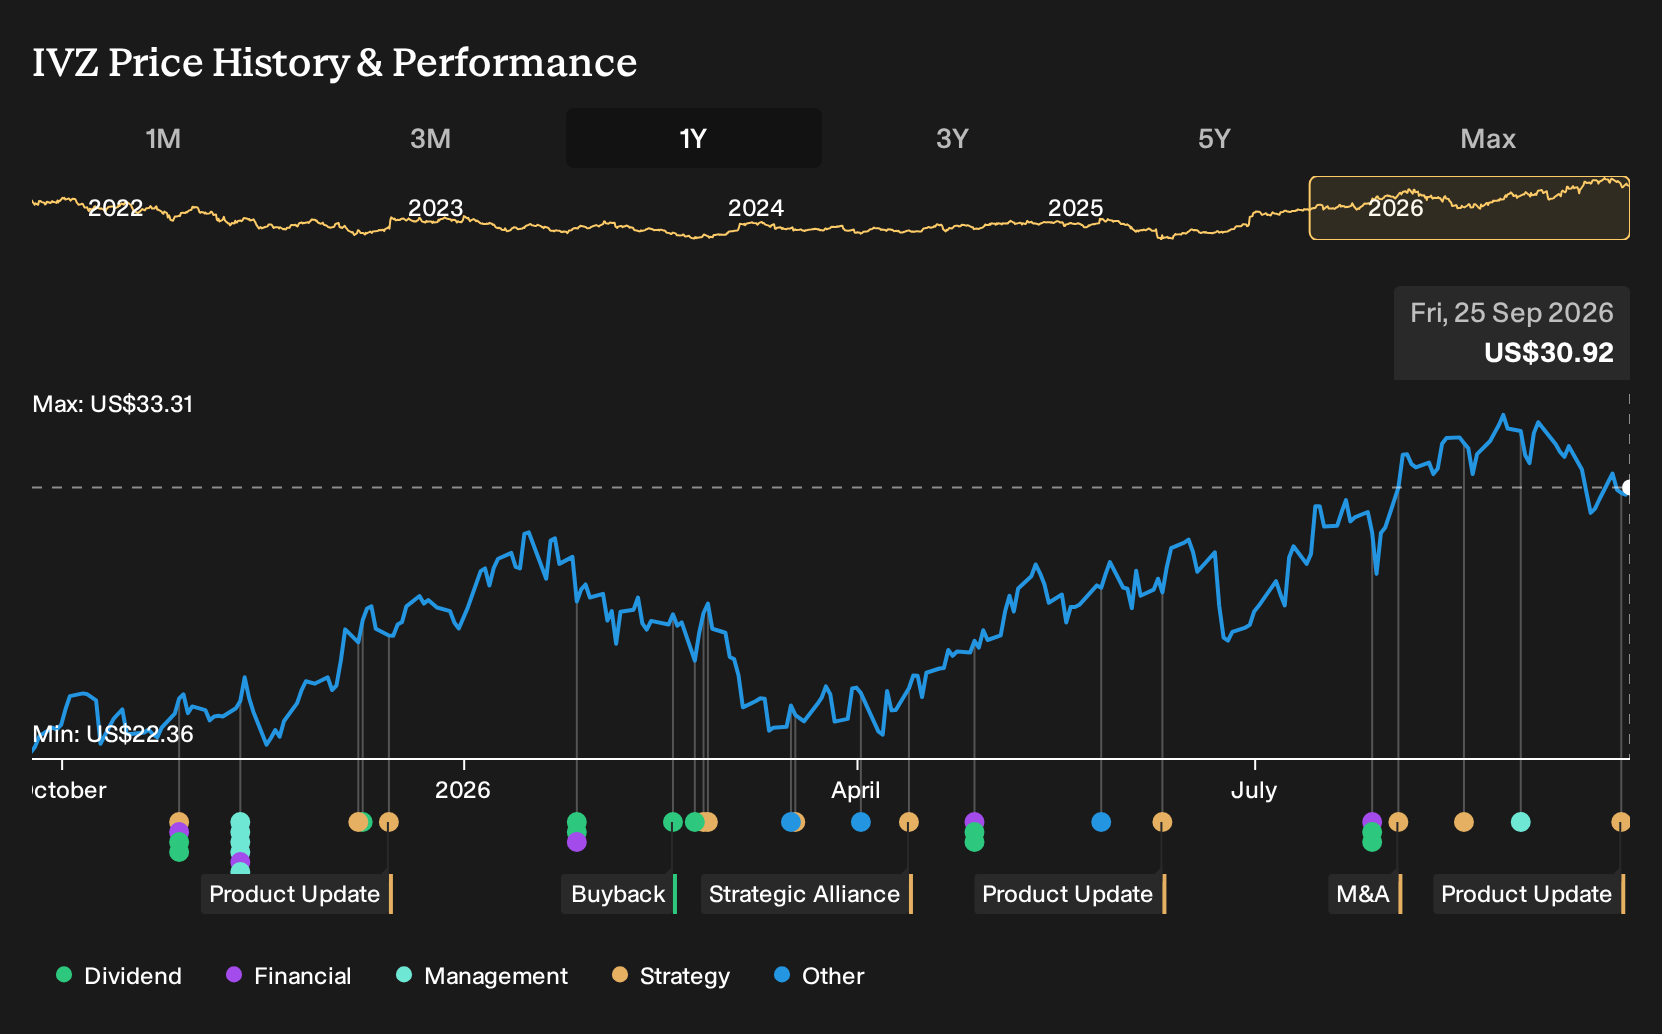
Exploring Other Perspectives
Some of the most optimistic analysts focus on a very different catalyst for Invesco. They see the MassMutual and Barings partnership and global expansion as the real swing factor, with forecasts built around revenue of about US$5.2b and earnings of roughly US$1.6b by 2029. These views were set before QQI and may evolve, so treat them as one possible storyline and compare them with your own expectations.
Explore 3 other Invesco fair value estimates, including one that suggests there could be as much as 51% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Invesco research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Invesco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Invesco's overall financial health at a glance.
Looking For More Invesco Style Investment Ideas?
If the QQI launch has you thinking about how Invesco fits into a broader portfolio, it can help to line it up against other stocks with clear, data driven traits. The Simply Wall St Screener lets you filter for different qualities so you can build a watchlist that matches your risk tolerance and income needs.
- For investors hunting for potential mispricings with solid fundamentals, start by scanning a curated set of 32 high quality undervalued stocks that may warrant a closer look alongside Invesco.
- If capital preservation sits high on your list, narrow your search to companies with sturdier finances by checking out a list of solid balance sheet and fundamentals (24 results) to compare against the profile of Invesco.
- Those who prefer a smoother ride over aggressive swings can focus on steadier performers by screening through 30 resilient stocks with low risk scores that might complement or balance a position in Invesco.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com