
How Declining Capital Returns Will Impact Standex International (SXI) Investors
- Standex International recently reported annualized revenue growth of 11.2% over the past two years and an average operating margin of 15.5%, while its return on invested capital has declined by an average of 3.8 percentage points each year.
- The mix of healthy revenue expansion and solid profitability, together with weakening returns on invested capital, points to investments that are less productive than before. This places greater focus on how effectively new projects and acquisitions are being deployed.
- We will now assess how Standex International's solid margins but declining return on invested capital could reshape the longer term investment narrative.
Compare Standex International's mix of growth and return trends with other industrial stocks that pair solid margins with disciplined capital allocation by scanning our hand picked list of solid balance sheet and fundamentals (24 results).
Standex International Investment Narrative Recap
To own Standex International, you need to believe the company can turn healthy revenue growth and a 15.5% operating margin into consistently productive investment decisions. The recent report confirms momentum in sales and profitability, while the declining return on invested capital keeps the focus on how new capacity, product launches, and bolt on deals are being put to work.
The near term catalyst is execution in high value areas such as electronics, aerospace and grid related projects, where demand trends have supported earnings growth. The biggest current risk is that acquisition driven expansion, soft spots in Scientific and Specialty Solutions, and trade or tariff costs keep pressuring returns and limit further margin progress.
Recent commentary around Standex International’s 11.2% annualized revenue growth over the last two years, alongside a 3.8 percentage point annual decline in ROIC, is the key operational update to watch. The mix of strong sales and weaker capital returns ties directly into the existing acquisition and integration risk that already sits in the story.
For you as a shareholder, this same disclosure becomes a real time scorecard on the company’s acquisition playbook and capital deployment. If integration of prior deals, footprint changes in Engraving & Hydraulics, and continued spend in electronics and aerospace do not translate into more stable ROIC, the main growth catalysts around automation and electrification start to look more execution sensitive than they first appear.
Standex International's current analyst narrative points to revenue of US$1.1b and earnings of US$164.5m by 2029, based on 7.7% yearly top line growth and an earnings increase of about US$59.7m from US$104.8m today.
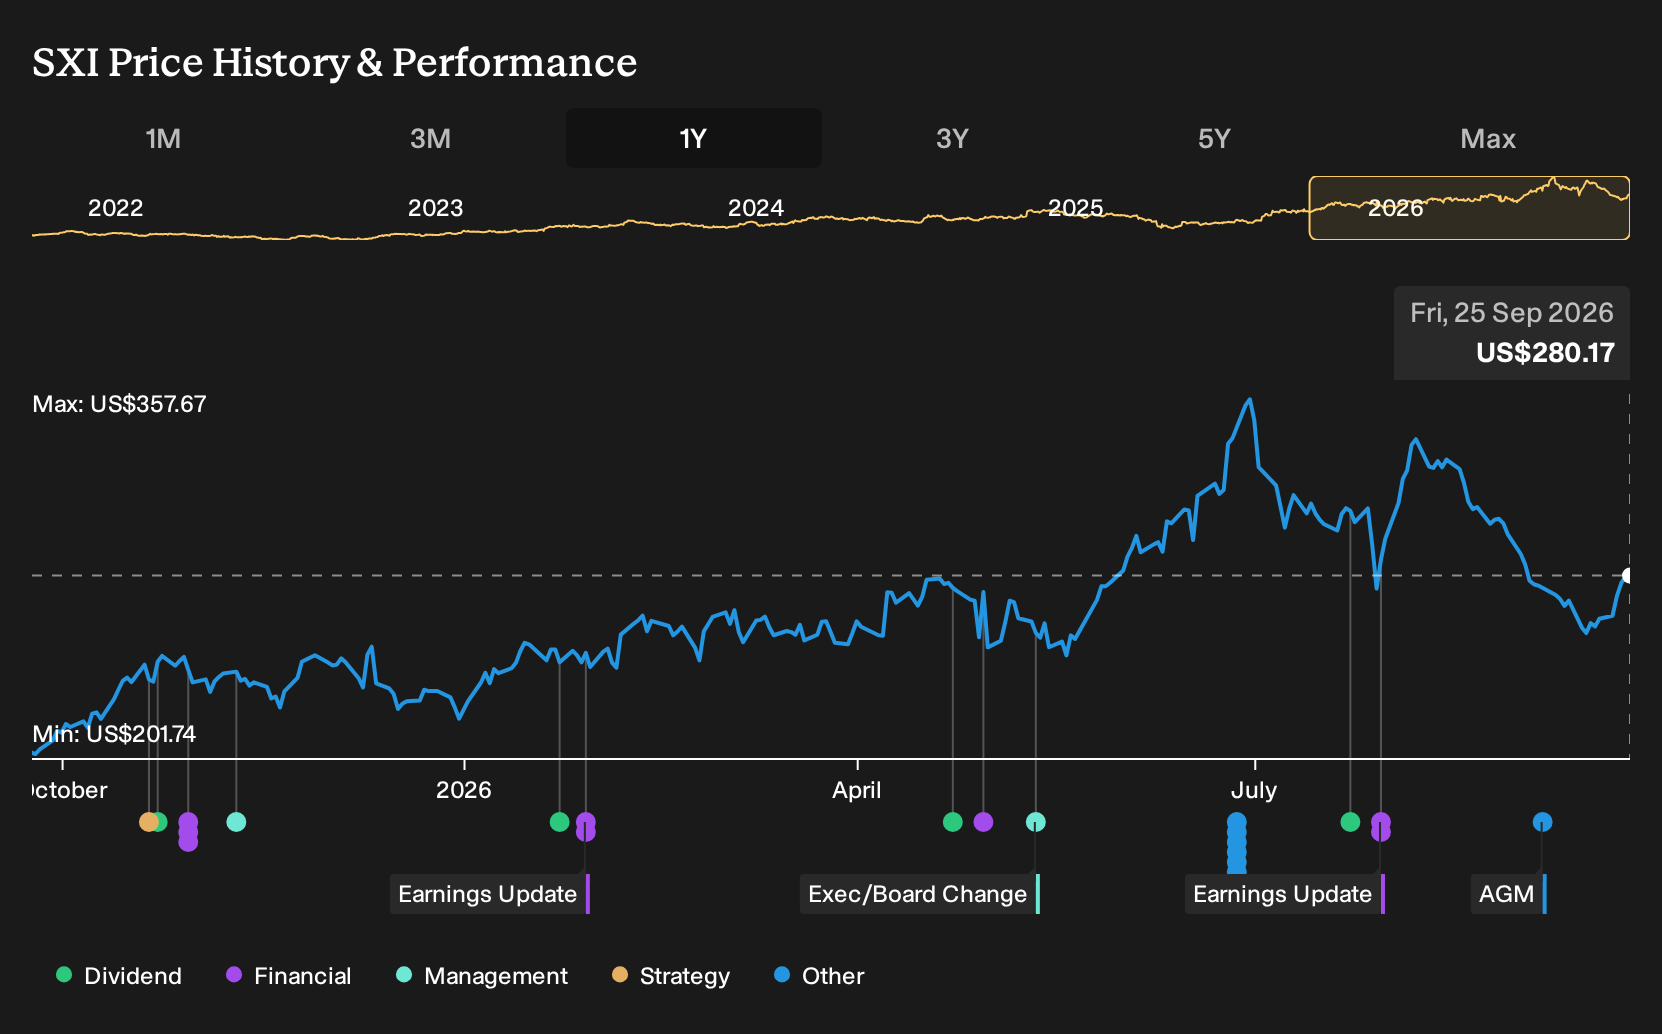
Uncover why Standex International's fair value indicates a 21% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Fair value guesses for Standex International from the Simply Wall St Community span roughly US$84 at the low end to about US$338 at the top, across 2 separate estimates. That spread, combined with acquisition and leverage risk on one side and automation or electrification tailwinds on the other, shows how far opinions can diverge and why you might want to explore several contrasting viewpoints before deciding how this story fits your portfolio.
Explore another Standex International fair value estimate, including one that suggests up to 21% potential upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Standex International research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Standex International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Standex International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Standex International?
Once you have a view on Standex International, it often helps to benchmark that thinking against other opportunities with different risk and return profiles. Using the Simply Wall St Screener, you can quickly scan for stocks that match the kind of balance sheet quality, income potential, or upside profile you want to focus on next.
- If capital preservation is high on your list, start with companies that pair robust finances with measured risk using our 30 resilient stocks with low risk scores.
- If you want a pipeline of fresh ideas that are not heavily followed, check out a curated 16 high quality undiscovered gems that show strong underlying fundamentals.
- If income is a priority, filter for reliable cash generators through a 8 dividend fortresses that screens for higher yielding options with resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com