
3 Aluminium Stocks Investors Are Watching As Tariffs Reshape Costs
Tariffs are back on the front page, and aluminium is suddenly at the centre of the story. As US–Canada trade friction pushes up can and auto body costs, and India leans harder into aluminium over copper, the companies that mine bauxite and refine alumina could see very different outcomes. This piece walks through three stocks exposed to those headlines, showing where the risks and potential openings might sit for your portfolio.
The stocks covered below are just a first cut, and the full screen surfaced 29 more aluminium and alumina producers with equally compelling narratives that are not included here. To move straight from headlines to hard data, head into the Global Primary Aluminium and Alumina Producers screener to identify, analyze, and focus on the highest-conviction ideas that fit your own criteria.
Vedanta (NSEI:VEDL)
Overview: Vedanta is a diversified natural resources group that mines and processes metals and energy, with key aluminium operations supporting India’s industrial and electronics supply chains.
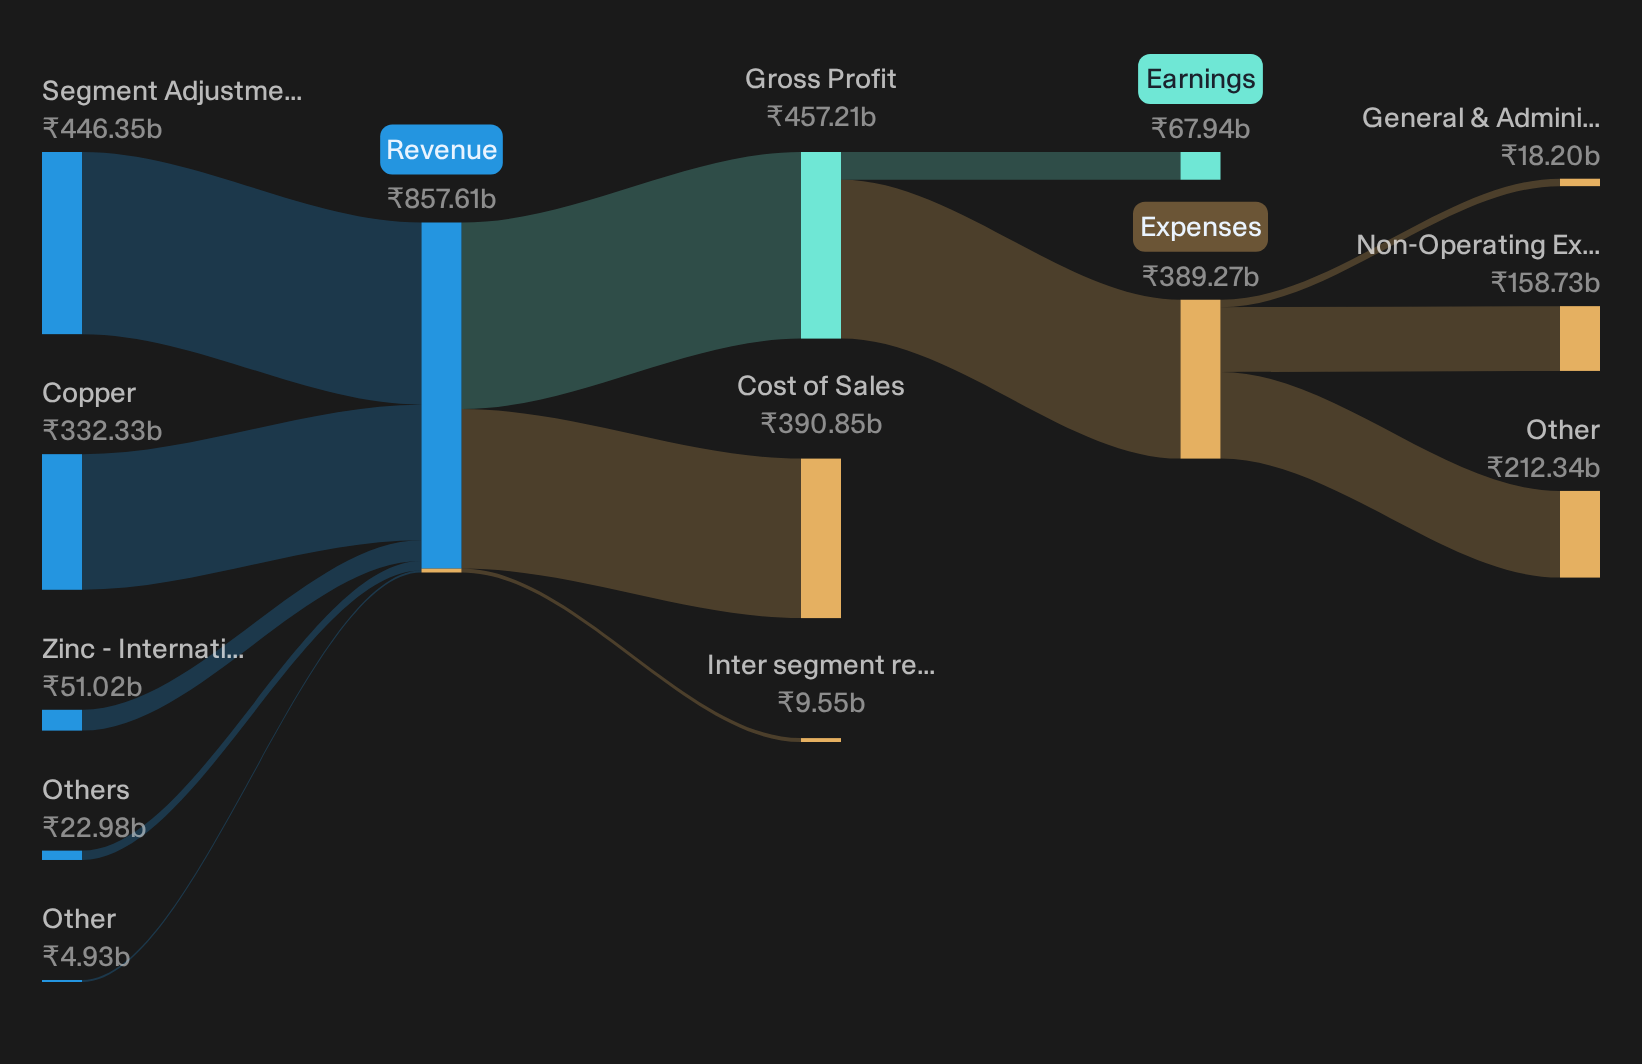
Operations: Vedanta reports ₹332,330 million from Copper and ₹446,350 million of segment adjustment, alongside smaller Zinc International and Other contributions.
Market Cap: ₹1,040.0 billion
Vedanta matters for this aluminium and alumina screener because its upstream assets plug directly into India’s shift toward aluminium heavy infrastructure and electronics. This puts its post demerger structure in a different light.
"On May 1, 2026, Vedanta demerged into 5 independent entities. Aluminium, Oil & Gas, Power, and Steel are now separate listed companies."
What happens when one unresolved cost and pricing pressure inside Vedanta’s aluminium value chain breaks in either direction will shape that story.
When that cost pressure finally moves, the full narrative for Vedanta shows how Vedanta’s demerger could accelerate value or reveal risks that current headlines are masking.
Century Aluminum (CENX)
Overview: Century Aluminum produces primary aluminum and alumina across the U.S. and Iceland, giving investors focused upstream exposure to aluminium pricing.
Operations: Century Aluminum reports US$2.7b in revenue from Primary Aluminum, with US$2.1b from the United States and US$545 million from Iceland.
Market Cap: US$3.8b
Century Aluminum is the pure upstream play in this screener. It ties your exposure directly to smelting capacity, alumina supply, and tariff supported pricing rather than a mix of downstream products.
"The planned restart of more than 50,000 tonnes per year at Mt. Holly, supported by a new power agreement through 2031 and an estimated full run rate contribution of about US$25 million in EBITDA per quarter from Q3 2026, directly targets higher shipment volumes and earnings."
What happens when one unresolved pressure in Century Aluminum’s power costs and tariff support shifts will matter a lot for those margins.
That power and tariff mix is exactly what the full narrative for Century Aluminum unpacks, revealing how Century Aluminum’s earnings profile could be accelerating, stalling, or quietly decoupling from peers.

Gravita India (NSEI:GRAVITA)
Overview: Gravita India recycles and manufactures lead products, aluminium alloys, plastics and copper alloys, supplying secondary metals to industrial customers.
Operations: Gravita India generates about ₹38.0 billion from Lead, ₹3.8 billion from Aluminium, ₹806 million from Plastics and ₹4.3 billion from Segment Adjustment, with smaller contributions elsewhere.
Market Cap: ₹108.9 billion
Gravita India fits this aluminium focused screener as a recycler that feeds secondary alloys back into global supply chains. Recent investment decisions suggest management is leaning into that role as metal flows and tariffs shift.
"Approval to set up a copper recycling plant at Mandvi, Gujarat, with planned capex of ₹1,600 million and an installed capacity of about 29,400 MTPA, funded through internal accruals and intended to expand Gravita India’s non ferrous metal recycling portfolio and product mix."
How one unseen pressure in Gravita India’s metal mix and recycling margins ultimately shifts will influence how that expansion is experienced.
That hidden pressure is exactly where the full narrative for Gravita India pushes further, showing how Gravita India’s recycling bets could be accelerating or quietly stalling against peers.

Seeking Alternatives Before The Crowd?
Fresh themes are breaking out while attention stays glued to aluminium. Spot under the radar for now ideas with real momentum before the window starts dropping, act now.
- Chase durable income streams by scanning a curated pool of high yield payers through the 160 dividend fortresses before those payouts get fully priced in.
- Track quiet earnings momentum by zeroing in on a hand picked 182 high quality undervalued stocks while sentiment is still catching up.
- Position ahead of potential infrastructure tailwinds by filtering a focused 40 power grid technology and infrastructure stocks while these tickers remain off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com