
Acadia Pharmaceuticals (ACAD) Stock May Be Mispriced After Mixed Phase III Push
Acadia Pharmaceuticals has seen a sharp pullback in recent weeks, and the slide puts fresh focus on a simple question for investors who care about valuation: does the current share price line up with what the company is earning today?
- The stock is down 30.1% over the past month, which puts recent sentiment under pressure and brings the earnings-based valuation story to the forefront.
- Mixed Phase II data for remlifanserin in Alzheimer's disease psychosis and the decision to press ahead with Phase III at the 60 mg dose can influence how investors think about Acadia Pharmaceuticals' long term earnings power and risk profile.
- There is a second opinion on Acadia Pharmaceuticals worth weighing. See what analysts think Acadia Pharmaceuticals's shares could be worth.
The issue now is whether Acadia Pharmaceuticals' current share price is adequately supported by its earnings when set against a Fair Ratio benchmark.
If you want to stress test this same earnings question beyond Acadia Pharmaceuticals, it can help to compare it with 32 high quality undervalued stocks.
Is Acadia Pharmaceuticals a Bargain on Earnings?
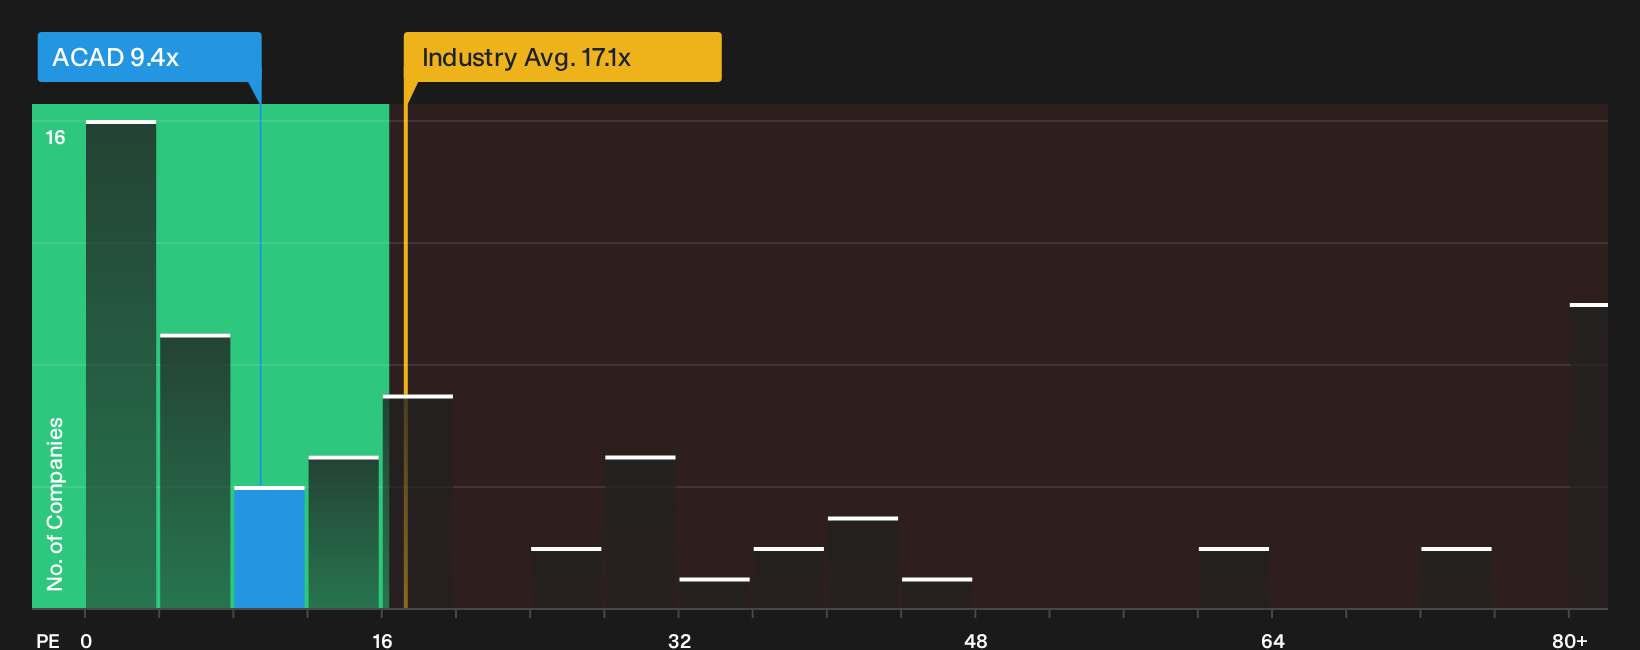
The P/E ratio is a useful anchor for Acadia Pharmaceuticals because the discussion is about what investors pay today for each dollar of current earnings. On this measure, the stock trades on a P/E of 9.4x, which is well below the Biotechs industry average of 17.1x and far under the peer group at 61.2x. A Fair Ratio model, which adjusts for the company’s growth outlook, profitability, size and risk profile, also points to a richer multiple than where the shares currently change hands. As a result, the present P/E screens as undervalued on this framework.
Because the latest move to push remlifanserin into Phase III comes after mixed Phase II data, the low P/E suggests investors are applying a heavy discount to Acadia Pharmaceuticals despite that pipeline commitment. Anyone weighing the shares has to decide whether the current trial and wider product set justify a P/E that sits this far below both the sector and peer benchmarks. Explore the numbers behind Acadia Pharmaceuticals's P/E valuation.
The Acadia Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St extend the Acadia Pharmaceuticals valuation puzzle by mapping out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today, and they sit on the Community page. Rather than stopping at a single ratio or model output, they lay out the future conditions that number relies on so you can monitor over time whether those assumptions stay intact or start to fray.
The community views on Acadia Pharmaceuticals split between those who see cautious opportunity and those who worry the bar is already high.
Bull case: 28% undervalued
ACADIA’s strategy suggests it is trying to evolve from a binary biotech story into a more durable specialty pharma model, one rooted in long term patient management…
Discover why this Narrative puts Acadia Pharmaceuticals at 28% undervalued.
Bear case: roughly fairly valued
The current valuation implies the market is already crediting ACADIA Pharmaceuticals with substantial success for DAYBUE, NUPLAZID, and an estimated multi billion dollar CNS pipeline even though regulatory, pricing, and dilution risks remain unresolved…
Explore why this Narrative puts Acadia Pharmaceuticals at roughly fairly valued.
One more Acadia Pharmaceuticals check that belongs beside the price tag
Before you focus only on what Acadia Pharmaceuticals earns for each dollar of share price, it is worth seeing who is steering the business and how their pay lines up with your interests. See who runs Acadia Pharmaceuticals and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com