
Komatsu Stock Lands Crawford Nickel Equipment Deal
- Canada Nickel Company announced it has selected Komatsu and SMS Equipment to supply more than 300 load, haul, and support machines for the Crawford Nickel Project, with an estimated current value of about CAD 1,500 million over the mine’s planned 40 year life, following a competitive vendor process.
- The win highlights how Komatsu’s automation and electrification technology is being used in large scale, low carbon mining projects. Detailed fleet, support, and financing agreements for Crawford are still to be negotiated by the first quarter of 2027.
- We will now look at how this long duration, low carbon mining fleet award could reshape Komatsu's broader investment narrative.
Scan beyond Komatsu and this Crawford contract, and size up other mining and industrial players that may be benefiting from electrification and automation tailwinds with our hand picked 93 robotics and automation stocks
Komatsu Investment Narrative Recap
To own Komatsu, you need to believe that heavy equipment demand and mining investment stay healthy enough for the Construction, Mining and Utility segment to support steady earnings, even after the recent hit to net margins and profit. The Crawford fleet award fits that story, but on its own does not transform near term fundamentals or fix soft spots in Japan and Indonesia.
The key near term swing factor remains how quickly underlying demand and high inventory levels normalize, and whether pricing power offsets any tariff or input cost pressure. The biggest risk is that weak regional markets and cautious customer capex linger, which would keep earnings recovery slow and working capital tied up.
The completed share buyback program, with ¥99,999.99 million spent to retire 15,303,700 shares, is the most relevant recent announcement for this Crawford news. A shrinking share count can magnify the effect of any incremental mining wins such as Crawford and Reko Diq on per share metrics, provided core operations stay resilient.
For you as a shareholder, the combination of a long duration mining equipment pipeline, a focus on low emission technology, and an executed repurchase plan ties directly into the main catalysts and risks. Mining contract visibility and aftermarket revenue support the story, while the potential for slower earnings growth than the broader JP market keeps execution risk front and center.
What The Current Komatsu Consensus Is Pricing In
Komatsu's narrative projects ¥4,717.6b revenue and ¥456.6b earnings by 2029. This assumes 3.4% yearly revenue growth and an earnings increase of about ¥75.5b from current earnings of ¥381.1b.
Uncover why Komatsu's fair value indicates an 11% potential downside to its current price that leaves little room for error.
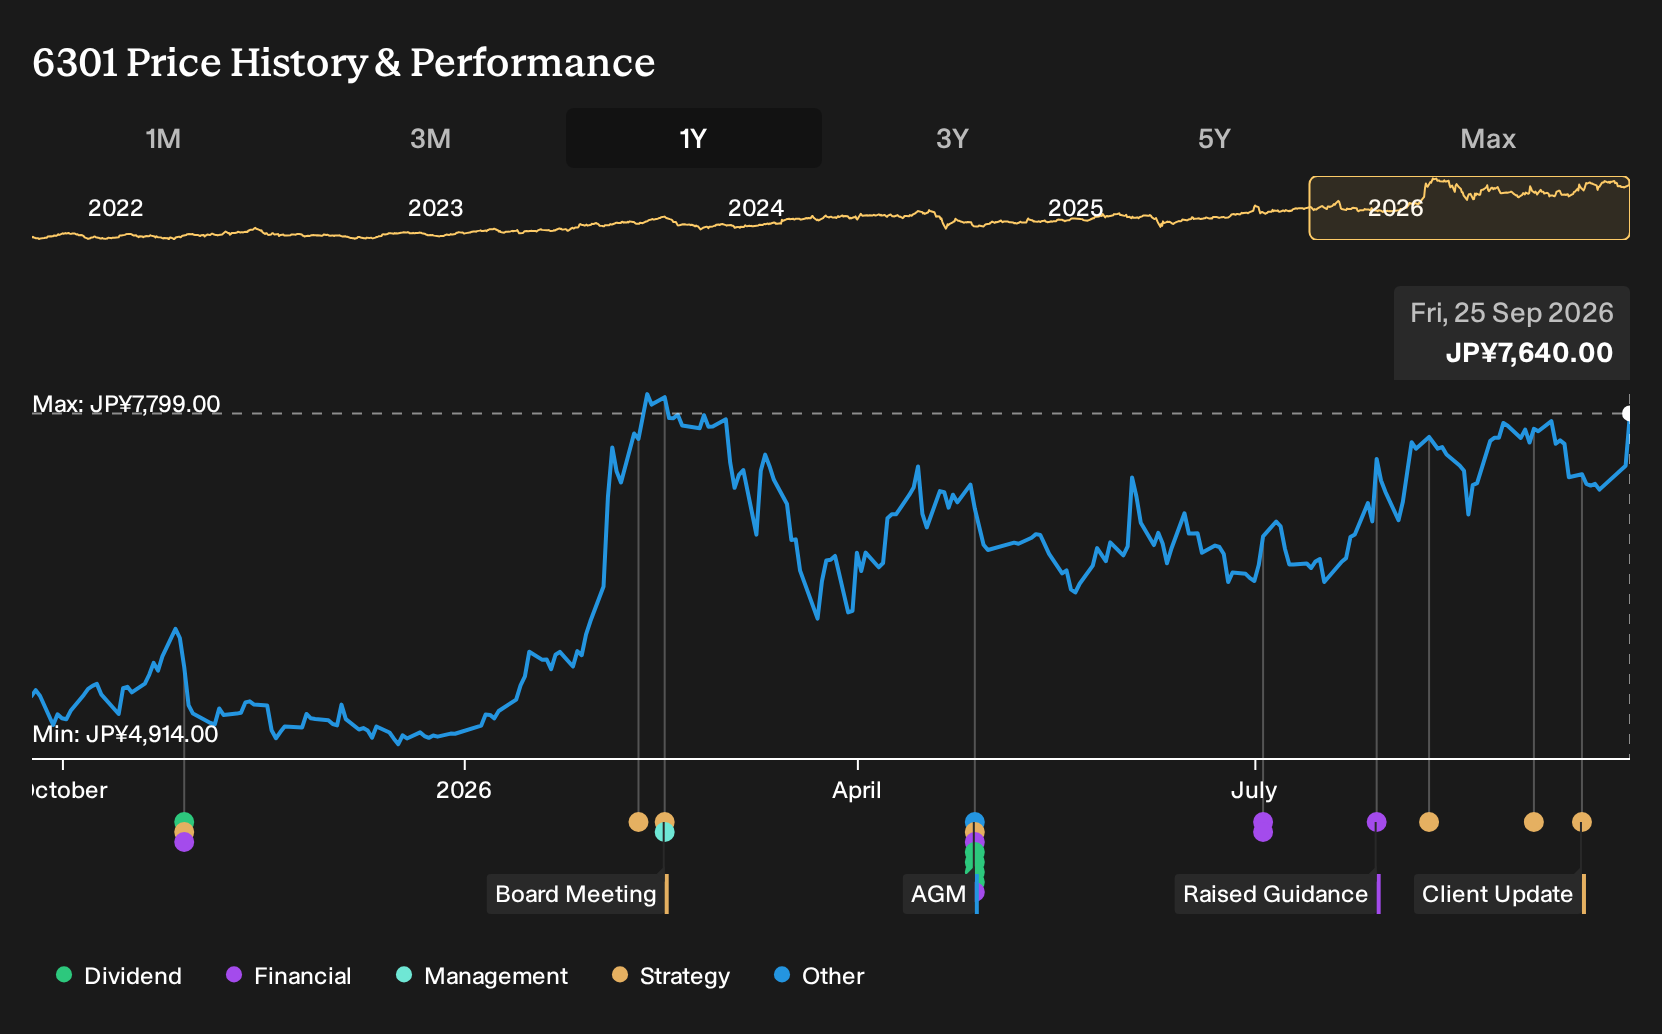
Exploring Other Perspectives
Some of the most optimistic analysts focus on Komatsu’s higher margin businesses as the real catalyst. Before this Canada Nickel fleet news, the bullish camp was already pencilling in revenue of about ¥5,189.1b and earnings near ¥594.0b by 2029. That is far above consensus, and this kind of contract could eventually push those narratives even further apart. You can treat this as a reminder that reasonable investors can look at the same numbers and reach very different conclusions, so it pays to explore several viewpoints before deciding how you feel about Komatsu.
Explore another Komatsu fair value estimate, including one that suggests as much as 10% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent research.
- A great starting point for your Komatsu research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Komatsu. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easier to evaluate Komatsu's overall financial health at a glance.
Looking For More Ideas Beyond Komatsu?
Once you have formed a view on Komatsu, it can help to compare your thesis with opportunities in other sectors and regions using the Simply Wall St screener.
- If you want potential value on your side, scan a curated set of companies that pair solid fundamentals with attractive pricing using our 18 high quality undervalued stocks.
- For investors who care about resilience first, focus on businesses with stronger balance sheets and sturdier financial footing through the list of solid balance sheet and fundamentals (22 results).
- If you are searching for under followed opportunities, broaden your watchlist with a hand picked 74 high quality undiscovered gems that combine quality metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com