
Does Foldable iPhone Launch Change The Bull Case For Apple (AAPL)?
- Apple recently rolled out the iPhone Duo, its first foldable phone, alongside the iPhone 18 Pro family and Apple Watch Series 12, with a strong focus on on device Siri AI and tighter ecosystem integration.
- The move into foldables and AI heavy features signals Apple’s push to keep hardware pricing power and reinforce services usage as competition in premium smartphones intensifies.
- Next, the focus shifts to how this AI centric iPhone Duo launch could reshape Apple’s investment narrative for long term holders.
Scan how investors are pricing this Apple AI hardware moment against other potential breakouts by reviewing the hand picked list of 87 AI infrastructure stocks in the same theme.
Apple Investment Narrative Recap
To own Apple, you need to believe its AI centric devices, services bundle, and tightly linked hardware ecosystem can keep users loyal and willing to pay premium prices, even as growth expectations moderate. The near term swing factor is whether the iPhone Duo and iPhone 18 cycle actually translate into meaningful hardware and services demand without putting excessive pressure on costs.
The biggest risk right now sits in execution around AI features and device differentiation, while regulatory, legal, and supply chain issues simmer in the background. Recent launches and ecosystem tweaks matter at the margin, but they do not yet change the core story of a mature giant fighting to keep margins and upgrade intent intact.
The Apple Pay rollout in India looks closest to the kind of catalyst that fits this Siri and on device AI push. It extends Apple further into a large market where the installed base can support future services and payments revenue, even if the initial rollout skips direct integration with the dominant UPI system.
For you as an investor, that India move ties directly into the long term thesis of a higher services mix and deeper ecosystem engagement, especially across emerging markets. It also sits alongside other AI and health upgrades as proof that Apple is still working to widen its ecosystem reach while dealing with legal settlements, cost headwinds, and labor disputes that may weigh on execution if they intensify.
Apple's narrative projects US$616.5b revenue and US$164.4b earnings by 2029. This implies 9.7% yearly revenue growth and an earnings increase of about US$35.5b from US$128.9b today.
Uncover why Apple's fair value indicates a 5% potential downside to its current price, leaving little room for error.
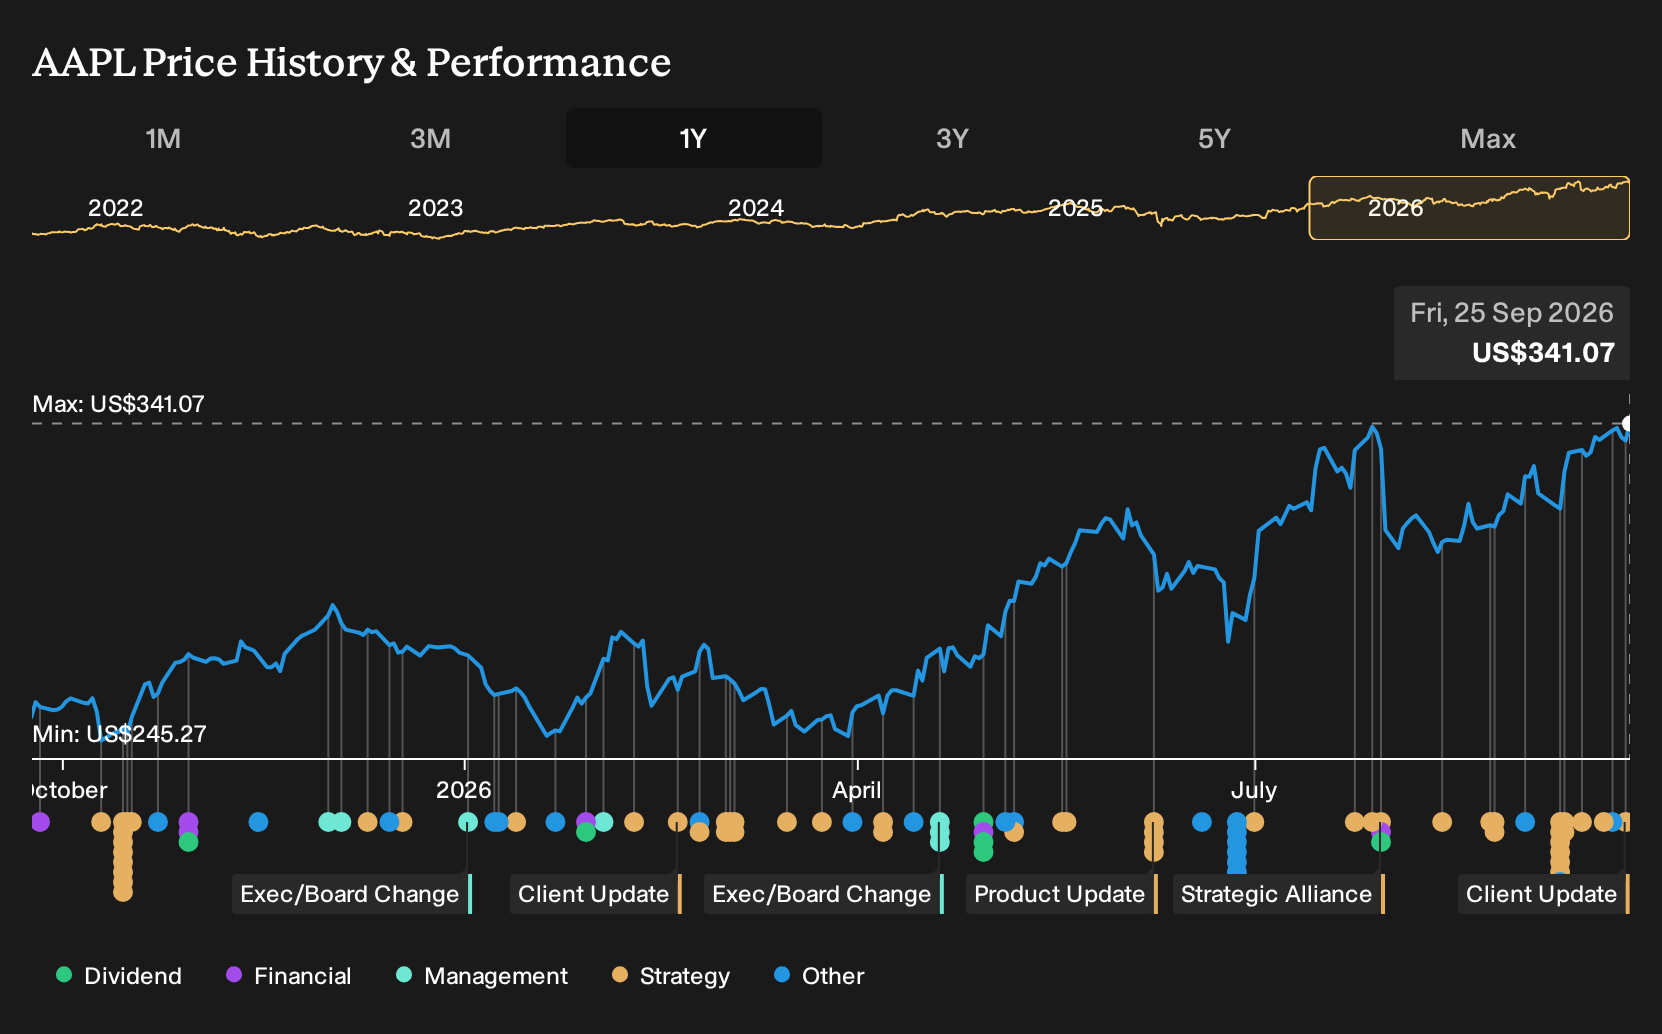
Exploring Other Perspectives
Some of the lowest Apple analysts focus on regulatory risk around the App Store instead of AI hardware upside. Before this iPhone Duo news, they were working off revenue expectations of about US$561.5b and earnings of roughly US$147.4b by 2029, which supports a much more cautious story. Use that spread to compare different narratives for yourself.
Explore 42 other Apple fair value estimates, including one that suggests as much as 46% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Apple research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Apple. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Apple's overall financial health at a glance.
Looking For More Apple Adjacent Investment Ideas?
If this Apple story has you thinking about where else AI, cash generation, and balance sheet strength could matter, use the Simply Wall St Screener to map out a wider opportunity set before making any moves.
- For potential mispriced quality, scan the 32 high quality undervalued stocks that combine fundamentals with a gap between market price and underlying metrics.
- If income and resilience matter most to you, check out the 8 dividend fortresses that may offer higher yields with a focus on sustainability.
- For investors who want financial robustness first, start with the list of solid balance sheet and fundamentals (24 results) and filter for businesses with stronger capital structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com