
ServisFirst Bancshares (SFBS) Could Be 19% Undervalued On Its Latest Dividend Signal
ServisFirst Bancshares (SFBS) set its latest income signal on September 21, 2026, when the board approved a quarterly cash dividend of $0.19 per share for third quarter shareholders.
ServisFirst Bancshares shares trade at $41.31, with a 1-day share price return of 0.15% and a year-to-date share price gain of 15.04%. The 1-year total shareholder return of 1.97% contrasts with a much stronger 66.29% total shareholder return over three years, suggesting recent momentum has cooled after a stronger multiyear run as investors weigh income signals like the latest dividend against the broader risk and growth profile.
Scan how ServisFirst Bancshares compares with other income focused financials by reviewing our hand picked 8 dividend fortresses, now shaping the market for yield hunters.
ServisFirst Bancshares appears to be a solid regional lender based on recent earnings and dividend signals, yet the share price has cooled after earlier gains. Is the current valuation giving you a fair deal on the underlying franchise?
Most Popular Narrative: 16% Undervalued
ServisFirst Bancshares is priced at $41.31 while the most followed valuation story pegs fair value at $49, leaving a double digit gap for investors to judge.
Expansion of commercial lending teams and ongoing hiring in key Southeastern markets positions the company to capitalize on robust population and business growth in the Sun Belt, supporting above-average organic loan and deposit growth, which is likely to drive top-line revenue and long-term earnings growth.
Increasing merchant services and treasury management fee initiatives, combined with a push to raise penetration rates among existing business customers, are expected to accelerate noninterest income growth and diversify revenue streams, enhancing overall profitability and margins.
See why 3 investors see ServisFirst Bancshares as 16% undervalued.
Result: Fair Value of $49 (UNDERVALUED)
Still, rising credit costs tied to higher charge offs and ongoing pressure on deposit growth could quickly weaken the ServisFirst Bancshares earnings story that investors are watching.
Find out about the key risks to this ServisFirst Bancshares narrative.
Another View on ServisFirst Bancshares Valuation
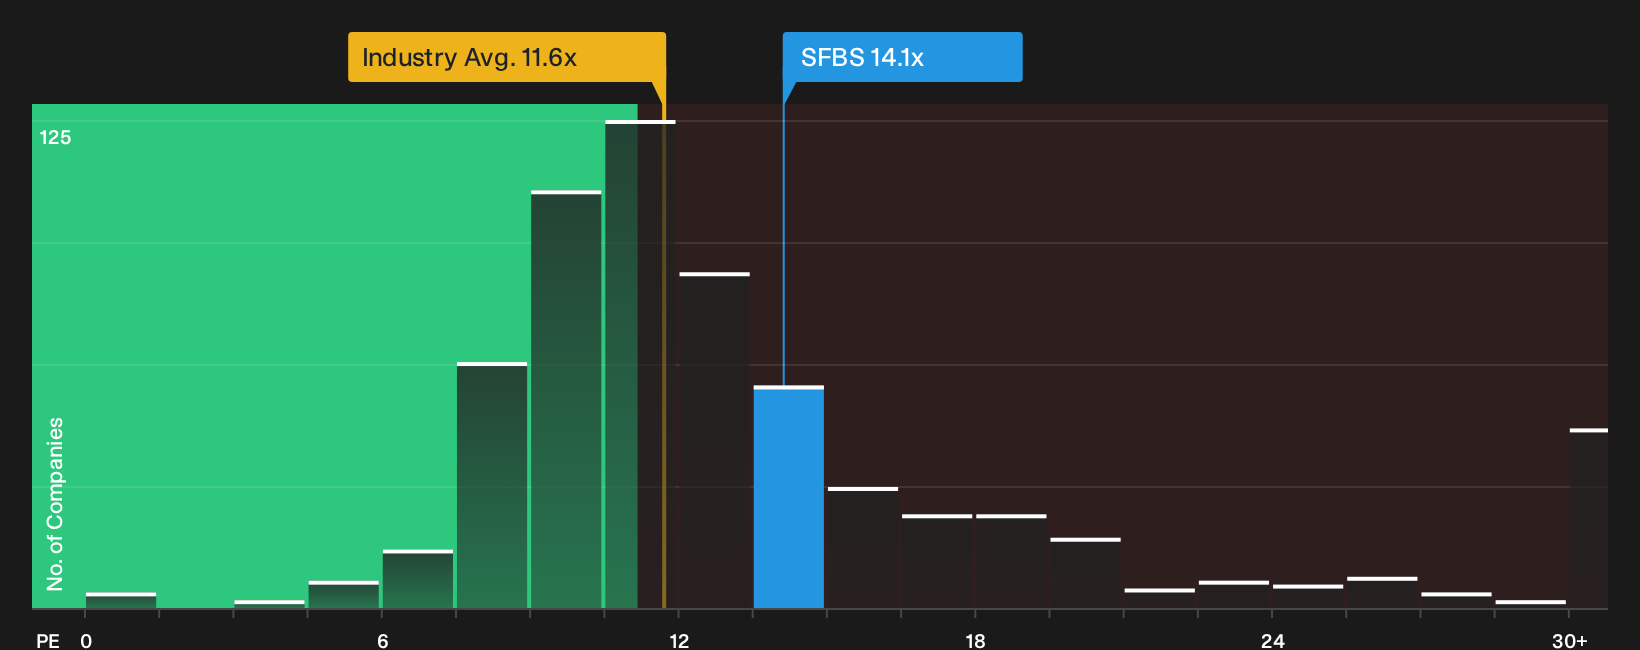
The earlier fair value of $49 for ServisFirst Bancshares leans on future earnings forecasts and analyst targets. On current numbers, the stock trades on a P/E of 14.1x, compared with 11.6x for the US Banks industry and a fair ratio of 14x. This points to a relatively full earnings multiple with limited margin for error.
The gap between ServisFirst Bancshares and both peers and the fair ratio suggests investors are already paying up for quality. The key question is whether you think the business can keep justifying that premium, or if you would rather wait for a cheaper entry and let the valuation work for you instead of against you.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around ServisFirst Bancshares valuation and income profile can feel messy, so check the numbers yourself and decide how much risk and upside you really see. To get a balanced snapshot of both sides of the debate, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ServisFirst Bancshares?
If ServisFirst Bancshares has your attention, do not stop here. Broaden your watchlist with fresh ideas that match your goals and risk comfort.
- Target potential bargains by scanning a curated set of quality companies that look mispriced using the 32 high quality undervalued stocks.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (24 results) so you are not relying on hope when conditions get tougher.
- Get ahead of the crowd by hunting through 16 high quality undiscovered gems before the wider market starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com