
American Water Works Company (AWK) Opens Training Center As Investors Ask If Resilience Is Priced In
American Water Works Company (AWK) has opened a new US$2.2 million training center in Gary, Indiana, using a mini city setup to build field, safety and operational skills for its workforce.
Recent headlines for American Water Works Company have focused on workforce training, flood recovery support and source water protection programs across several states, yet the share price has eased, with a 7 day share price return of 3.67% lower and a 30 day share price return of 4.79% lower. Despite that softer recent stretch, the stock shows a small positive year to date share price return of 0.45%. Total shareholder return over 3 years is 13.73% higher, but 5 year total shareholder return is 13.38% lower, pointing to momentum that has cooled compared with earlier periods.
Spot under-the-radar utilities that share similar long-term themes around infrastructure, reliability and regulated earnings by scanning our curated 30 resilient stocks with low risk scores.American Water Works Company looks like a solid regulated utility with training, infrastructure and source water programs all pulling in the same direction. After the recent share price slip, is that resilience already fully priced in?
Most Popular Narrative: 8% Undervalued
American Water Works Company last closed at $130.91, while the most followed narrative anchors fair value at about $141.45, using a 7.24% discount rate and a long term capital plan that leans heavily on regulation and acquisitions.
Heightened regulatory and societal focus on water quality and infrastructure modernization now aligns with a roughly US$48b capital plan over 10 years and US$1.8b already deployed in the first half of 2026. This supports rate base expansion that can flow through to revenue and earnings over time.
See why 34 investors see American Water Works Company as 7% undervalued.
Result: Fair Value of $141.45 (UNDERVALUED)
Still, the narrative around American Water Works Company could be challenged if the roughly US$48b capital plan or the Essential Utilities merger runs into regulatory or integration setbacks.
Find out about the key risks to this American Water Works Company narrative.
Another View: What Market Multiples Say About American Water Works Company
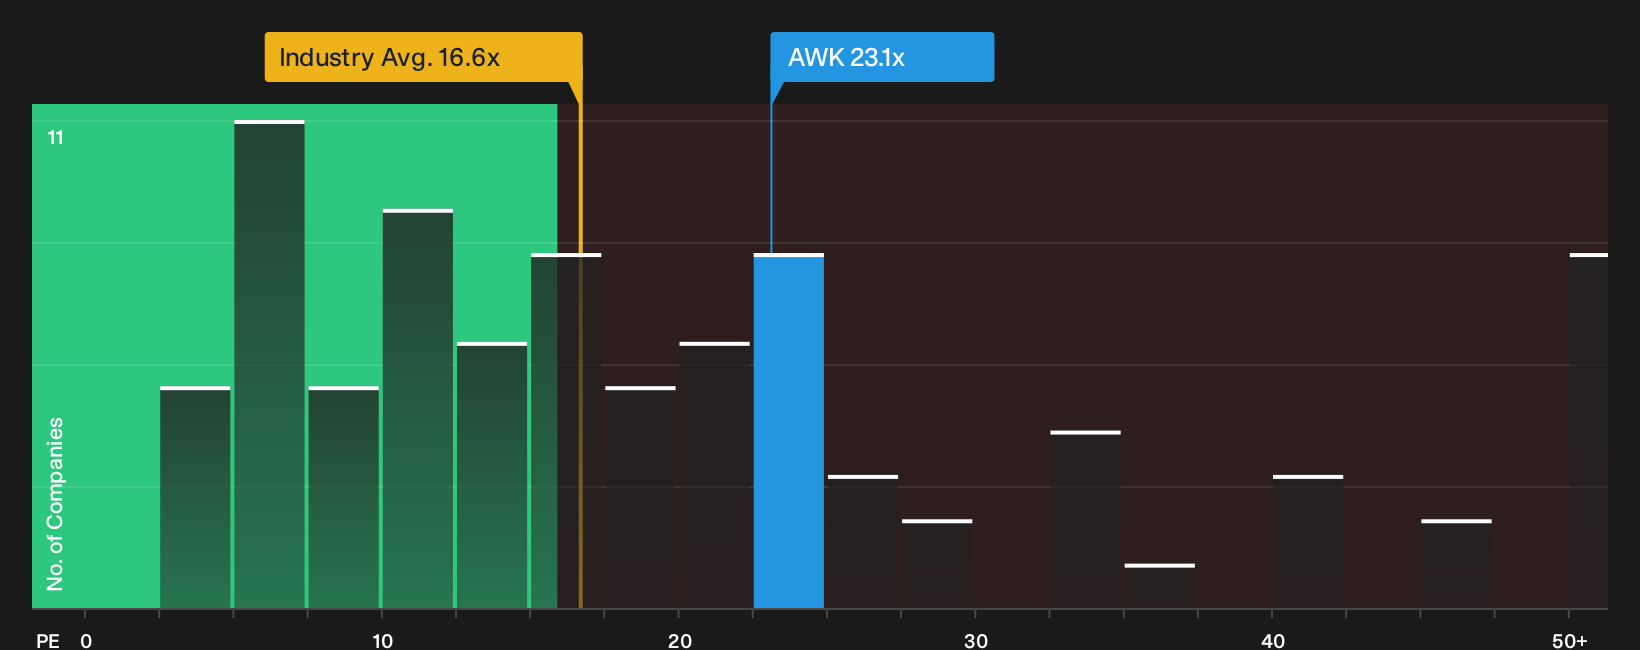
The narrative around American Water Works Company leans on a fair value of $141.45, yet the P/E of 23.1x tells a different story. That valuation sits above the global water utilities group at 16.6x and even above peers at 22.3x, while the fair ratio is 22x. In practice, that means the share price already carries a premium that could shrink if sentiment cools or growth expectations soften. Is this a quality premium you are comfortable paying, or a valuation risk you would rather avoid?
To see how that premium stacks up against the underlying numbers, take a closer look at the detailed valuation workup in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around American Water Works Company can either paralyze you or push you to look closer at the data yourself and move decisively. Take a moment to weigh both sides with the 2 key rewards and 2 important warning signs.
Looking for more American Water Works Company style ideas?
If American Water Works Company has you thinking harder about quality and valuation, do not stop here. Broaden your watchlist by lining up a few contrasting ideas that match your risk appetite and return goals.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that surfaces companies with financial strength front and centre.
- Pursue upside potential by checking the 32 high quality undervalued stocks that highlights stocks where quality metrics and current pricing look out of sync.
- Hunt for less crowded opportunities through the 16 high quality undiscovered gems that focuses on quieter stories with solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com