
United Parcel Service (UPS) Could Be 19% Undervalued On Rate And Fuel Pressure
United Parcel Service (UPS) is back in focus after a sharp move in bond markets and higher fuel costs weighed on the stock, while an analyst downgrade added another layer of pressure.
Over the past few months, United Parcel Service has absorbed a mix of stock specific news and broader market shocks, with rising Treasury yields and fuel costs feeding into a 30 day share price return of down 11.1% and a 90 day share price return of down 13.1%. At the same time, the 1 year total shareholder return of 19.6% contrasts with a 3 year total shareholder return of down 28.4% and a 5 year total shareholder return of down 34.4%, suggesting recent momentum has cooled even after a stronger year for investors who reinvested dividends.
Scan how United Parcel Service compares with other transport and logistics stocks facing similar rate and fuel pressures by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
The recent pullback has reset United Parcel Service to levels some investors view as a fresh opportunity, while others prefer to wait for more weakness. Where does the current valuation leave you on that spectrum?
Most Popular Narrative: 19% Undervalued
United Parcel Service is currently trading at $93.96, while the most followed narrative pegs fair value at $115.96. This leaves a sizeable gap that hinges on execution of cost savings and mix improvements rather than broad market sentiment.
UPS anticipates $3.5 billion in annual cost reductions for 2025 through variable, semi-variable, and fixed cost savings, positioned to exceed the revenue loss from Amazon. This should improve profitability and free cash flow.
See why 215 investors see United Parcel Service as 19% undervalued.
Result: Fair Value of $115.96 (UNDERVALUED)
Still, United Parcel Service faces real swing factors, including global trade policy changes and the planned cut to Amazon volumes, which could unsettle revenue and execution.
Find out about the key risks to this United Parcel Service narrative.
Another View On United Parcel Service Valuation
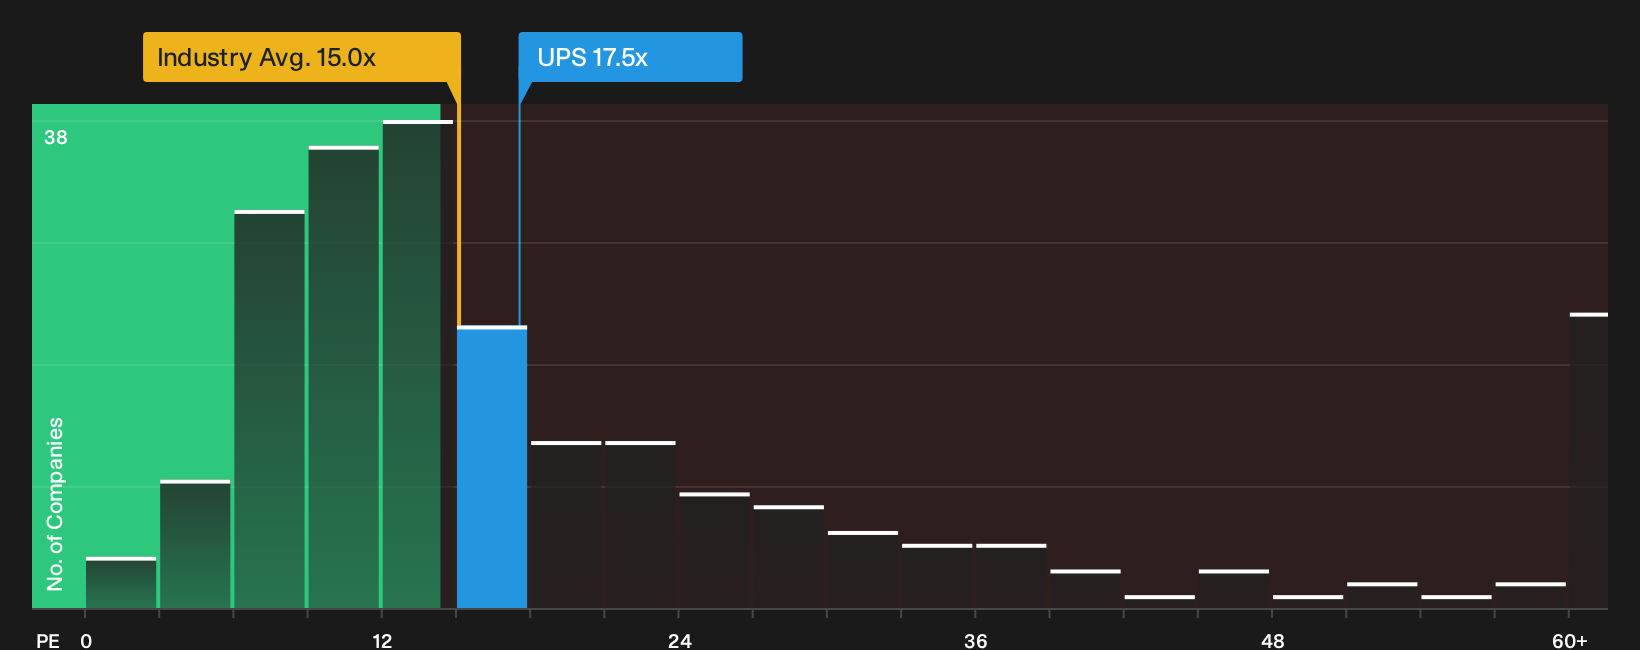
The first narrative presents United Parcel Service as undervalued based on future cash flows, yet the current P/E of 17.5x suggests a more cautious picture. It is above the global logistics average of 15x, below a peer group on 19.6x, and well under a fair ratio of 25.9x that the market could eventually move toward. That combination indicates both upside potential and the risk that expectations are already factoring in a recovery. Which side of that trade off do you think dominates at $93.96?
See what the numbers say about this price in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on United Parcel Service can be useful if they push you to interrogate the numbers yourself and move with intent rather than drift with headlines. To weigh the downside triggers against the upside case and decide where you stand, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond United Parcel Service?
If United Parcel Service has sharpened your thinking, you can use that focus to scan fresh opportunities where quality, value, and resilience line up before the crowd.
- Target potential upside with companies that combine sturdy balance sheets and attractive pricing by running a tailored search through 32 high quality undervalued stocks.
- Prioritize staying power and stability by filtering for businesses in the 30 resilient stocks with low risk scores that score well on resilience and risk controls.
- Look for potential future leaders hiding in plain sight by scanning the 16 high quality undiscovered gems before attention and valuations change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com