
Is CVS Health (CVS) Cheap As Renewables And Cancer Care Expansion Lift Optimism?
CVS Health (CVS) has put sustainability and access to care in focus, committing to source 50% of its electricity from renewables by 2040, while Aetna expands bundled cancer treatment authorizations for Medicaid members.
Recent headlines around CVS Health’s renewable energy push and Aetna’s broader cancer care bundles have landed alongside a 1-year total shareholder return of 21.37% and a 3-year total shareholder return of 43.14%. At the same time, the 90-day share price return has declined 14.58%, which hints that optimism around longer-term execution is holding up better than near-term share price momentum.
Scan for other healthcare stocks that pair long-term themes like renewables and access to care with potential breakout setups using our curated 30 resilient stocks with low risk scores.
After a 14.6% slide over 90 days and stronger returns over 1 and 3 years, CVS Health now sits in an awkward middle ground. The question for investors is whether patience on the sidelines is preferable to paying up for a long-term position today.
Most Popular Narrative: 28% Undervalued
On the most followed narrative for CVS Health, a fair value of $124 sits well above the last close at $89.13, which frames the current weakness as a valuation gap rather than a break in the story.
CVS Health is no longer the broken Aetna plus drugstore story the market used for most of 2024–25. Through the first half of 2026 the company has raised full-year guidance twice, Aetna’s medical benefit ratio has improved, cash flow is running well ahead of plan, and all three operating segments are growing.
See why 2 investors see CVS Health as 28% undervalued.
Result: Fair Value of $124 (UNDERVALUED)
Still, the CVS Health story could be knocked off course if medical costs spike again at Aetna, or if pharmacy benefit reforms compress Health Services profitability faster than expected.
Find out about the key risks to this CVS Health narrative.
Another View On CVS Health’s Valuation
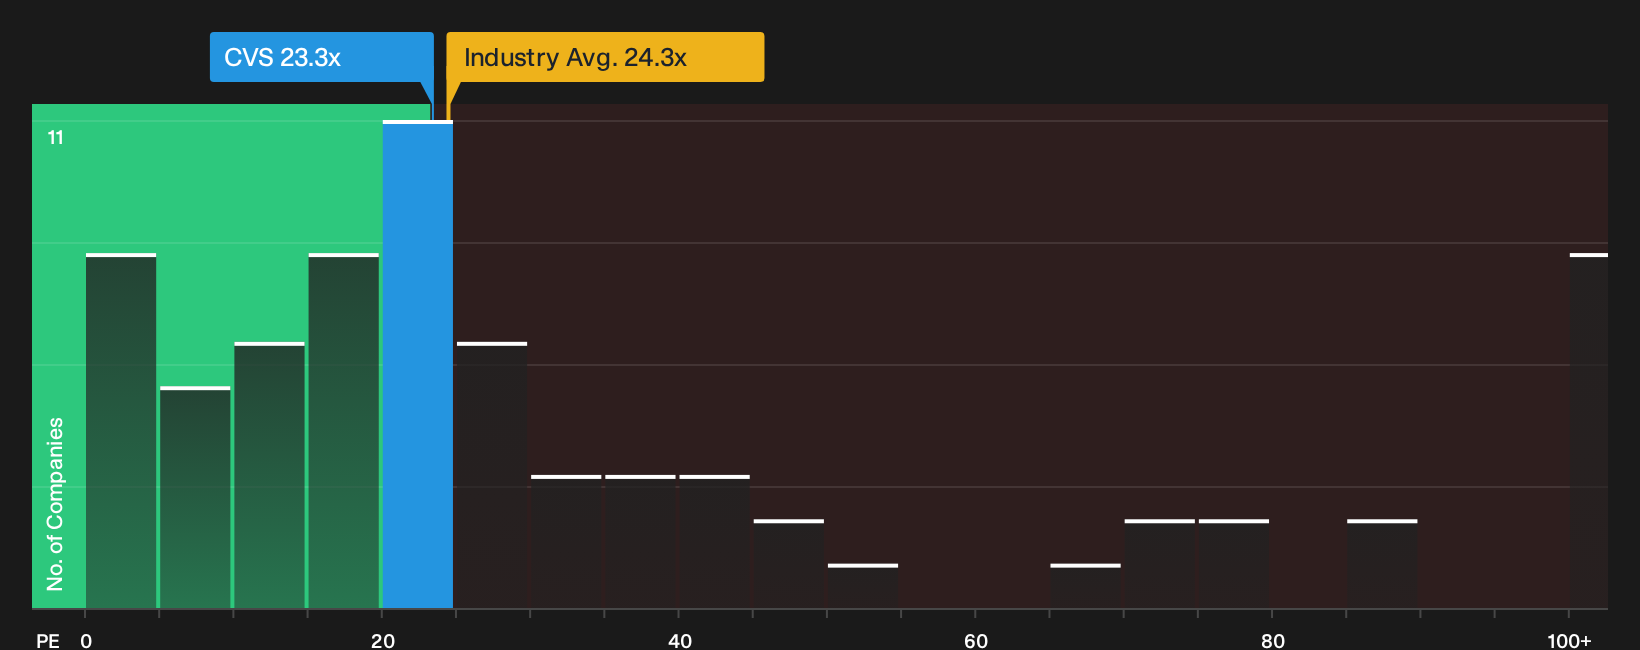
There is a second yardstick that pulls in a different direction. On a P/E of 23.3x, CVS Health screens as more expensive than its peer average at 18.7x, even though the fair ratio sits higher at 37x. That mix points to both valuation risk and room for sentiment to shift.
For readers who want to see how these earnings multiples compare across peers and against that fair ratio in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around CVS Health is clearly mixed, with bullish fair value estimates pulling against recent share price pressure, so act quickly and test the numbers yourself. To weigh both sides of the story, walk through the 4 key rewards and 2 important warning signs.
Looking For More Ideas Beyond CVS Health?
If you stop with CVS Health, you risk missing other setups that fit your style. Use the screeners below to pressure test fresh ideas fast.
- Hunt for quality at a discount by reviewing the 32 high quality undervalued stocks that pair solid fundamentals with appealing prices.
- Target reliable income streams by checking out the 8 dividend fortresses that focus on higher-yielding payers.
- Prioritize resilience by scanning the list of solid balance sheet and fundamentals (24 results) that spotlight financially robust businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com