
Ascendis Pharma (ASND) Could Be 28% Undervalued As It Reclaims TransCon Rights
Ascendis Pharma (NasdaqGS:ASND) has just taken full control of its TransCon technology in metabolic and cardiovascular diseases after ending its collaboration with Novo Nordisk. This shift directly refocuses attention on the stock.
Investors have been processing this shift alongside other recent moves, including a newly authorized share repurchase program of up to US$400 million. The reaction has been cool so far, with the 30-day share price return down about 9.9% and the year-to-date share price return lower by around 8.1%. This suggests momentum has faded in the short term even as the TransCon decision reshapes how some shareholders weigh future opportunity against execution risk.
Scan how Ascendis Pharma compares with a curated 16 high quality undiscovered gems that are also pursuing differentiated drug platforms and working to turn specialist pipelines into scalable franchises.
Ascendis Pharma now trades at a sizeable discount to analyst targets after reclaiming TransCon rights and launching a US$400 million buyback. Is that pricing in real execution risk, or leaning too hard into caution?
Most Popular Narrative: 28% Undervalued
On the latest Simply Wall St narrative, Ascendis Pharma screens as undervalued, with a fair value estimate of $313 against a last close of $225.60. That gap puts the focus on whether the TransCon platform and current product mix can justify the implied future cash flows.
Expansion of SKYTROFA into additional established growth hormone indications such as ISS, SHOX deficiency, Turner syndrome and SGA, alongside potential use in new segments like achondroplasia, can increase total addressable demand and contribute to higher revenue and more efficient use of existing commercial infrastructure.
See why 4 investors see Ascendis Pharma as 28% undervalued.
Result: Fair Value of $313 (UNDERVALUED)
Still, the narrative around Ascendis Pharma can break if YORVIPATH uptake slows materially or if TransCon CNP timelines and approvals fall short of expectations.
Find out about the key risks to this Ascendis Pharma narrative.
Another View On Ascendis Pharma's Valuation
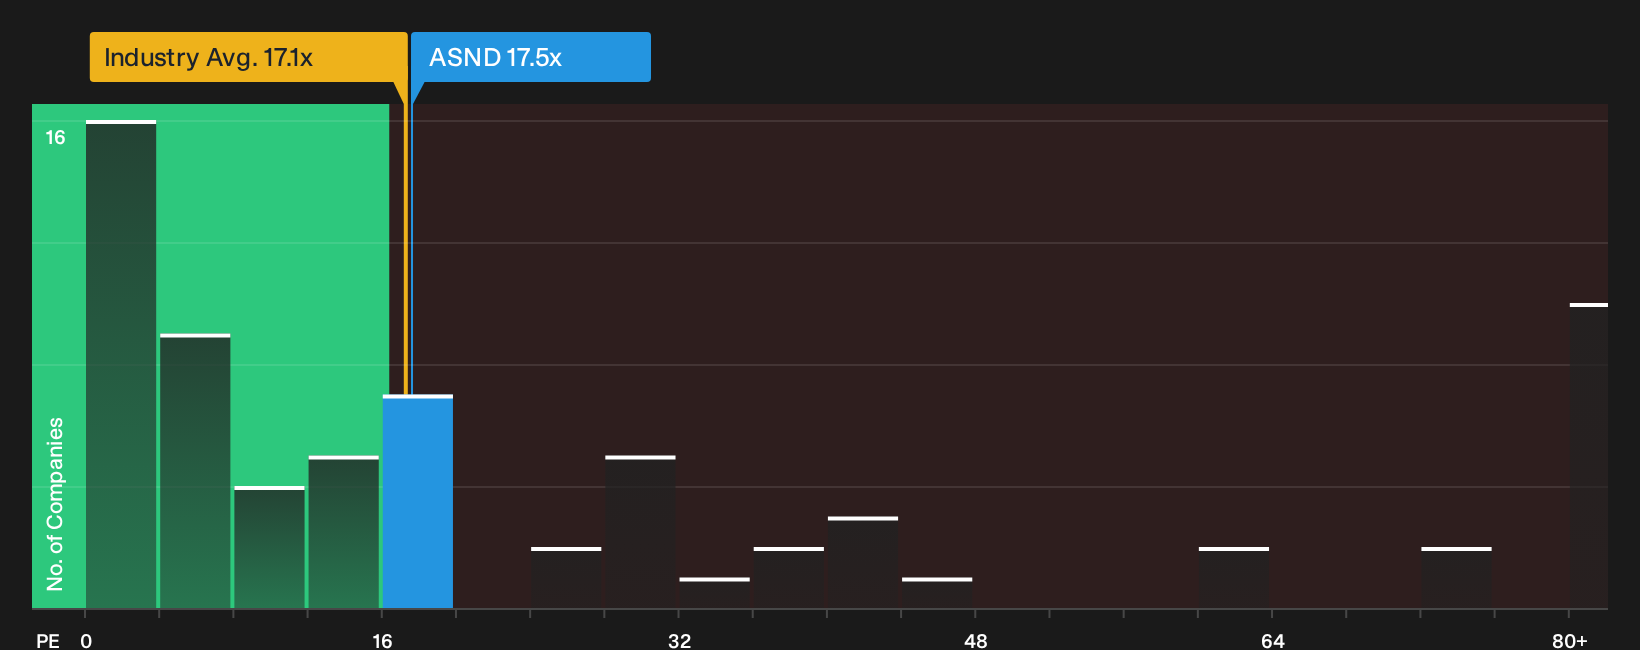
The earlier fair value narrative painted Ascendis Pharma as materially undervalued. On plain earnings multiples, the picture is less generous. The stock trades on a P/E of 17.5x, which is slightly more expensive than the wider US Biotechs industry at 17.3x, even though our fair value work flags it as trading 69.6% below intrinsic value. That mix of a modestly richer multiple and a very large discount to fair value raises a simple question for investors: Is the market fairly cautious on near term execution, or is it underestimating how much TransCon driven cash flow can eventually support this price?
For a closer look at how the numbers stack up against peers and what that means for valuation risk versus opportunity in practical terms, see what the numbers say in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment on Ascendis Pharma feels unresolved, do not sit on the fence. You can weigh the potential upside against the concerns by checking the 4 key rewards and 1 important warning sign.
Want more ideas beyond Ascendis Pharma?
You do not need to stop at Ascendis Pharma. Use the Simply Wall St screener to spot other potential opportunities before they move without you.
- Target dependable cash generators by scanning a list of solid balance sheet and fundamentals (24 results) to help you focus on sturdier balance sheets when markets feel uncertain.
- Hunt for potential mispricings by checking a 32 high quality undervalued stocks that filters for quality companies priced below their estimated worth.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that points you toward businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com