
How Investors May Respond To HNI (HNI) Strong Sales Outlook
- HNI has reported 29.9% annual revenue growth over the past two years, alongside 10.7% annual earnings per share compounding and a 40.2% sales growth outlook for the next 12 months.
- The combination of recent revenue expansion and faster earnings growth indicates that HNI has been scaling efficiently while securing a larger share of its markets.
- We will now examine how HNI's 29.9% annual revenue growth could reshape the investment narrative that analysts had built previously.
HNI Investment Narrative Recap
To own HNI, you need to be comfortable with a business that is leaning into office refresh demand and residential fireplace spending while still facing real questions about where long term office usage settles. The recent 29.9% annual revenue growth and 10.7% EPS compounding point to execution strength, but they do not erase uncertainty around hybrid work or housing related softness.
Right now, the near term swing factor is whether HNI can convert its 40.2% sales growth outlook into cleaner profitability after a year affected by a large one off loss and thinner margins. The biggest risk is that pricing driven growth in Residential Building Products or tariff exposed hospitality volumes soften, which could pressure both cash generation and already tight dividend cover.
There have been no fresh company announcements tied directly to this revenue acceleration. As a result, the focus stays on existing execution levers such as Mexico optimization and KII related efficiencies referenced in prior outlooks. Those projects matter because analysts expect earnings to grow strongly, and any stumble on cost savings could leave that thesis exposed.
For you as a shareholder or prospective investor, the key question is whether HNI can pull through the drag from last year’s one off loss and low 0.1% net margin while still funding capex, servicing debt that is not well covered by operating cash flow, and paying a dividend that current earnings do not fully support. The recent growth numbers make the potential upside more visible, but the funding mix and dilution over the past year keep the risk side of the ledger very real.
HNI's current analyst narrative points to forecast revenues of US$7.7b and earnings of US$595.5m by 2029. This outlook is based on an assumed 29.1% yearly revenue growth rate and an increase in earnings of roughly US$594.5m from US$1.0m today.
Discover how HNI's fair value suggests a 46% potential upside to its current price before the market closes that gap.
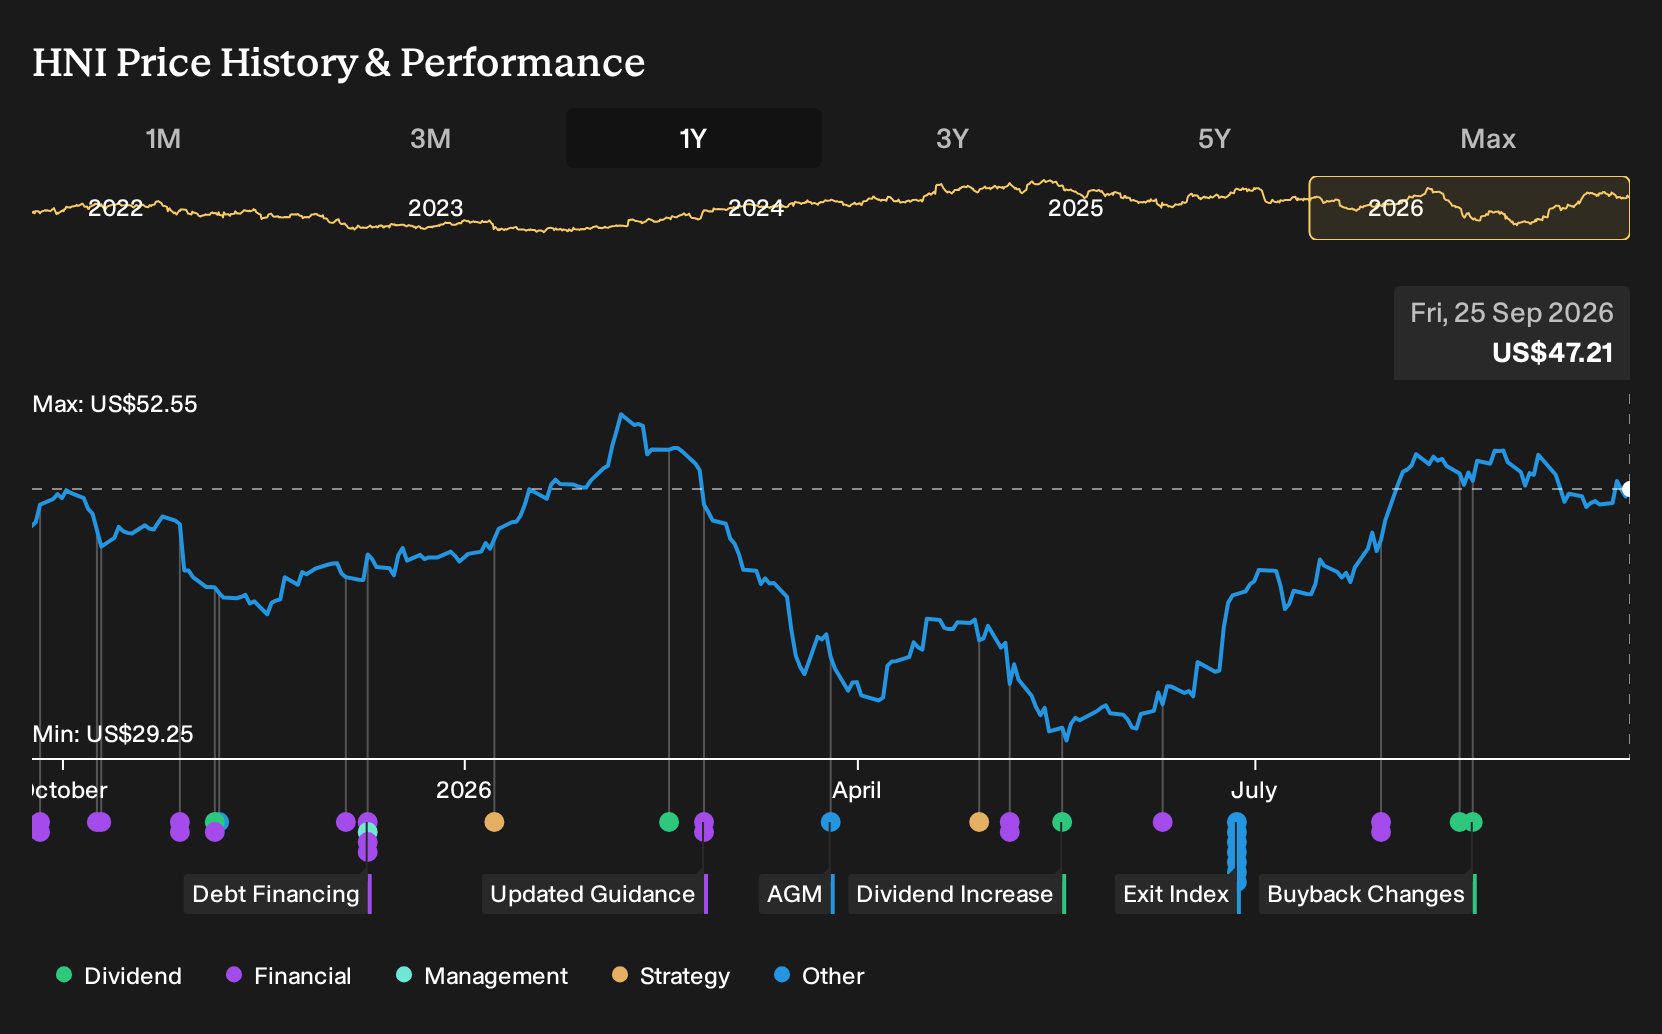
Exploring Other Perspectives
HNI attracts three separate fair value views from the Simply Wall St Community, with estimates starting at US$69 and stretching to roughly US$491.76. That spread reflects very different readings of hybrid work, housing demand, and tariff risk. Use those contrasting opinions to stress test your own thesis before committing fresh capital.
Explore 2 other HNI fair value estimates, including one that suggests potential upside of up to 942% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your HNI research is our analysis highlighting 4 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for HNI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HNI's overall financial health at a glance.
Looking For More Ideas Beyond HNI?
Once you have formed a view on HNI, it can help to line it up against a broader watchlist so you are not relying on a single opportunity. The Simply Wall St Screener lets you filter for different traits, from resilience and balance sheet strength to higher growth potential, and compare those profiles side by side.
- If you want potential upside with a quality tilt, scan a curated 16 high quality undiscovered gems that already clear a fundamentals hurdle before they hit most radars.
- For anyone prioritising staying power over excitement, focus on a 30 resilient stocks with low risk scores that filters for businesses with more resilient risk scores.
- Income focused investors who still care about underlying strength can work through a 8 dividend fortresses designed to highlight higher yield payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com