
Apple Patent Verdict Puts These IP Rich Tech Stocks In Focus
A US jury just ordered Apple to pay US$5.7b over haptic patents used in its iPhone and Apple Watch Taptic Engine, and that verdict shines a floodlight on who really controls crucial technology. When headlines focus on Apple, quieter intellectual property rich stocks can see their risk and royalty debate sharpen. This article walks through 3 such companies exposed to the same legal currents and how that might matter for your portfolio decisions.
The three intellectual property rich stocks below are just a starting sample, while the full screen surfaced 28 more US listed technology and electronics companies with equally focused patent and licensing narratives that are not covered here.
To go deeper, head straight into the Intellectual Property-Rich Technology Stocks screener to identify, analyze, and filter the highest conviction intellectual property rich technology ideas for your watchlist.
QuickLogic (QUIK)
QuickLogic leans into the Intellectual Property Rich Technology theme through its embedded FPGA designs and licensing model, which put its chip architecture at the center of customers’ products rather than the physical factories that make them.
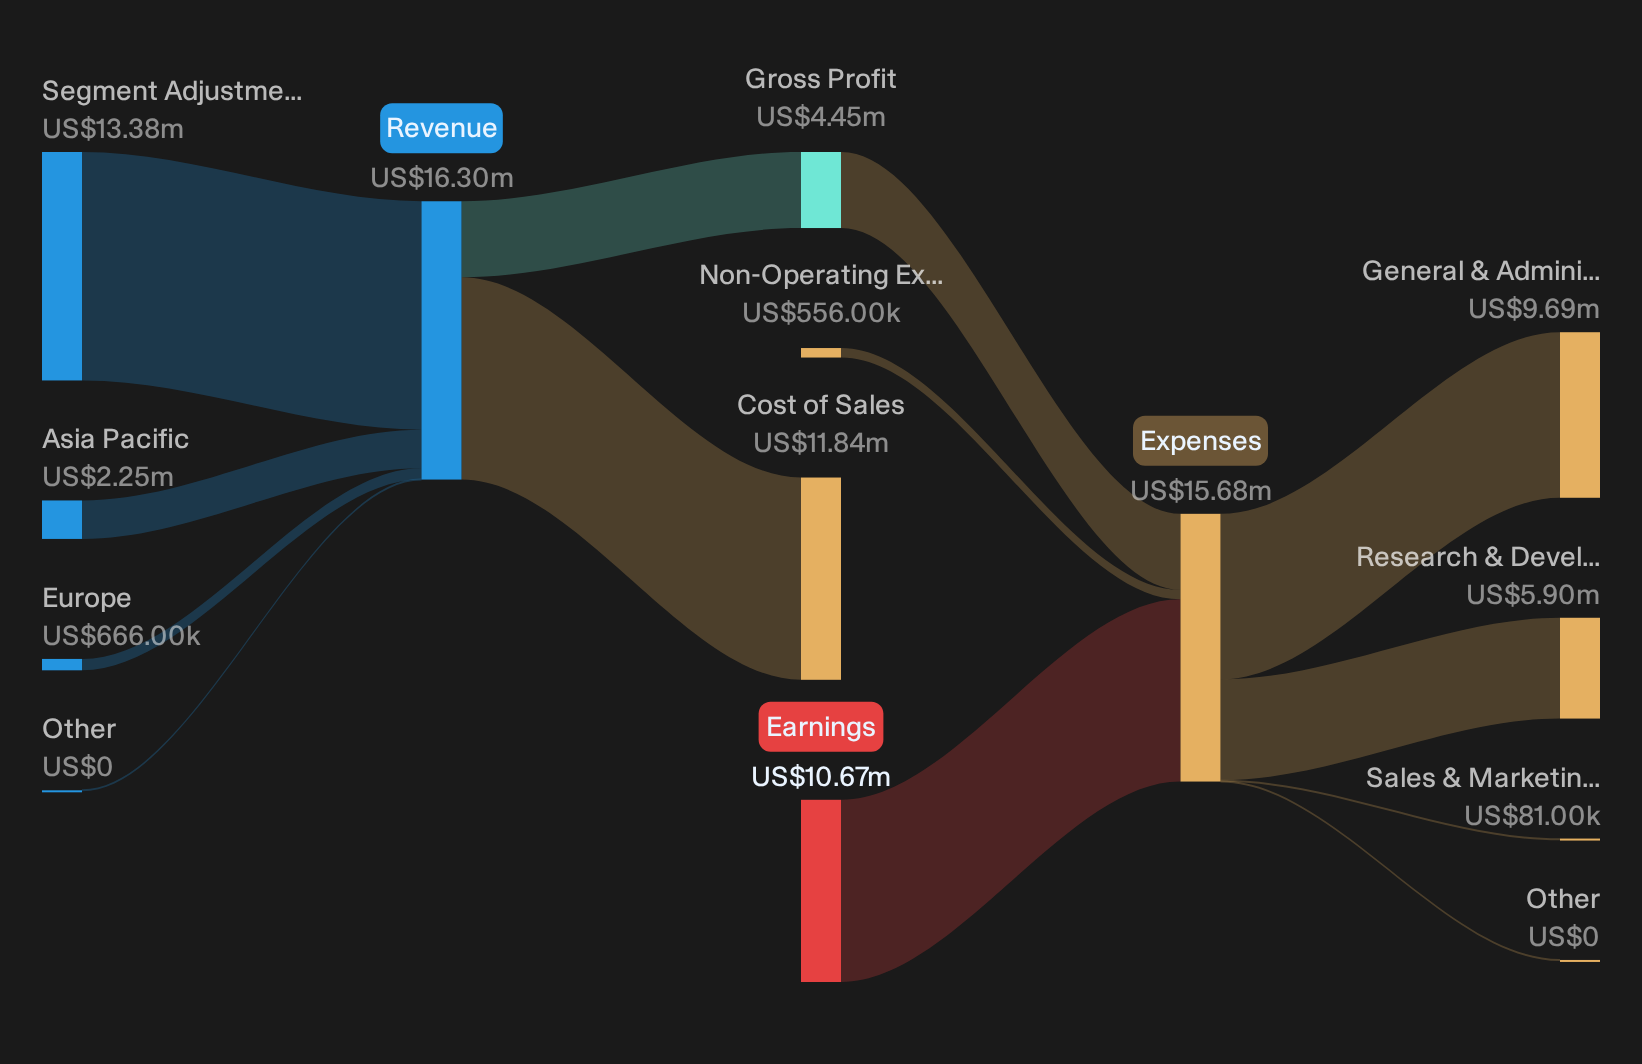
QuickLogic is a US based fabless semiconductor specialist whose business revolves around eFPGA IP, discrete FPGA devices, and related software tools, with all of its US$16 million revenue coming from semiconductors and a market value of about US$201 million.
"QuickLogic's accelerated investment in a US-fabricated, high-density, radiation-hardened (rad-hard) FPGA test chip positions the company to capitalize on the growing demand for domestically produced, mission-critical programmable logic in defense and aerospace, enabling entry into large, multi-hundred-million-dollar addressable markets."
The real test for QuickLogic will hinge on how one quiet shift in its mix of IP royalties versus hardware sales influences future margin potential.
If that mix shift is what you care about, read the full narrative for QuickLogic to see how QuickLogic’s royalty potential and risk profile really line up.
CEVA (CEVA)
CEVA is the pure-play intellectual property story in this screen, selling chip designs and software that other manufacturers build into their own silicon, which makes it a natural focal point when investors are thinking about who gets paid when patents move to the foreground.
CEVA licenses processor, connectivity, audio, sensing, and AI silicon IP to chipmakers and device brands, generating about US$116 million from IP licensing and carrying a roughly US$1 billion market value.
"Accelerating customer adoption of CEVA's Edge AI NPUs (as evidenced by multiple new, high-impact licensing deals and the integration of NeuPro architectures across diverse markets like audio, video, and infrastructure) lays the foundation for materially higher royalty revenue per device as these AI-enabled products ramp into mass production over the next 18 to 24 months."
The bigger question is how much of that potential actually flows through to margins if a single key assumption about customer uptake shifts.
That margin swing is exactly what the full narrative for CEVA unpacks, showing where CEVA’s royalty engine could accelerate, stall, or quietly decouple from headline licensing wins.

PDF Solutions (PDFS)
PDF Solutions leans straight into the Intellectual Property Rich Technology theme, since almost all of its US$241 million in Software and Programming revenue comes from proprietary chip design software, data platforms, and hardware tools, backing a roughly US$2.1 billion stock built around owned technology rather than commodity production.
PDF Solutions matters in this screen because it sells the data and IP layer that keeps chip factories running smarter, and that puts its software and connectivity tools in the conversation whenever IP ownership, data rights, and manufacturing resilience move to the foreground.
"Accelerated enterprise adoption of PDF's secure, cloud-based supply chain orchestration and analytics solutions, including secureWISE, Sapience Manufacturing Hub, and Exensio, positions the company to address the industry's need for integrated data traceability and resilient manufacturing networks; this supports recurring revenue growth and may contribute to higher earnings stability."
The key issue for PDF Solutions is how much of that software pull-through actually shows up in margins if a potential shift in customer data usage were to play out differently.
That comes down to how resilient those data economics really are. This is exactly what the full narrative for PDF Solutions unpacks, including where recurring revenue could quietly accelerate.

Curious About What Else You Might Be Missing?
Fresh themes keep breaking out while attention drifts. Use that momentum before these under the radar for now ideas get fully caught by the crowd and act now.
- Track income potential by scanning dividend payers in the 8 dividend fortresses before yields change or balance sheets shift and some of the easier opportunities fade.
- Look for potential mispricing by reviewing the 16 high quality undiscovered gems that combine solid fundamentals with relatively low attention while that information gap may still be relevant.
- Consider infrastructure-related trends by checking the 40 power grid technology and infrastructure stocks where grid technology players may experience changing momentum before headlines fully reflect it.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com