
Lam Research (LRCX) Could Be 34% Undervalued On Raised 2026 Outlook
Lam Research (LRCX) has grabbed attention after management lifted its 2026 wafer fab equipment market outlook to the low US$150b range and forecast packaging revenue growth of more than 70%, citing AI and memory demand.
That outlook reset lands on a stock that has already swung sharply this year, with Lam Research posting a 70.33% year to date share price return and an even stronger 146.76% one year total shareholder return, despite a 16.85% decline over the past 90 days that reflects shifting sentiment around AI spending cycles and interest rate moves.
Scan beyond Lam Research and size up other AI infrastructure suppliers using the curated 85 AI infrastructure stocks that are also tied to wafer equipment and advanced packaging demand.
The share price reset leaves Lam Research looking either refreshed for another leg higher or already past the sweet spot. The valuation work now has to determine which side of that argument you agree with.
Most Popular Narrative: 26% Undervalued
On the numbers that matter to valuation, the leading Lam Research narrative places fair value at $423.85 against a last close of $315.21. This sets up a clear gap for investors to interpret rather than a marginal pricing dispute.
Lam has greater operating leverage to memory and layer-count growth than any of them, and it owns the specific process steps, high-aspect-ratio etch, through-silicon via formation, copper electrofill, that HBM stacking and 3D NAND scaling physically require. When the constraint is vertical scaling, Lam is the constraint.
See why 28 investors see Lam Research as 26% undervalued.
According to isidrohg, that story leans on Lam Research earning a larger share of a growing memory and packaging budget rather than on a simple re-rating of the stock. The fair value is built off a $23.23b revenue base, a 31.3% net margin and a 54.4x future P/E input discounted at 11.25%.
The same narrative treats the current 54.3x P/E as something the market might not maintain if margins normalise. In this view, the upside case depends more on earnings and cash flow delivery than on investors paying a higher multiple for each dollar of profit.
Result: Fair Value of $423.85 (UNDERVALUED)
Still, Lam Research faces real tripwires, including any sharp pullback in memory capex or tighter China export rules that choke off wafer equipment demand.
Find out about the key risks to this Lam Research narrative.
Another View: What Lam Research’s P/E Is Saying
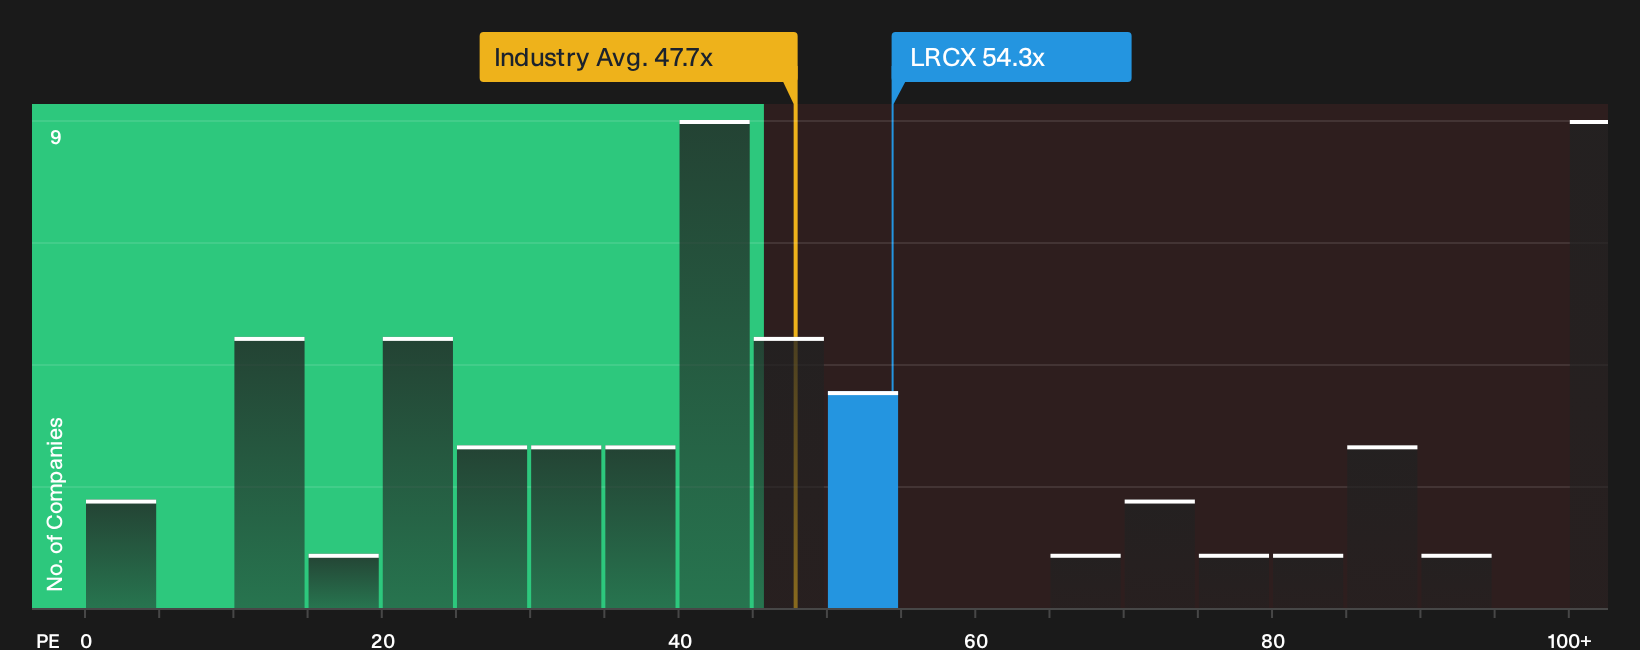
The narrative pins Lam Research at a fair value of $423.85, yet the market is already paying a rich P/E of 54.3x. That is higher than the US Semiconductor industry at 47.7x, above peer averages of 47.7x, and well above a fair ratio of 44.8x that the market could move toward. If sentiment cools or forecasts miss, how much room is there before valuation risk bites?
To see how the current price stacks up against those earnings multiples in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Lam Research is split, with investors weighing rich multiples against real growth hopes, so move quickly and study the full picture for yourself. To see the balance of upside and downside risk in one place, review the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Lam Research?
Do not stop your research with Lam Research when you can scan other opportunities side by side using focused screeners that keep the key numbers in front of you.
- Target consistency by reviewing a list of solid balance sheet and fundamentals (24 results) that keeps financial strength in focus before you commit fresh capital.
- Hunt for value gaps through a 32 high quality undervalued stocks that lines up quality fundamentals against current market pricing.
- Prioritise resilience and sleep-better-at-night ideas with a 30 resilient stocks with low risk scores that filters for steadier return profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com