
3 UK Homebuilder Stocks Most Exposed To Higher Gilt Yields
UK domestically focused consumer and services stocks sit right in the crossfire of today’s big macro stories. Oil near $100, 10-year gilts around 5.4% and a Chancellor weighing how hard to lean on tax and spending all feed directly into household bills, borrowing costs and confidence. This article picks out 3 UK stocks exposed to that mix, showing where the Iran war, the “Burnham bounce” and bond markets could matter most for your portfolio.
The three stocks below are only a sample of what this theme can touch, and the full screen surfaced 19 more domestically tilted businesses with equally compelling stories that are not covered here. To go deeper into this idea, identify your own shortlist and analyze which UK-focused plays line up with your thesis, head straight into the UK domestically focused consumer and services stocks screener.
MJ Gleeson (LSE:GLE)
Overview: MJ Gleeson builds affordable homes across the North and Midlands and promotes and sells residential land in southern England, tying it closely to UK housing demand.
Operations: The group generates about £400 million from Gleeson Homes and £10 million from Gleeson Land, with all £410 million earned in the UK.
Market Cap: £142 million
MJ Gleeson is tightly wired into the UK housing-related consumer story, so any shift in domestic appetite for new-build homes quickly feeds into its order book and land pipeline.
"Gleeson Homes is continuing to increase its forward order book and has plans to accelerate site openings. This is likely to positively impact future revenue and earnings as it supports growth in housing deliveries."
The real test for MJ Gleeson will come from how one stubborn pressure on its build costs and pricing power ultimately settles.
How that pressure ultimately plays out is exactly what the full narrative for MJ Gleeson unpacks, including where MJ Gleeson could accelerate if conditions ease or stay tight.

Crest Nicholson Holdings (LSE:CRST)
Overview: Crest Nicholson Holdings builds and sells residential homes and some commercial properties across the UK, tying fortunes closely to domestic housing activity.
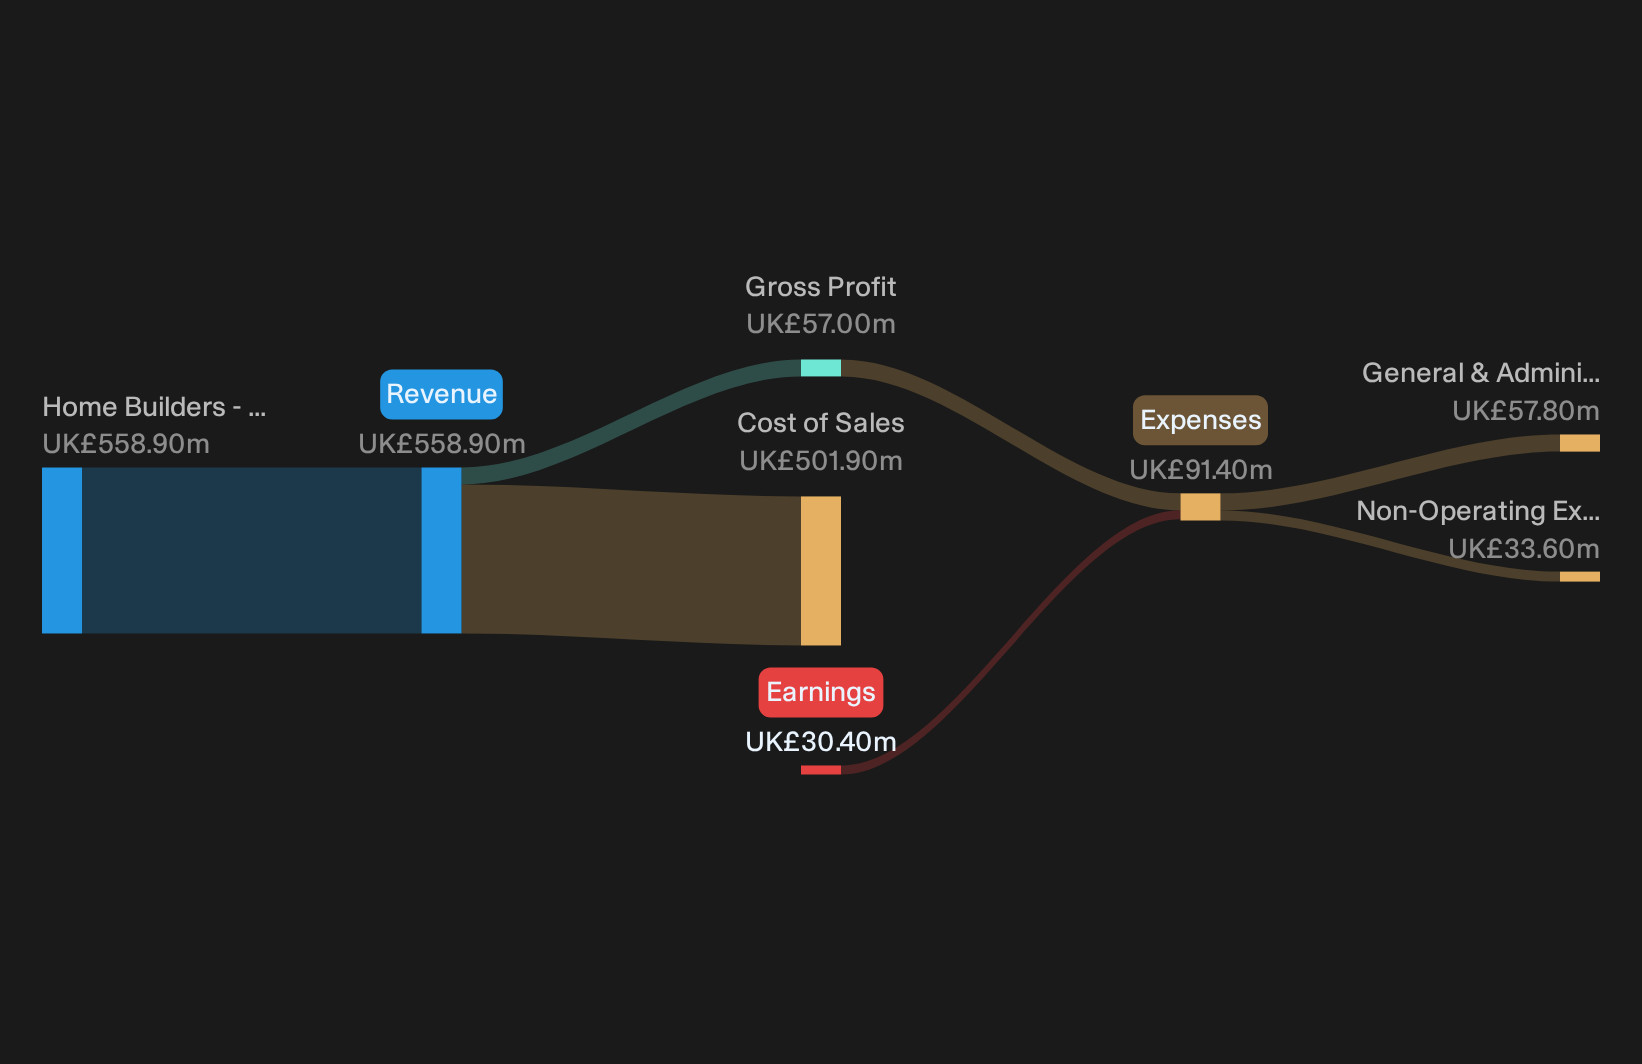
Operations: The group generates about £559 million from UK residential and commercial home building, with all reported revenue coming from the United Kingdom.
Market Cap: £151 million
Crest Nicholson Holdings gives you direct exposure to the UK housing cycle, where mortgage availability and local confidence can quickly shift the outlook.
"Although the focus on the mid premium segment aligns product, branding, and customer experience, the shift requires ongoing spending on marketing, sales tools, and upgraded specifications, which could keep pressure on net margins if pricing does not fully cover the higher cost to serve."
What happens to Crest Nicholson Holdings’ profitability depends heavily on a single pressure point that could quietly reshape both pricing power and future demand.
That pressure point is exactly where the full narrative for Crest Nicholson Holdings shows whether Crest Nicholson Holdings is quietly setting up for accelerating demand or just masking deeper risk.
Vistry Group (LSE:VTY)
Overview: Vistry Group provides UK housing solutions, focusing on single family homes that directly tap into domestic housing demand and local consumer conditions.
Operations: Vistry Group generates about £3.4b from UK residential and commercial home building, with all reported revenue coming from the United Kingdom.
Market Cap: £822 million
Vistry Group provides exposure to the UK housing story, where first time buyers, policy support and confidence around home ownership all feed directly into demand.
"Vistry's growing focus on the affordable and partnership housing sector greatly increases its dependence on government funding and policies; any policy reversal, budget cuts, or tightening of affordable housing grants would place downward pressure on both volumes and revenues."
Future outcomes for Vistry’s margins and operations will depend on how one unresolved policy pressure is ultimately handled.
That policy overhang is exactly where the full narrative for Vistry Group shows how Vistry Group could turn funding risk into accelerating demand and an overlooked long term growth story.

Seeking Fresh Alternatives Before They Fly
Fresh themes can gain momentum quickly while older ideas drop out of focus. Move before the crowd, look for potential breakouts while it matters, and try to position early.
- Scan curated companies in the 1 dividend fortresses to spot potential income workhorses before yield hunters increase competition and narrow your opportunity set.
- Explore the hand picked 5 high quality undiscovered gems to look for potential compounders that are still under the radar for now, before wider attention affects entry points.
- Focus on resilience first by reviewing the 4 resilient stocks with low risk scores so you are not left searching for stability after markets have already repriced it.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com