
Condestable Drilling Plans Altering The Investment Case For Rio2 Stock?
- Rio2 released a company wide exploration update covering Condestable in Peru, Fenix Gold in Chile and Kalzas in Canada, including new multi phase drilling at Condestable and a weather driven suspension of the 2026 drilling campaign at Fenix until early 2027.
- The detailed geological mapping and 57,740 hectare GeoMagDrone survey at Condestable have sharpened Rio2’s view of where to allocate drilling capital, with six priority targets now defined for follow up work.
- We will look at how Rio2’s investment narrative is affected by the Condestable drilling rollout and refined district scale targeting.
Scan 36 elite gold producer stocks, which echoes Rio2’s multi country exploration push, and see which producers are also lining up fresh drilling campaigns and district wide work.
Rio2 Investment Narrative Recap
To own Rio2, you need to believe it can turn Fenix Gold into a reliable cash generator while using Condestable and Kalzas to extend the project pipeline. The latest update keeps that broad picture intact. The near term swing factor still looks like Fenix reaching consistent throughput and costs, with Condestable exploration more about shaping medium term options than immediate results.
The biggest operational risk remains weather and leach performance at Fenix, especially after recent interruptions linked to harsh conditions. Suspending the 2026 Fenix drilling until early 2027 pushes out data on deeper mineralization, which slows one potential de risking lever rather than changing the core near term challenge.
The most relevant disclosure here is the two phase drilling program at Condestable, backed by fresh geological mapping and the 57,740 hectare GeoMagDrone survey. For investors, this is about whether Condestable can grow into a larger, longer life copper hub that supports the wider Rio2 portfolio and potentially feeds into future expansion plans.
Six priority targets and a tightly designed drill grid create clearer upcoming catalysts. Phase 1 drilling from existing platforms can test resource conversion and new zones within the current footprint. Phase 2 depends on fresh permits and access. Execution on both phases, and how results tie into the existing plant and any ore sorting work, will heavily influence how much weight you give Condestable in the Rio2 story.
Rio2's narrative projects $691.3 million revenue and $250.6 million earnings by 2029. This requires 59.3% yearly revenue growth and an earnings increase of about $192.4 million from $58.2 million today.
Uncover why Rio2's fair value indicates a 57% potential upside to its current price that may not last much longer.
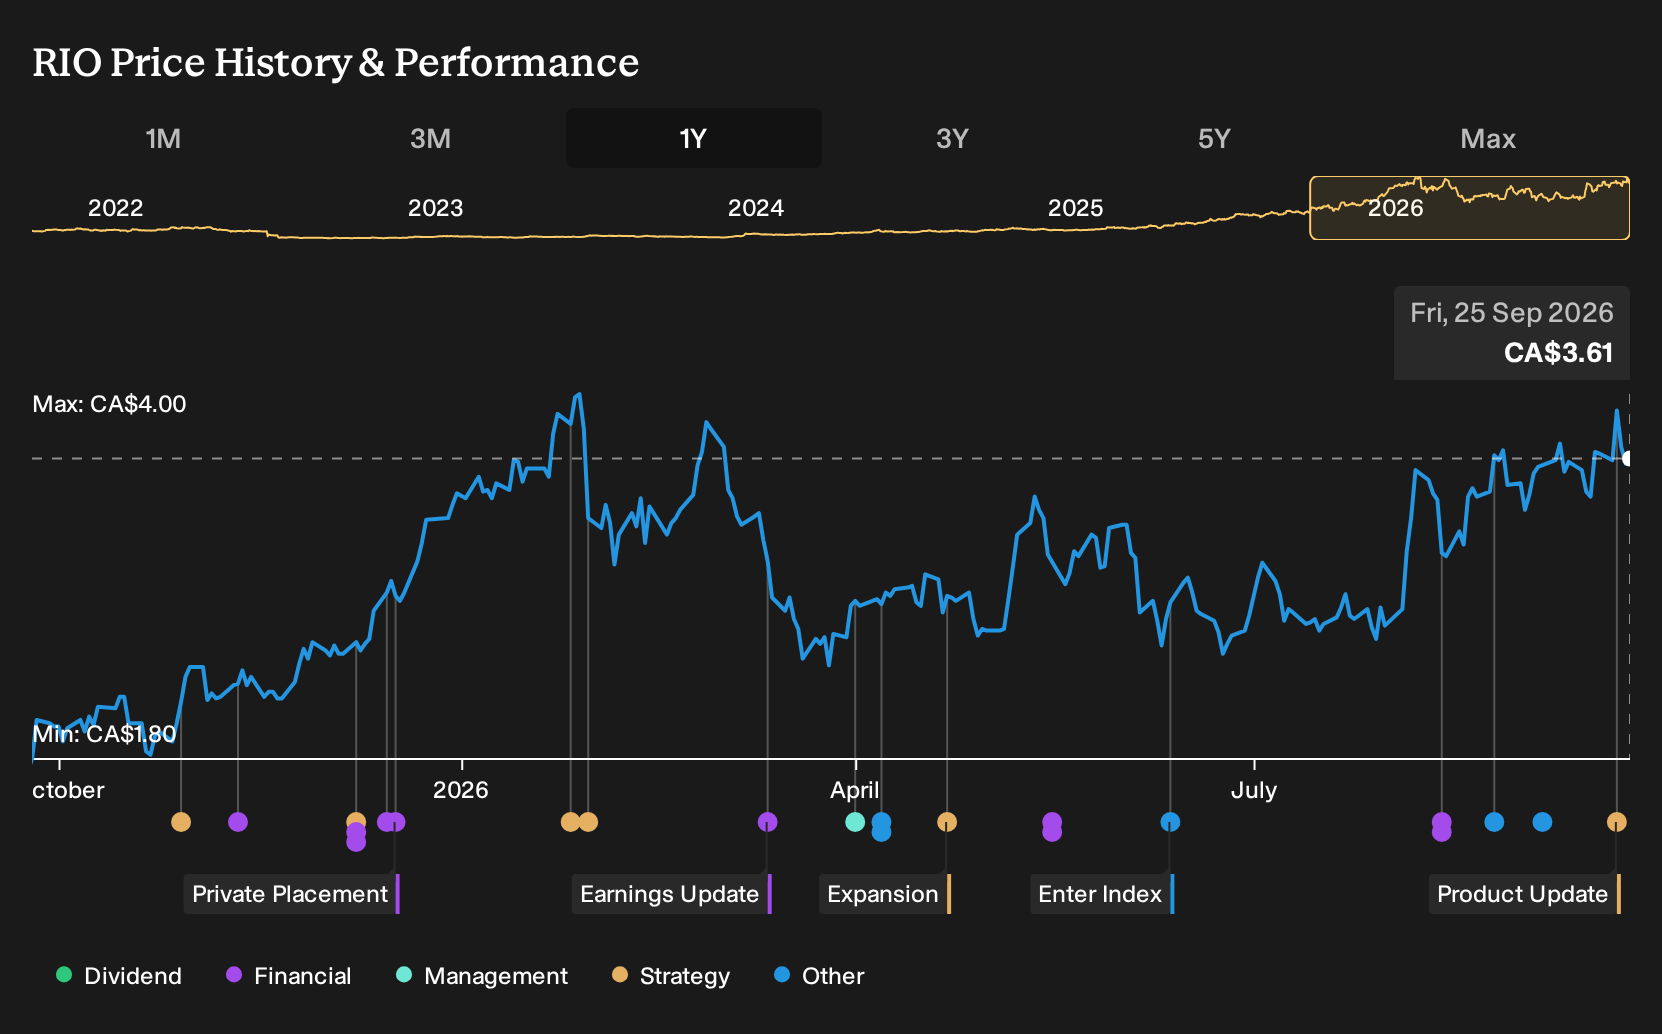
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community span from US$5.65 to US$21 per Rio2 share, which is a wide bracket for one ticker. Those views sit beside fresh information risk, including Fenix weather interruptions and the large, staged Condestable program. Use that spread as a prompt to compare several competing Rio2 viewpoints yourself.
Explore 5 other Rio2 fair value estimates, including one that suggests it could be worth just CA$5.65!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Rio2 research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rio2. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rio2's overall financial health at a glance.
Looking for more Rio2 style investment ideas?
If the Rio2 story has you thinking about how to balance potential upside with different types of risk, it can help to scan a wider field of companies that match the kind of profile you want in your portfolio.
- If you want higher risk and the possibility of outsized moves, start with a focused group of smaller companies through 20 elite penny stocks with strong financials.
- For investors who care most about quality and valuation discipline, you can narrow your search to 5 high quality undervalued stocks that combine earnings power with solid fundamentals.
- If resilience and balance sheet strength are your priority, filter for businesses with conservative financial footing using the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com