
Vistra (VST), What Is Behind The Renewed Attention?
Vistra (VST) is back in focus after new commentary compared it directly with Constellation Energy as a public market way to gain exposure to rising AI driven electricity demand and data center power needs.
Vistra’s recent pullback tells the story. The share price has slipped over the past quarter and year to date, yet the 3 year total shareholder return is more than 3x and the 5 year total shareholder return is very large. This suggests long term holders have already seen substantial value creation even as current momentum has cooled on concerns about softer Texas power prices and how quickly AI linked demand will feed through to cash flows.
Scan beyond Vistra and see how other potential AI power beneficiaries stack up in a curated set of 85 AI infrastructure stocks.
Vistra’s pullback has reset expectations after a huge three year run. Does that recent slide finally tilt the balance of risk and potential reward back toward new money, when you compare it with the current valuation?
Most Popular Narrative: 53% Undervalued
Against Vistra’s last close of $138.46, the most followed valuation story on Simply Wall St pegs fair value at $291.87, which implies a sizeable gap between the current quote and that narrative’s view of the business.
The certified case's starting point is Vistra's own reaffirmed 2026 Adjusted Free Cash Flow guidance. This figure, worth repeating, excludes any contribution from Cogentrix or the Meta agreements entirely. The growth assumption above the guided baseline is not optimism for its own sake. It is credit for three real, disclosed, signed catalysts: Cogentrix, the Meta PPAs, and now Helix. None of these are hypothetical, and none of them are fully reflected in the numbers being guided today.
See why 69 investors see Vistra as 53% undervalued.
Result: Fair Value of $291.87 (UNDERVALUED)
Still, Vistra’s heavy net debt load and exposure to commodity price swings could quickly challenge that undervalued narrative if cash generation or hedge outcomes disappoint.
Find out about the key risks to this Vistra narrative.
Another View: How Vistra Looks On Earnings Multiples
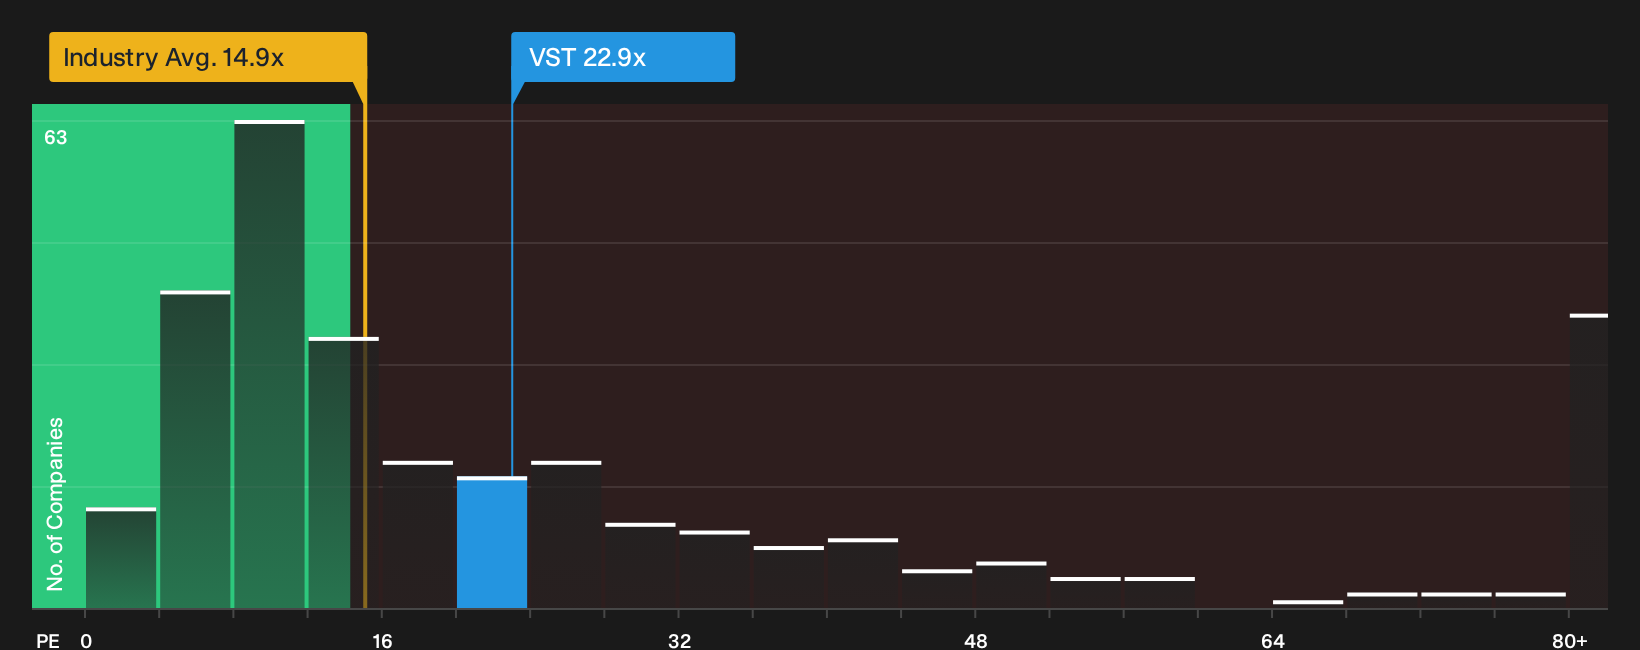
That 53% undervalued fair value story sits beside a more cautious message from the market. Vistra trades on a P/E of 22.9x, compared with 14.9x for the global renewable energy group and 17x for peers, even though the fair ratio points closer to 29.7x.
Paying a richer P/E than the sector and peer average means less room for disappointment if expectations on cash generation, AI linked demand or Texas pricing wobble again, even if the fair ratio hints the market could still move higher over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Vistra's risk and reward profile so far. Act while sentiment is divided and weigh both sides through 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Vistra?
If Vistra has sharpened your focus on opportunity and risk, do not stop here. Use the Simply Wall Street Screener to surface fresh ideas tailored to your goals.
- Target resilient companies with healthy balance sheets and robust fundamentals through a curated list of solid balance sheet and fundamentals (24 results) that cuts through the noise.
- Hunt for quality at a reasonable price by scanning a focused 32 high quality undervalued stocks that filters for strength in both cash flows and financial position.
- Spot potential under the radar by reviewing a hand picked 16 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com