
Emami And 2 Other Indian Dividend Stocks To Own
Bond yields at two decade highs are resetting borrowing costs across the world, which puts reliable income front and center for many investors. For Indian dividend stocks paying more than a 3% yield, that creates a clear draw. Investors receive potential cash flow today, instead of relying only on future price moves. This article walks through three dividend ideas from this high yield screen and why they merit a closer look now.
The three dividend stocks highlighted below are only a small sample, as this same screen surfaced another 44 income ideas with similarly compelling stories that are not covered here. If you want to move faster, head straight into the Dividend Powerhouses (3%+ Yield) screener to identify, filter, and analyze the dividend payers that best fit your own criteria.
Emami (BSE:531162)
Emami is a fast moving consumer goods player built around everyday personal and healthcare brands that throw off steady cash, which is exactly the profile this dividend screen looks for in a 3%+ payer.
Emami manufactures and sells a wide range of personal and healthcare products, with the entire ₹39.1b in reported revenue coming from this core segment, and carries a market value of about ₹169.9b.
"The ongoing migration of Indian consumers from unbranded to branded and premium wellness/personal care products, combined with Emami's deep heritage in Ayurveda and natural offerings, positions the company to disproportionately benefit from growing health/wellness awareness and premiumization, which in turn supports sustained gross margin expansion and superior average realization per unit."
What really matters for dividend investors is how one less visible pressure on Emami’s cash generation ultimately shapes that margin story.
That hidden cash flow drag is exactly what the full narrative for Emami unpacks, including how Emami’s payout could respond if those pressures ease or accelerate.

Bhansali Engineering Polymers (BSE:500052)
Bhansali Engineering Polymers manufactures thermoplastic resins such as ABS, SAN, and ASA that power everyday products from cars to appliances. All ₹14,402 million in revenue comes from resin manufacturing, and the company carries a market value of about ₹31.4b.
For dividend hunters, Bhansali Engineering Polymers offers a 3.17% yield backed by resin cash flows and high earnings quality, alongside recent Q1 FY2027 revenue of ₹4,819.06 million and net income of ₹655.98 million. The main question is how that payout holds up if one pressure on its resin margins shifts.
If you want to see how that margin pressure and payout risk really interact, head into the 2 key rewards and 1 important major warning sign before resin pricing resets the story.

Gujarat Energy (NSEI:GUJENERGY)
Gujarat Energy runs a large piped and compressed natural gas distribution network that behaves much like a utility. This is the kind of recurring cash engine dividend investors tend to look for in a 3%+ yield screen.
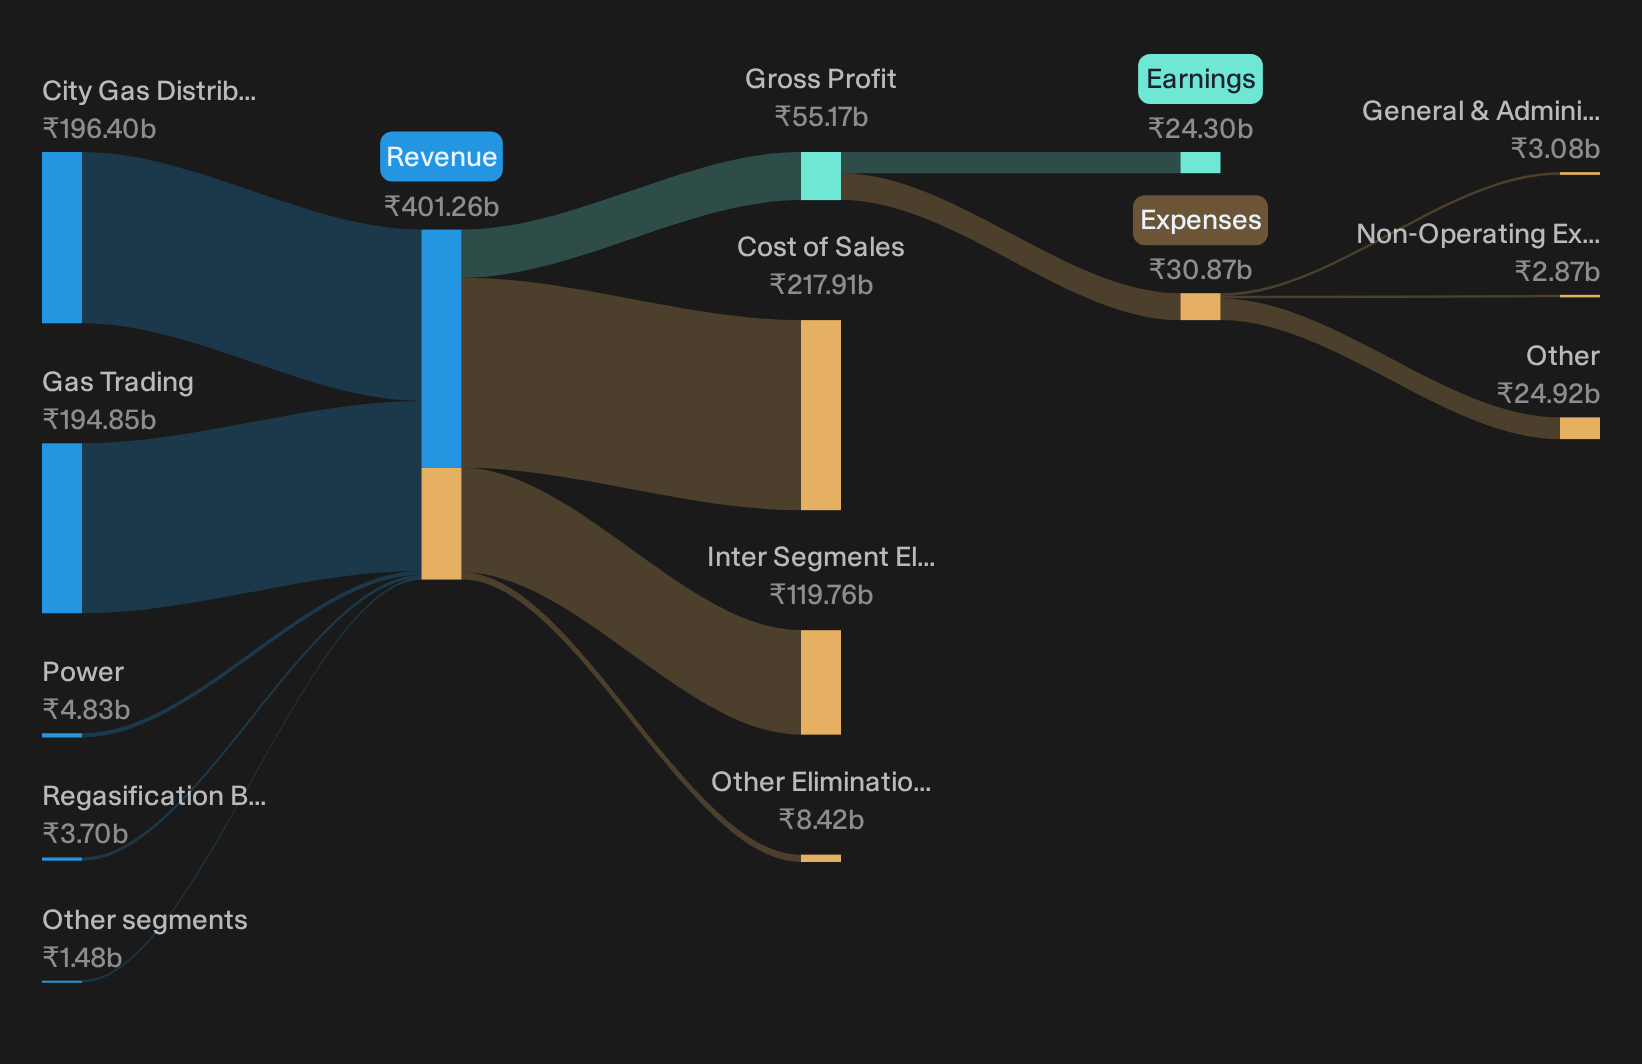
Gujarat Energy generates about ₹196.4b from city gas distribution and ₹194.9b from gas trading, alongside smaller power, regasification and E&P lines, all within India, and carries a market value of roughly ₹221.4b.
"Sustained policy and consumer momentum towards cleaner fuel usage and rapid urban expansion are supporting strong double-digit growth in CNG volumes, with Q1 FY '26 seeing 12% YoY CNG volume increase and the company expecting to outpace even last year's 11% growth due to robust CNG vehicle additions and strategic infrastructure investments."
Consider what happens if one less visible pressure on Gujarat Energy’s funding costs and capital spending rhythm starts to reshape those steady cash flows.
That funding shift is exactly where the full narrative for Gujarat Energy picks up. It reveals how Gujarat Energy’s capital rhythm could quietly accelerate or cap those CNG cash flows.
Seeking Alternatives Before Momentum Flies
Fresh ideas often move first, and late capital frequently ends up chasing fading momentum. Review these under the radar lists before the broader market catches up and pricing power weakens, then consider your options.
- Target resilient balance sheets and stable cash engines by running the list of solid balance sheet and fundamentals (201 results) while it still highlights candidates the wider market has not fully recognized.
- Identify early leadership in digital assets by checking the 21 cryptocurrency and blockchain stocks before crypto sentiment shifts again and stronger operators no longer trade on under the radar valuation multiples.
- Explore long term infrastructure and electrification themes by reviewing the curated 40 power grid technology and infrastructure stocks while these grid builders remain priced as if growth is still a secondary factor.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com