
AI Optics Pivot Could Be A Game Changer For Semtech (SMTC)
- Semtech recently completed integration of its AirLink secure edge 5G and LTE routers with Palo Alto Networks next generation firewalls, while moving key optical and surge protection products into full production and ecosystem standards groups targeting 5G Advanced, AI networks and industrial equipment.
- The combination of edge security tie ins, 50G fronthaul roll out and 200G lane XPO optics positions Semtech’s connectivity portfolio more tightly around AI data center traffic growth, which aligns with analyst commentary that focuses on the firm’s pivot toward higher value optical and data center solutions.
- Next, the focus shifts to how Semtech’s tighter link to AI oriented optical infrastructure could influence the longer term investment narrative.
Semtech Investment Narrative Recap
To own Semtech, you need to be comfortable with a story that leans heavily on data center optics, 5G transport and higher value protection devices rather than legacy IoT connectivity. The near term swing factor is execution on those newer portfolios while keeping gross margins from drifting lower as product mix shifts. The recent announcements reinforce that pivot but do not fundamentally change the key questions around margin quality and earnings durability.
The biggest risk still sits in integration and mix. Prior goodwill impairment, exposure to cyclical infrastructure spending and pressure from lower margin segments remain front of mind. These AI and 5G linked launches improve Semtech’s positioning, yet they also raise the bar on on time delivery, R&D productivity and design win conversion.
The 50G fronthaul portfolio moving into full production is the announcement most tied to the current AI centered narrative around Semtech. It plugs the business directly into the optical plumbing required for Ericsson and Nokia radio platforms that are built to handle heavier AI and AR traffic from mobile devices. That places more operational weight on Semtech’s signal integrity segment.
For you, the practical question is whether this 50G product ramp can offset volatility in other areas and support the high growth expectations already embedded in earnings forecasts and a rich P/E multiple. Any delay in carrier or vendor deployments, competitive pricing pressure or technical hiccups in volume rollouts would quickly test the idea that Semtech can sustain its margins and returns at current levels.
Analysts sketch a path for Semtech that reaches forecast revenues of $2.3b and earnings of $546.9m by 2029, built on expected yearly revenue growth of 27.5%. That projection moves from current earnings of a $33.2m loss to the 2029 consensus, which is a $580.1m improvement in absolute profit terms.
Uncover why Semtech's fair value indicates a 12% potential upside to its current price that may not last much longer.
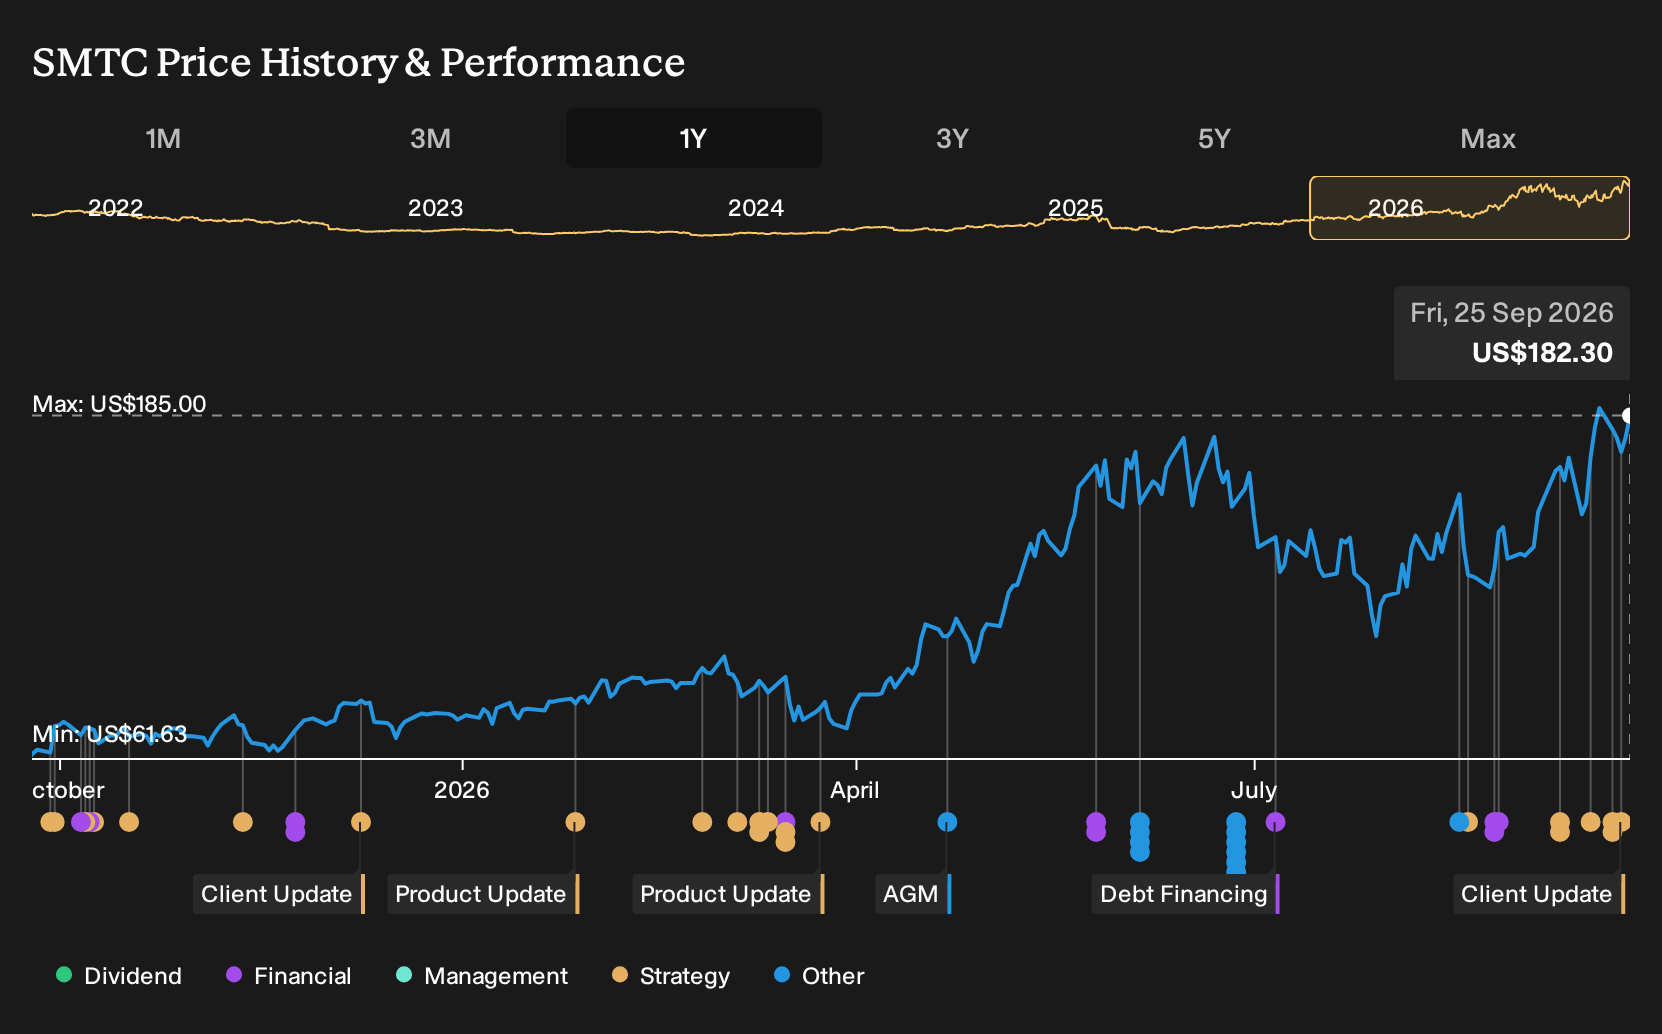
Exploring Other Perspectives
Some readers may focus on a different risk. The most cautious analysts worry that Semtech’s heavy AI data center tilt could backfire if hyperscalers slow upgrades. Before this news, the lowest forecasts still had revenue reaching about $2.5b and earnings around $769.8m by 2029, yet with a much lower P/E and valuation story. These views were all formed before the Palo Alto Networks integration and 50G fronthaul updates, so you may want to compare several of these viewpoints and decide which future you find more convincing.
Explore 2 other Semtech fair value estimates, including one that suggests as much as 48% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Semtech research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Semtech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Semtech's overall financial health at a glance.
Looking for more investment ideas beyond Semtech?
If the Semtech story has sharpened your thinking on AI infrastructure and optical networks, it can help to compare it with other listed businesses that share certain financial traits or risk profiles. The Simply Wall St Screener lets you move from a single ticker to a broader watchlist built around the qualities you care about most.
- If you prefer companies that combine resilient balance sheets with solid fundamentals and want a quick way to filter for them, then start with this list of solid balance sheet and fundamentals (24 results).
- If potential undervaluation is your priority and you want businesses that may offer more quality for each dollar paid, scan through the 32 high quality undervalued stocks to see what fits your criteria.
- If you are interested in lesser known opportunities that still show strong underlying metrics, then cast a wider net with the 16 high quality undiscovered gems to round out your research list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com