
Casella Waste Systems (CWST) Has Investors Asking A Bigger Question
Casella Waste Systems (CWST) has drawn investor attention after recent share price weakness, with the stock down about 12% over the past month and roughly 13% over the past 3 months.
At a share price of $82.24, Casella Waste Systems has seen momentum fade, with the stock down over the past week and month and the year-to-date share price return weaker than its multi-year total shareholder returns, which remain positive over three and five years.
Compare Casella Waste Systems' recent pullback with other potential rebound candidates by scanning our hand picked 32 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
For Casella Waste Systems, the question is whether this pullback signals a shift in how the market feels about the stock or a change in what the underlying business is worth. It is time to test that against the valuation.
Most Popular Narrative: 27% Undervalued
Casella Waste Systems is trading at $82.24 against a widely followed fair value estimate of $112, which frames the recent share price weakness as a potential valuation gap rather than a settled verdict on the business.
The heightened focus among municipalities, universities, and commercial clients on sustainability and ESG-driven solutions is increasing demand for Casella's Resource Solutions segment. This demand is strengthened by recent investments in upgraded recycling facilities and innovative processing capabilities, which is supporting top-line revenue growth and resiliency against commodity price swings.
See why 3 investors see Casella Waste Systems as 27% undervalued.
Result: Fair Value of $112 (UNDERVALUED)
Still, the Casella Waste Systems story leans heavily on successful acquisition integration and disciplined capital spending. As a result, prolonged margin pressure or weak post deal cash generation could quickly challenge this valuation gap.
Find out about the key risks to this Casella Waste Systems narrative.
Another View on Casella Waste Systems Valuation
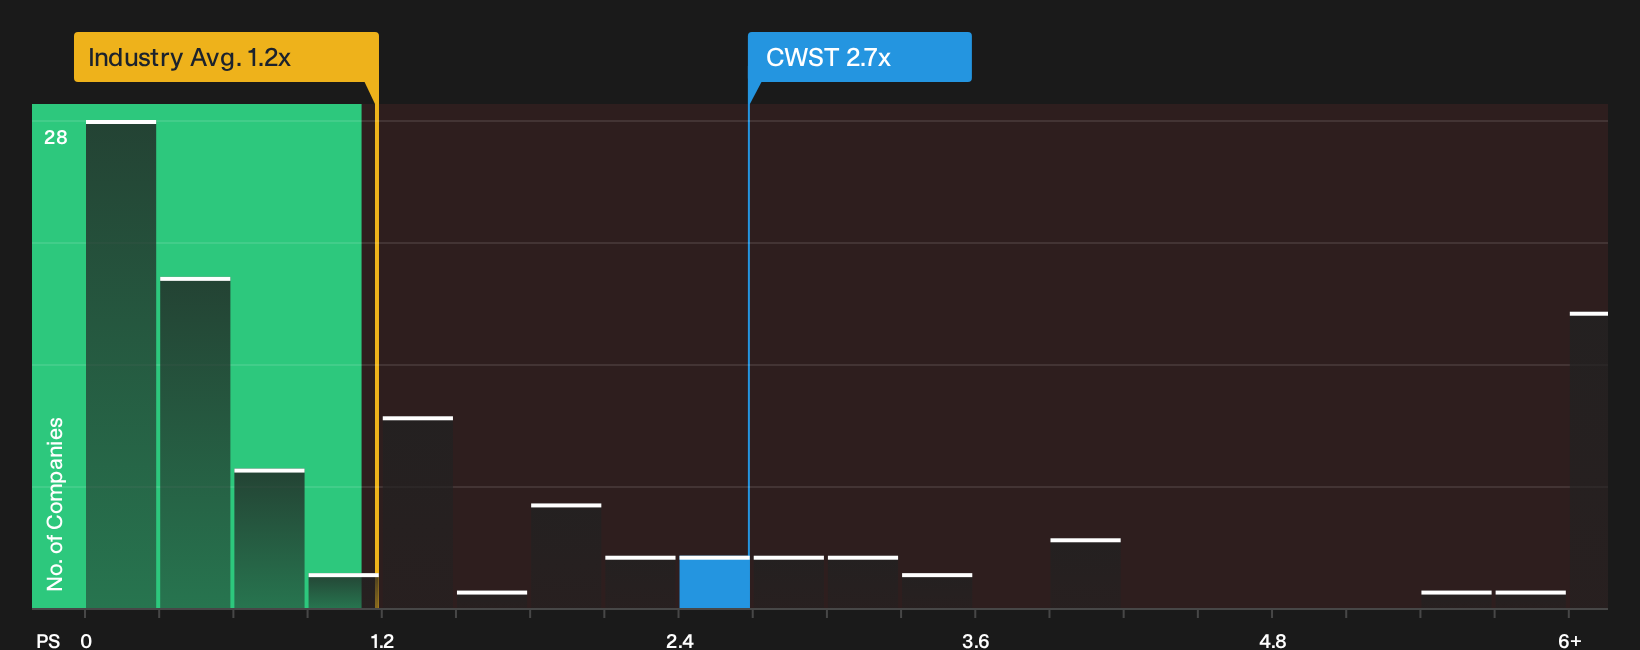
While the narrative fair value for Casella Waste Systems points to a 27% gap to $112, the market message from pricing multiples is very different. The stock trades on a P/S ratio of 2.7x, compared with a fair ratio of 1.7x and a US Commercial Services sector average of 1.2x. This implies investors are already paying a sizeable premium that could compress if expectations ease. Which signal do you trust more when the story and the sticker price disagree?
See what the numbers say about this price, find out in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Casella Waste Systems feel messy, that is the point; you are meant to weigh both sides. Get the full picture with 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Casella Waste Systems?
If Casella Waste Systems has you rethinking your watchlist, this is the moment to broaden your opportunity set and reassess where your next dollar goes.
- Target higher income potential by reviewing a focused shortlist of income plays through 8 dividend fortresses that emphasise yield with supportive fundamentals.
- Stack the odds toward financial resilience by scanning a list of solid balance sheet and fundamentals (24 results) that can better handle shocks and funding demands.
- Get ahead of the crowd by tracking 16 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com