
British Undervalued Stocks To Watch In September 2026
With UK bond yields influenced by a global reset in borrowing costs, investors are paying closer attention to companies that can fund themselves from their own operations rather than relying heavily on debt markets. That puts strong cash generators trading below estimated fair value in a useful spotlight. This article highlights three undervalued British stocks where current cash flow profiles look interesting on a discounted cash flow basis.
The stocks covered below are a small sample of the opportunities highlighted by Simply Wall St’s cash flow work. The full screen surfaces 10 additional companies that have similarly interesting stories from a discounted cash flow perspective but are not detailed here.
If you want to go straight to the source and identify, compare, and analyze candidates for your own watchlist, head into the Undervalued Stocks Based On Cash Flows screener.
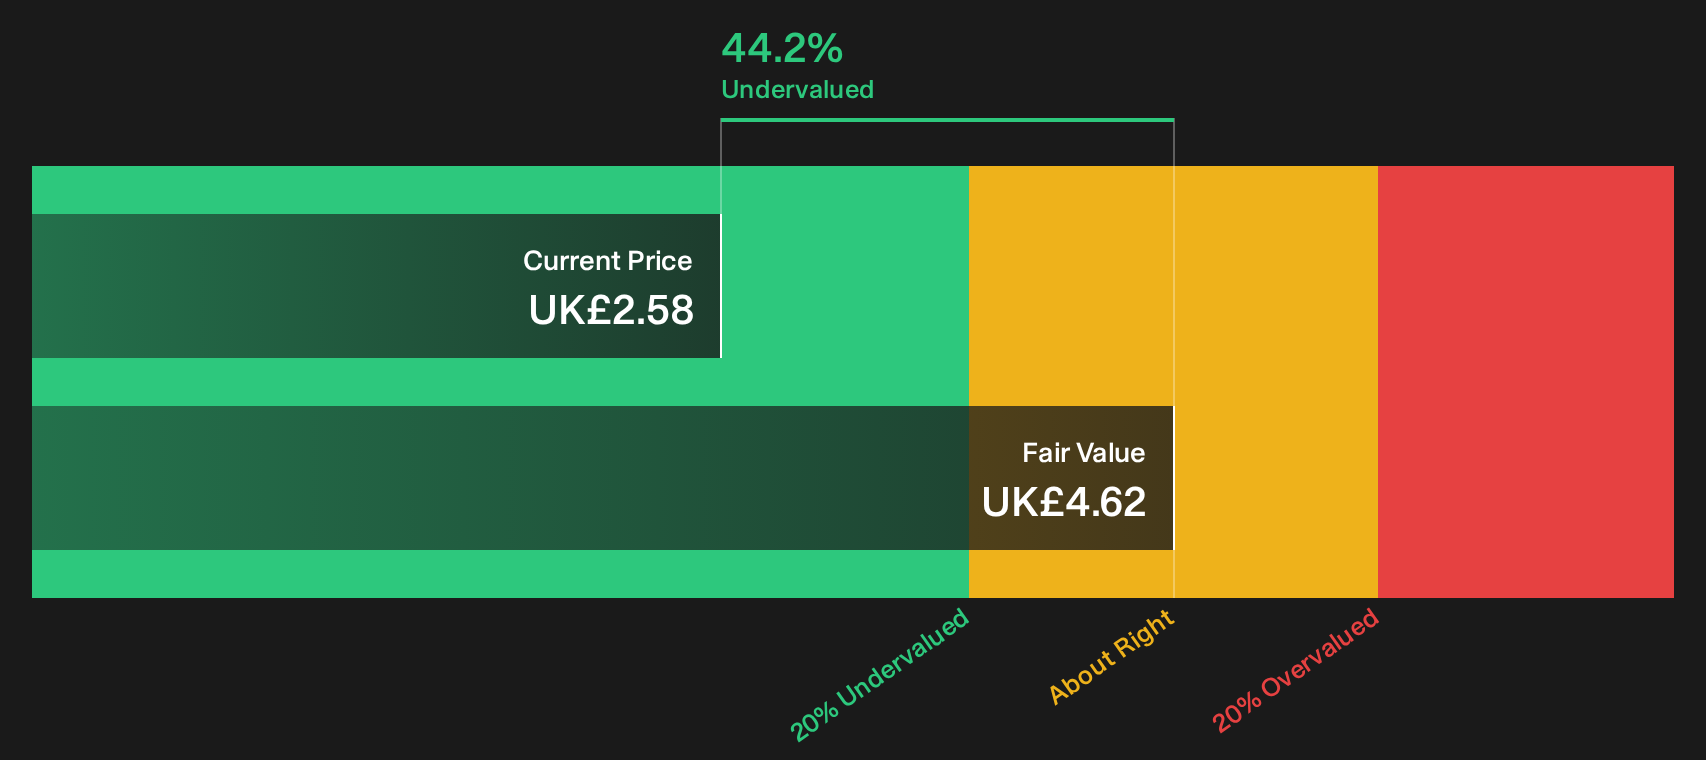
LSL Property Services (LSE:LSL)
Overview: LSL Property Services runs a capital light UK platform across surveying and valuation, mortgage and insurance advice, and franchised estate agency services.
Operations: LSL Property Services generates about £110.7 million from Surveying and Valuation, £48.2 million from Financial Services, and £26.7 million from Estate Agency, all in the United Kingdom.
Market Cap: £254 million
LSL Property Services sits squarely in this cash-flow-focused screen because its surveyor-led valuation and conveyancing-packaging work creates recurring fees rather than one-off windfalls.
"Structural growth in the private rental sector, supported by LSL’s program of lettings book acquisitions for franchisees, is expanding high visibility, recurring income streams that can smooth cyclicality in housing transactions and support group revenue resilience and net margins."
The real test for LSL Property Services is how one unseen pressure on funding costs and balance sheet flexibility shapes those margins.
If that funding pressure is what you are watching, read the full narrative for LSL Property Services to see how LSL Property Services’ cash engine could be accelerating or stalling next.
AltynGold (LSE:ALTN)
Overview: AltynGold is a London headquartered gold producer. Its Sekisovskoye mine and Teren Sai projects in Kazakhstan underpin its cash flow story.
Operations: The business generates about $175 million from exploration and development at the Sekisovskoye gold asset in the Republic of Kazakhstan.
Market Cap: £294 million
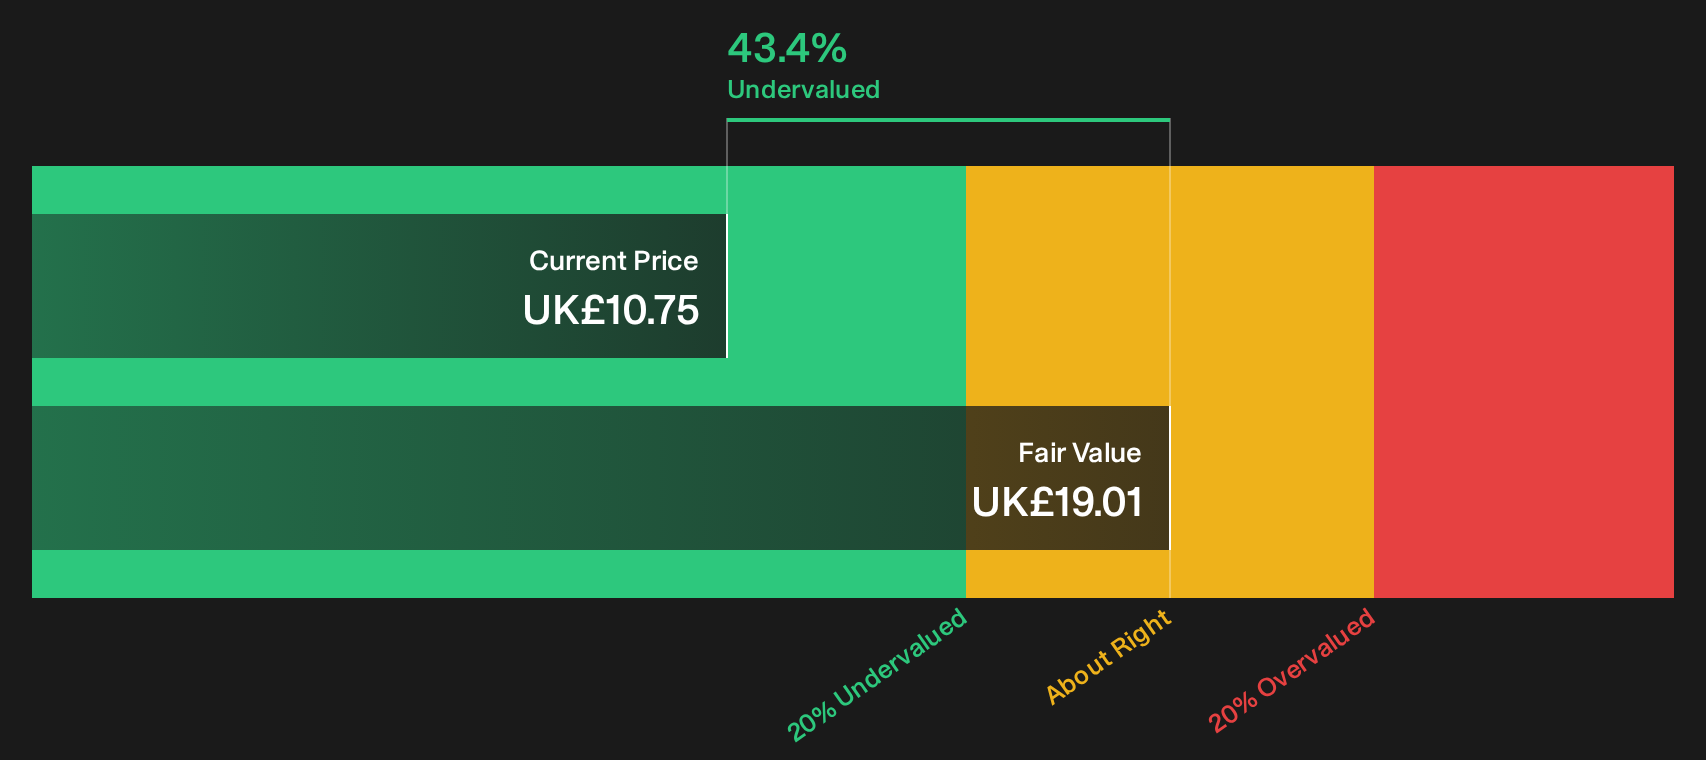
AltynGold reports a 35.4% net margin, 41.3% ROE and a 6.3x P/E, while trading 43.4% below an estimated fair value based on cash flows. These metrics place the Sekisovskoye and Teren Sai projects at the center of the potential opportunity for value focused investors, depending on how one unseen pressure related to gold linked cash generation develops.
That funding question is exactly why it is worth reading the analysis report for AltynGold to see whether AltynGold’s cash engine is quietly decoupling from the gold price.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings runs funds that manage renewable infrastructure assets alongside private equity and venture strategies for institutional and retail investors.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, mainly across the United Kingdom and Australia.
Market Cap: £476 million
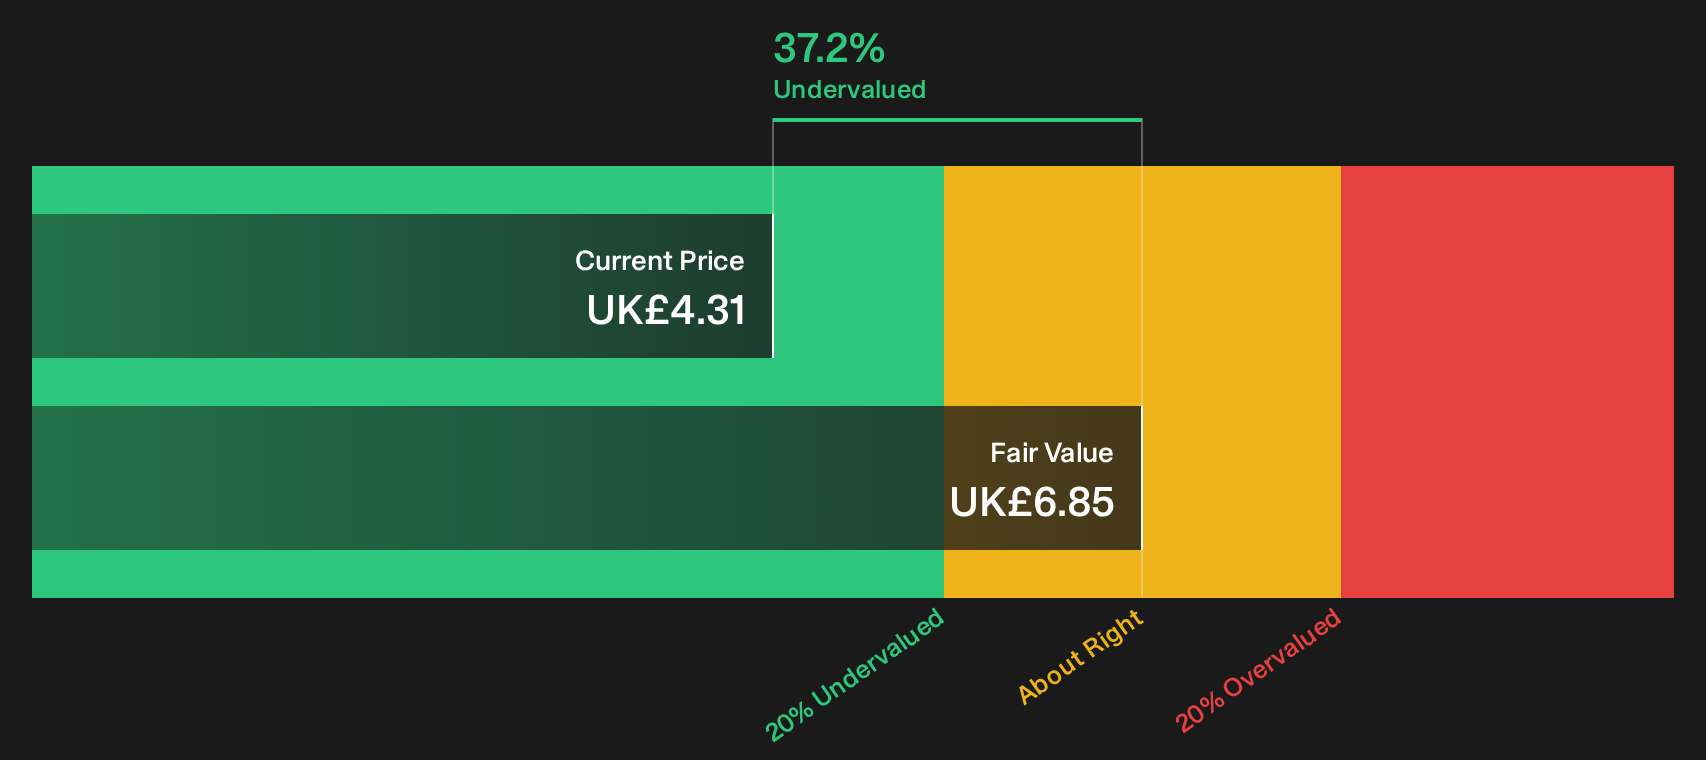
Foresight Group Holdings matters for this cash flow screen because its renewable infrastructure funds and platforms can produce relatively steady fee streams that plug neatly into discounted cash flow work.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is expected to contribute to compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and the return of capital accelerates."
What really moves the needle for Foresight Group Holdings is how one unseen pressure on fundraising momentum and fee mix shapes those future margins.
Those margin swings are exactly what the full narrative for Foresight Group Holdings unpacks, showing where Foresight Group Holdings could be accelerating fee power and where hidden risks might be quietly building.
Seeking Fresh Alternatives For Your Curiosity
Fresh ideas move first. Breakout stories and quiet compounders rarely stay under the radar for long before momentum catches up. Scan these curated picks now and review them while they are still less widely followed.
- Identify cash generative compounders at an earlier stage by reviewing the 5 high quality undiscovered gems curated for strong balance sheets and resilient earnings profiles.
- Monitor consistent income opportunities by scanning the 1 dividend fortresses built around robust payout histories and solid coverage.
- Review potential metal supply dynamics by exploring the 36 best rare earth metal stocks focused on producers and developers with meaningful exposure to critical materials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com