
How New Camera Lenses Will Impact Sony Stock Investors
- Sony Group recently introduced two compact G Master super telephoto primes, the FE 400mm f/4.5 and FE 600mm f/6.3, targeting high performance outdoor and wildlife imaging with lighter builds and advanced autofocus and stabilization features.
- The new lenses add a middle tier in Sony Group's super telephoto lineup, giving professionals and serious hobbyists lighter, more accessible tools that can still pair with high resolution bodies for flexible cropping and field use.
- This article examines how Sony Group's broader investment narrative is shaped by these compact G Master lenses in the imaging segment.
Sony Group Investment Narrative Recap
To own Sony Group, you generally need to believe the shift toward content, services, sensors and creator hardware can offset pressure in legacy electronics and cyclical hardware. The compact G Master super telephotos fit that creation centric push, but by themselves they are unlikely to move group earnings near term, particularly with quarterly revenue expected to soften.
The more immediate swing factors still sit in PlayStation engagement, content monetization and the Imaging & Sensing Solutions pipeline, while geopolitical and supply chain costs remain key risks. The new lenses help defend Sony Group's imaging positioning, yet do not materially change those broader catalysts or the operational risk profile investors are already weighing.
The launch of the FE 400mm f/4.5 and FE 600mm f/6.3 G Master primes is the clearest link between this news and Sony Group's existing catalysts. These lenses lean into higher value creator gear, which aligns with the push toward creation centric devices and sensor based ecosystems that support more durable, higher margin revenue over time.
On the flip side, this type of product expansion keeps Sony Group exposed to competition in imaging and to hardware related supply chain pressures that analysts already flag as risk factors. Execution now rests on keeping these premium tools tightly tied to Sony bodies, services and sensor leadership, so that each lens sale supports the broader earnings mix investors are watching.
Sony Group's current analyst narrative points to revenue of ¥13,819.9b and earnings of ¥1,439.0b by 2029, based on forecast yearly top line growth of 2.9% and an earnings increase of roughly ¥325.0b from ¥1,114.0b today.
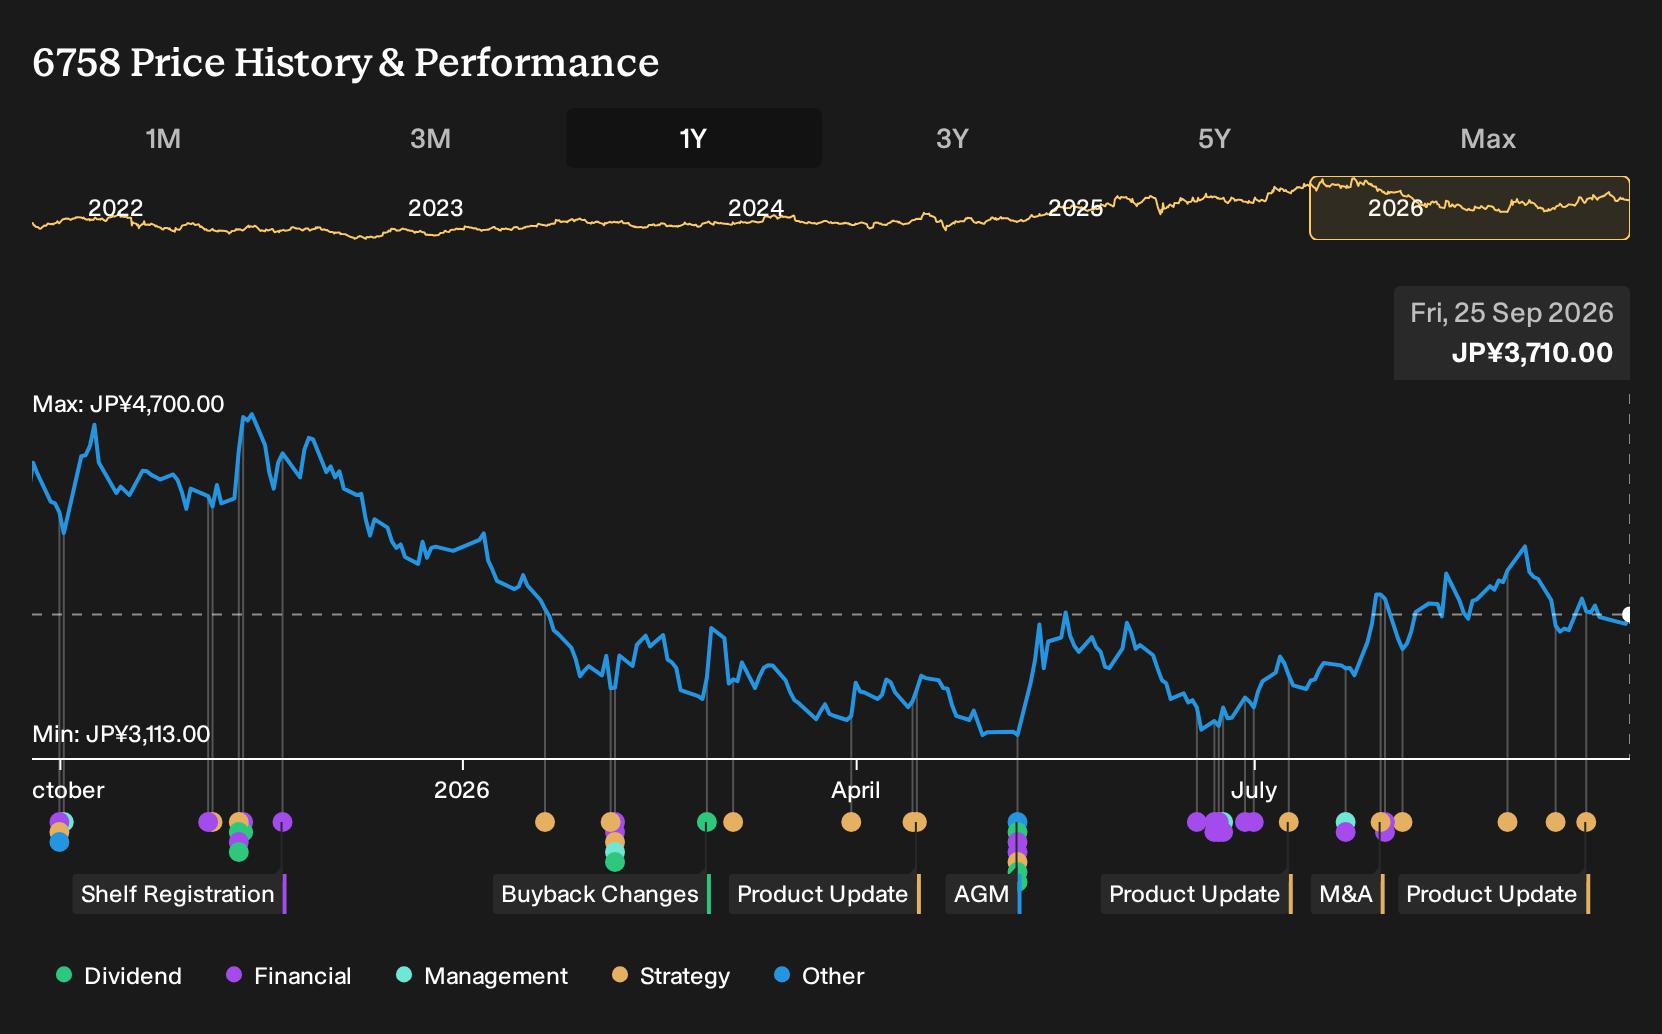
Uncover why Sony Group's fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on gaming risk rather than imaging upside. The most bearish analysts saw Sony Group revenue easing toward ¥12,209.9b by 2029 with earnings only around ¥1,118.9b, which is far below the consensus path. Those forecasts were set before these compact G Master launches, so opinions may shift.
Explore 2 other Sony Group fair value estimates, including one that suggests it could be worth just ¥4,848!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sony Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sony Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sony Group's overall financial health at a glance.
Looking for more investment ideas beyond Sony Group?
If the Sony Group story has you thinking about where else quality, durability and sensible pricing power might show up, the Simply Wall St Screener can help you cast a wider net without losing focus on fundamentals.
- If you prefer strong balance sheets and resilient business models over excitement and hype, then start with a list of solid balance sheet and fundamentals (22 results) that filters for financial strength and staying power.
- If capital preservation and steadier return profiles matter most to you, review a 21 resilient stocks with low risk scores that concentrates on businesses with lower assessed risk scores.
- If you want exposure to companies that still fly under most radars, yet have fundamentals you can actually underwrite, then scan a 74 high quality undiscovered gems and see what else might deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com