
How $1b Buyback At AerCap Holdings (AER) Has Changed Its Investment Story
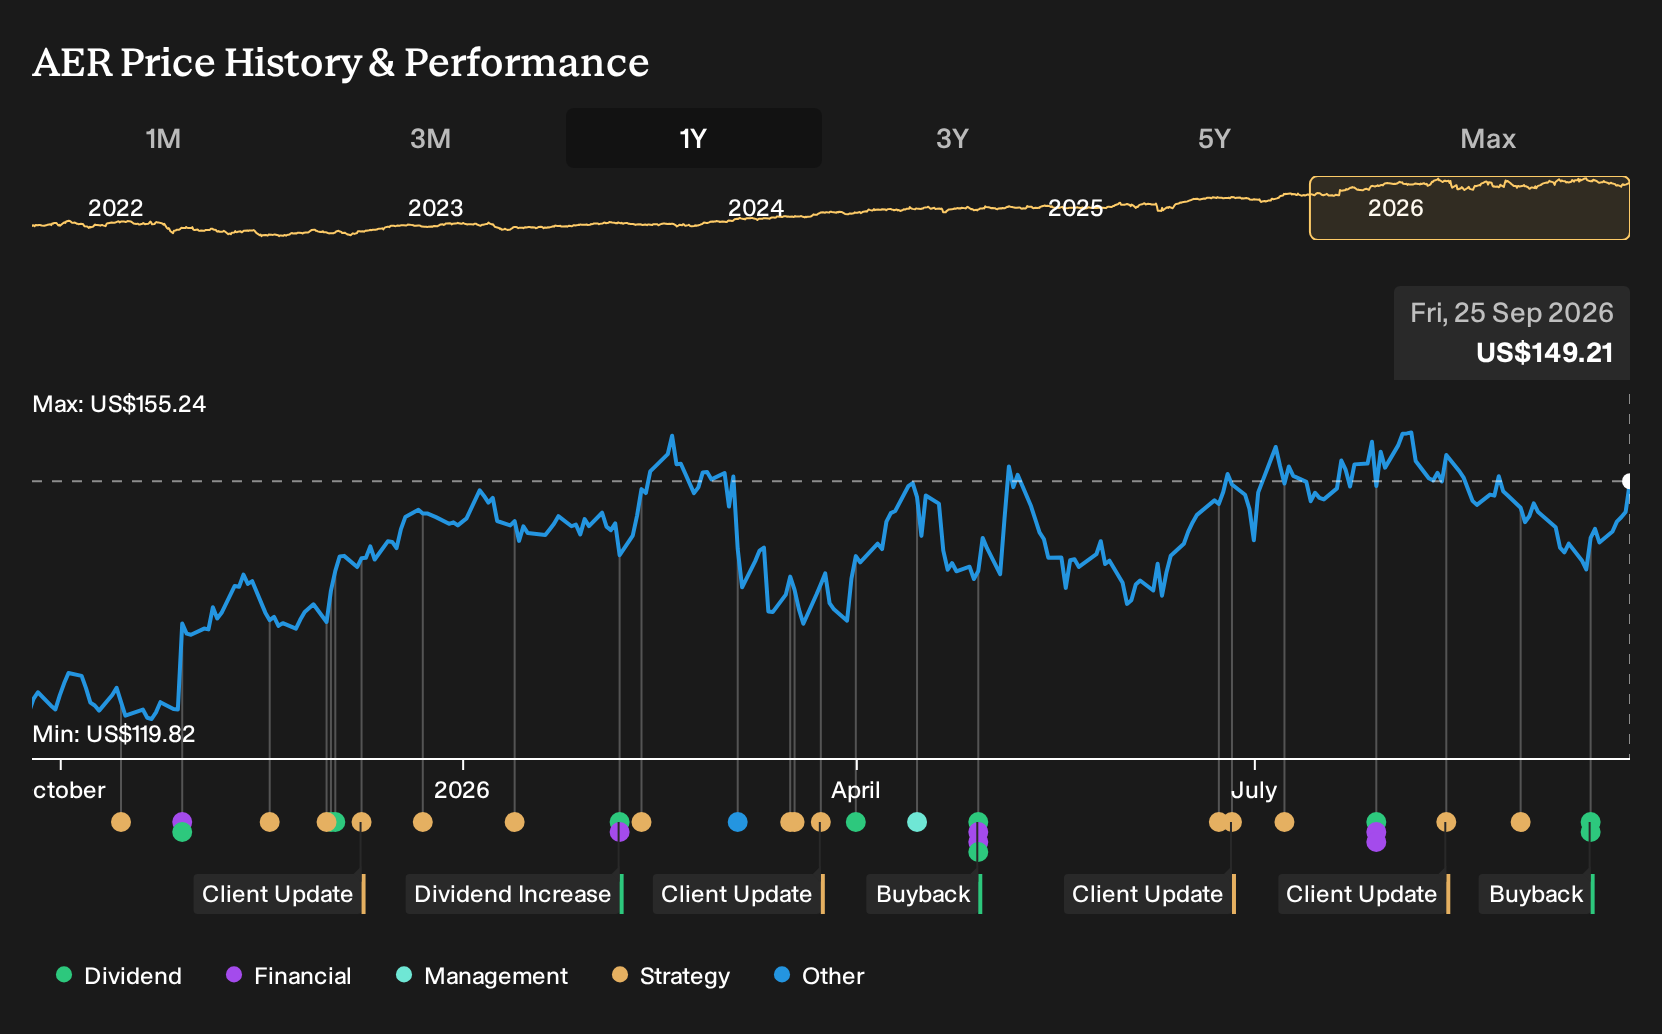
- AerCap Holdings has authorized a new share repurchase program that allows the firm to buy back up to US$1b of its stock through June 30, 2027. The program is expected to be funded by cash on hand and cash generated from operations.
- The buyback authorization highlights AerCap Holdings' capacity to return capital while still relying on internal cash generation. This directly links capital allocation choices to the underlying leasing, engine, and helicopter cash flows that investors already track.
- We will now look at how AerCap Holdings' US$1b repurchase authorization reshapes the investment narrative around cash returns and execution.
Compare AerCap Holdings' new buyback move with other companies returning cash to investors by scanning our hand picked 8 dividend fortresses alongside capital return programs like this one.
AerCap Holdings Investment Narrative Recap
AerCap Holdings appeals to shareholders who buy into a cash focused leasing model that converts aircraft, engine and helicopter assets into rent, sale gains and, eventually, capital returns. The key near term swing factor is how tight aircraft supply and high lease extension rates translate into utilization and earnings, while analysts still flag falling revenue and profit forecasts over the next three years.
The new US$1b repurchase authorization does not materially change those core business drivers. It does reinforce that management expects internal cash generation to remain robust, which can support per share metrics if asset sale margins and airline health hold up. The main operational risk remains pressure on airlines from higher fuel costs or weaker demand that could impact gains on sale and lease economics.
The buyback plan approved on September 16, 2026 is the announcement that matters most here. A US$1b authorization, funded by cash on hand and cash from operations, directly intersects with expectations for ongoing asset sales, an 85% passenger lease extension rate and customer interest in newer, fuel efficient aircraft.
For you as a shareholder, the question is whether AerCap Holdings can keep generating enough surplus cash while analysts project earnings to decline 9.7% per year and revenue to fall 2.1% annually over the next three years. Execution on engines, cargo conversions, helicopters and the record asset sale program will be important in offsetting those headwinds and in supporting any future repurchase activity under this plan.
AerCap Holdings' narrative projects US$8.3b revenue and US$2.4b earnings by 2029. This assumes revenue will decline 2.6% per year and earnings will fall by about US$1b from US$3.4b today.
Uncover why AerCap Holdings' fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value estimates for AerCap Holdings, yet they already span a wide band from about US$179 to US$345 per share. Those views pre date the new US$1b buyback and do not factor in risks like elevated fuel costs or executive share sales, so you are seeing how far opinions can diverge. Use that spread as a prompt to explore several alternative viewpoints before leaning on any single narrative.
Explore another AerCap Holdings fair value estimate, including one that suggests it could be worth just $179.30!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AerCap Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AerCap Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AerCap Holdings' overall financial health at a glance.
Looking for more AerCap Holdings sized ideas?
If AerCap Holdings has sharpened your focus on cash generation, capital returns, and valuation, use that same lens across a broader opportunity set with the Simply Wall St Screener.
- For investors who want income without ignoring balance sheet strength, scan a curated group of 8 dividend fortresses that combine yield with financial resilience.
- If the goal is to pay a fair price for quality, filter for 32 high quality undervalued stocks that pair solid fundamentals with conservative valuations.
- When you prefer to keep risk in check while still staying in equities, start with 30 resilient stocks with low risk scores and focus your research on businesses with steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com