
Is Upcoming Earnings Altering The Investment Case For Progress Software Stock (PRGS)?
- Progress Software is scheduled to report Q3 2026 results after the close on 30 September, with analysts estimating earnings per share of $1.52 and close attention on revenue trends and cost efficiency.
- The recent upward shift in earnings estimates highlights how much weight investors are placing on the ability of Progress Software to sustain margins while managing efficiency initiatives.
- We will look at how the investment narrative for Progress Software lines up with rising Q3 EPS expectations and focus on margin sustainability.
Scan beyond Progress Software ahead of this earnings release and review hand picked peers with resilient fundamentals in the 32 high quality undervalued stocks.
Progress Software Investment Narrative Recap
To own Progress Software, you need to believe this is a steady compounder in application infrastructure and AI tooling, where recurring revenue from products like ShareFile, OpenEdge and Sitefinity can support consistent cash generation even if headline growth is modest. The near-term hinge is whether Q3 confirms that the recent margin improvement and efficiency push are repeatable rather than a one off.
The biggest short-term catalyst is clear earnings visibility around the SaaS and AI portfolio, and whether profitability holds while the firm leans into cloud delivery and integration work. The key risk is execution. Cost of cloud infrastructure, M&A integration and interest expense could pressure margins if operational discipline slips.
The most relevant backdrop to this Q3 release is the earlier progress management has flagged on integrating ShareFile, which has already fed into higher ARR, revenue and expense savings. You are essentially watching to see if those benefits now flow cleanly through to earnings power without eroding service quality or product momentum.
ShareFile also connects directly to the current catalysts. A larger SaaS base can improve revenue predictability, support AI features across the portfolio and potentially offset slower growth elsewhere in the stack. The risk is that reliance on acquired SaaS assets, funded by higher-risk borrowing and carrying interest costs, makes consistent margin delivery harder if integration or cloud spending runs ahead of plan.
Progress Software's current earnings sit at $89.0 million, with analysts expecting profits to decline to $74.3 million by 2029 as revenue stays broadly flat. That outlook implies earnings falling by $14.7 million, even though the consensus still pencils in about $1.0 billion in sales for 2029.
Uncover how Progress Software's fair value indicates a 42% potential upside to its current price before the discount narrows.
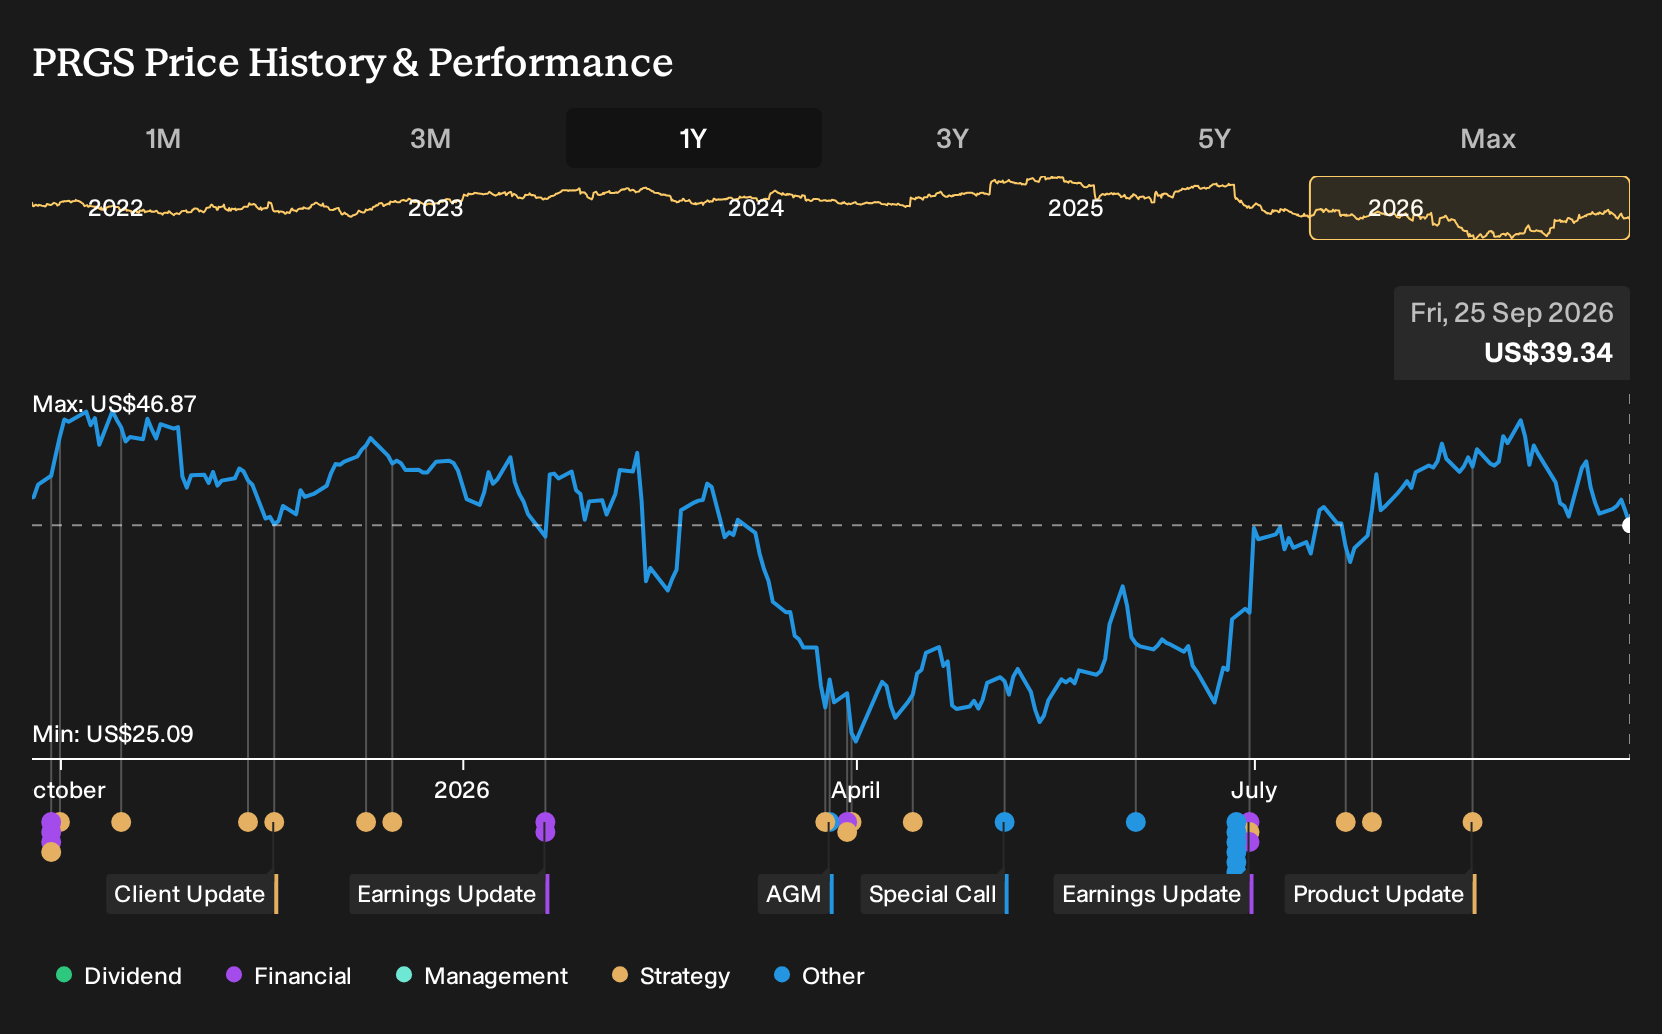
Exploring Other Perspectives
One alternate view around Progress Software puts cloud competition front and center. The most cautious analysts worry that hyperscale vendors could squeeze future maintenance income, so they plug in 2029 earnings of about $71.0 million on roughly $1.0b of sales. Those forecasts, set before this Q3 release, outline a far more conservative path. Use them as a reference point to stress test your own expectations as results come in and opinions inevitably shift.
Explore 2 other Progress Software fair value estimates, including one that suggests it could be worth just $40.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Progress Software research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Progress Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Progress Software's overall financial health at a glance.
Looking for more Progress Software investment ideas?
If this Progress Software earnings story has sharpened your thinking, use the broader market as your hunting ground. The Simply Wall St Screener can help you quickly filter for other companies that match the kind of balance, income or upside profile you are searching for.
- If capital preservation sits high on your list, start with a group of companies that score well on resilience and risk by reviewing the 30 resilient stocks with low risk scores.
- Income focused investors can zero in on cash generators with meaningful yields by scanning the 8 dividend fortresses.
- If you want to find businesses with strong fundamentals that are not yet crowded trades, go through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com