
Should Franchisee Bankruptcy Require Action From Wendy's (WEN) Investors?
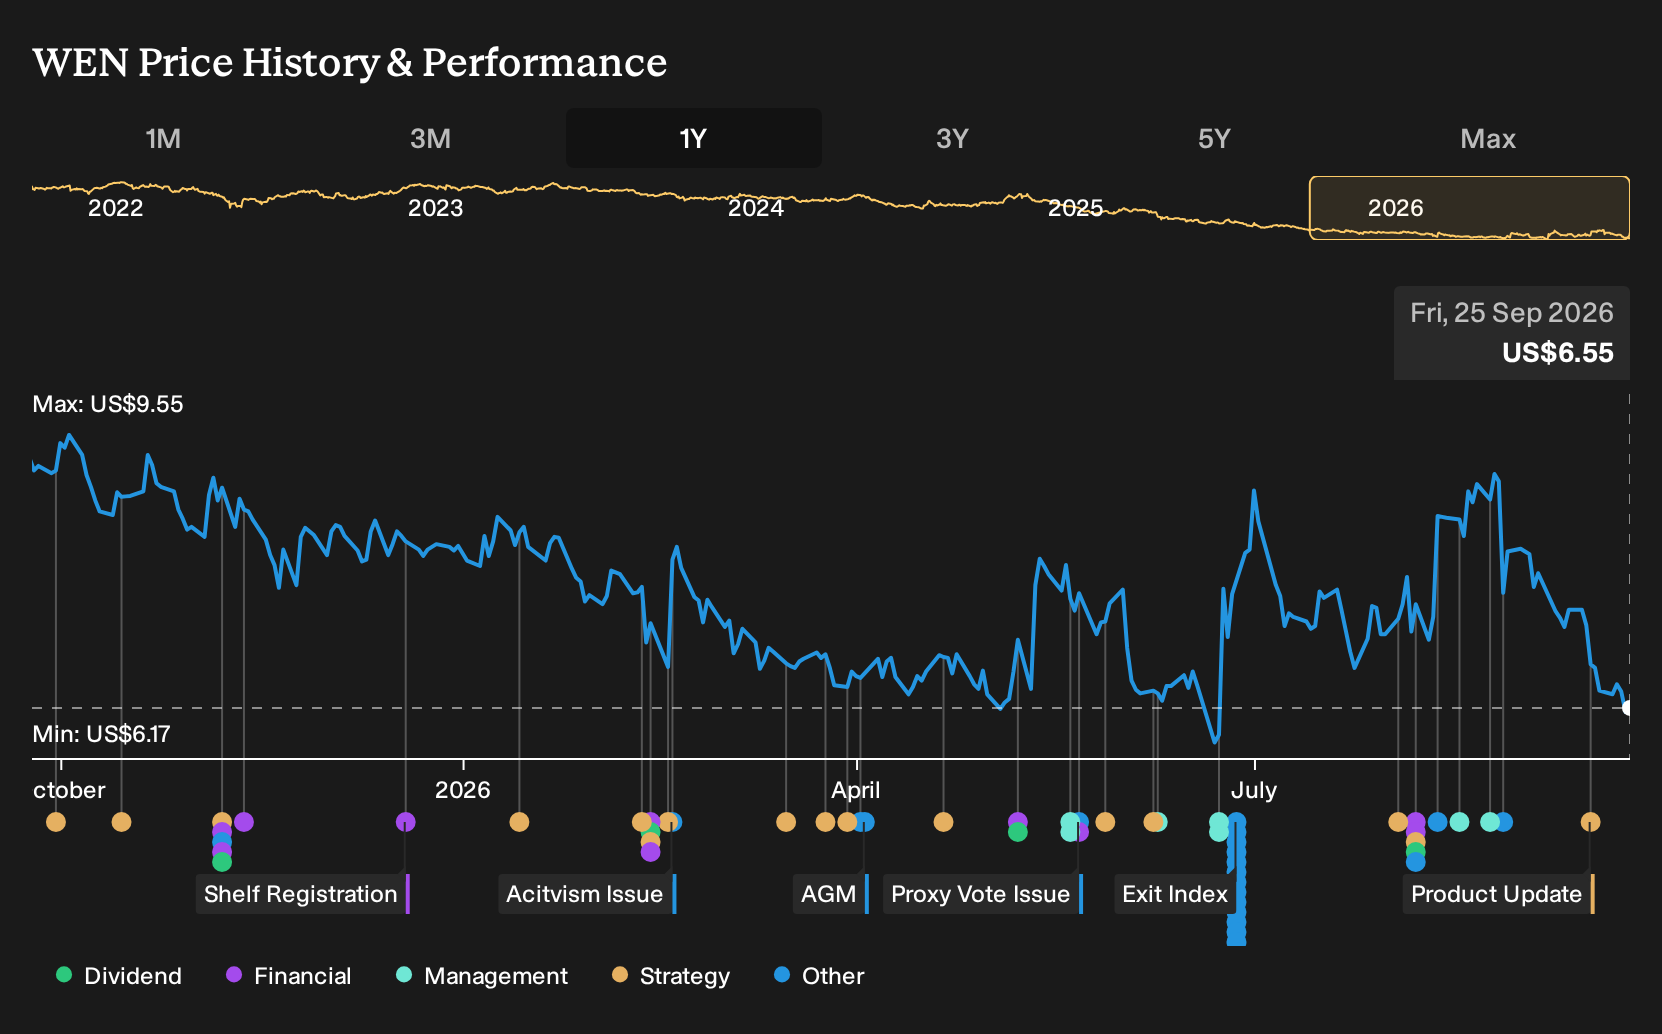
- Meritage Hospitality Group, which operates 314 Wendy's locations across 15 states, filed for Chapter 11 bankruptcy after Wendy's issued a termination notice on its franchise agreement, while the chain also pushed ahead with limited time promotions such as Lisa Barlow's Baby Gorgeous Meal and related app based sweepstakes.
- The Meritage bankruptcy highlights financial strain and sales pressure within a large portion of Wendy's U.S. franchise system, raising questions about operational resilience, capital needs, and how effectively the brand can support franchise profitability while still funding marketing tie ins and digital promotions.
- Attention now turns to how Wendy's investment narrative holds up in light of the Meritage bankruptcy and its impact on franchise system health.
Pressure test Wendy's story against other consumer-focused plays by scanning a curated set of 32 high quality undervalued stocks with solid fundamentals and potential for sentiment to shift.
Wendy's Investment Narrative Recap
For Wendy's, the core belief is that the brand can keep customers coming through a mix of menu news, digital ordering and a broad franchise footprint, even as competition and cost pressure stay intense. The immediate operational swing factor now is franchise system stability. The Meritage bankruptcy puts more weight on how quickly management can support at risk operators while keeping stores open and standards consistent.
The biggest risk in the near term is franchisee profitability and unit closures, especially with interest costs and commodities already squeezing margins and advertising spend under pressure. The recent dividend cut keeps more cash inside the business, which can help fund store level support or remodels, but only if that capital translates into better sales trends and healthier franchise economics.
The Lisa Barlow Baby Gorgeous Meal sits right at the intersection of Wendy's short term needs. It is an app only and DoorDash only offer that pushes customers into digital channels where ordering tends to be more efficient and data rich. That supports the broader plan around mobile, loyalty and targeted offers without requiring large new physical investments.
This promotion also matters for franchisees wrestling with traffic and price sensitive guests. Limited time bundles can help defend share against aggressive discounting from rivals, while the app based sweepstakes and Bravo Fan Fest activation aim to keep the brand visible even as ad budgets face pressure. The operational test is whether campaigns like this drive repeat visits at acceptable margins rather than just one off promotional spikes.
What Wendy's Analyst Forecasts Are Actually Pricing In
Wendy's narrative projects US$2.3b in revenue and US$137.4m in earnings by 2029. That outlook assumes revenue expands at 1.7% per year and that earnings decline by about US$27.7m from US$165.1m today.
Discover why Wendy's fair value indicates a 22% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate Wendy's story leans on aggressive international expansion as the real swing factor, not just digital promos like the Baby Gorgeous Meal. In that optimistic view, analysts were penciling in about US$2.4b of revenue and US$149.9m of earnings by 2029. That is more upbeat than consensus, and the Meritage news could easily reshape those expectations.
Explore 5 other Wendy's fair value estimates, including one that suggests as much as 88% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Wendy's research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Wendy's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wendy's overall financial health at a glance.
Looking For More Ideas Beyond Wendy's?
If the Meritage story has you reassessing Wendy's, it can help to widen the lens and compare it with other opportunities that share some of the same themes around quality, balance sheets and income potential.
- For investors who care most about strong finances and durable business models, start with a curated list of solid balance sheet and fundamentals (24 results) to help you focus on resilience first.
- If downside risk is front of mind after the latest franchise headlines, narrow your search to a 30 resilient stocks with low risk scores that screens for resilience and quieter price swings.
- For readers who want quality plus the chance that the market is underestimating the story, scan a 16 high quality undiscovered gems that highlights companies with solid fundamentals yet limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com