
3 Canadian Growth Stocks With Earnings Growth Up To 67%
With U.S. Treasury yields sitting near 5% and pulling money toward safer government bonds, many investors are overlooking a pocket of Canadian growth stories where executives have serious skin in the game. That combination of fast expanding businesses and high insider ownership can be powerful for patient shareholders. This article walks through three stocks from this growth and alignment screen that merit a closer look at this time.
The three Canadian growth stories below are just a sample, and the full screen surfaced 46 more companies where insiders own a meaningful stake and the growth narrative is just as compelling. To identify, compare, and analyze those additional opportunities with high insider alignment, head straight into the Fast Growing Stocks With High Insider Ownership screener.
Colliers International Group (TSX:CIGI)
Colliers International Group is a global commercial real estate and engineering specialist whose capital markets and investment management arm ties directly into the fast growing stocks with high insider ownership theme through fee income linked to transaction activity and assets under management.
Colliers generates about US$3.5b from commercial real estate services, US$1.9b from engineering work, and US$562 million from investment management, with a market value near CA$6.5b.
For investors focused on growth that is closely aligned with owner incentives, Colliers International Group offers a mix of recurring fees and transaction driven upside that fits this screener’s focus on optimistic growth expectations from both analysts and management.
"The growing interest from institutional and private wealth channels in alternative asset classes such as data centers, student housing, infrastructure, and credit solutions is driving segment diversification and AUM growth in the investment management business, supporting future recurring fee revenue and higher net margins."
What matters next is how one quiet shift in the business feeds through to margins and the durability of that fee stream.
That margin story is only part of it, and the full narrative for Colliers International Group lays out how Colliers International Group’s shifting mix could reshape resilience, risks, and upside potential.

Cascades (TSX:CAS)
Cascades is a Canada based packaging and tissue producer where the higher growth e commerce and protective packaging lines give the fast growing stocks with high insider ownership theme a very tangible anchor.
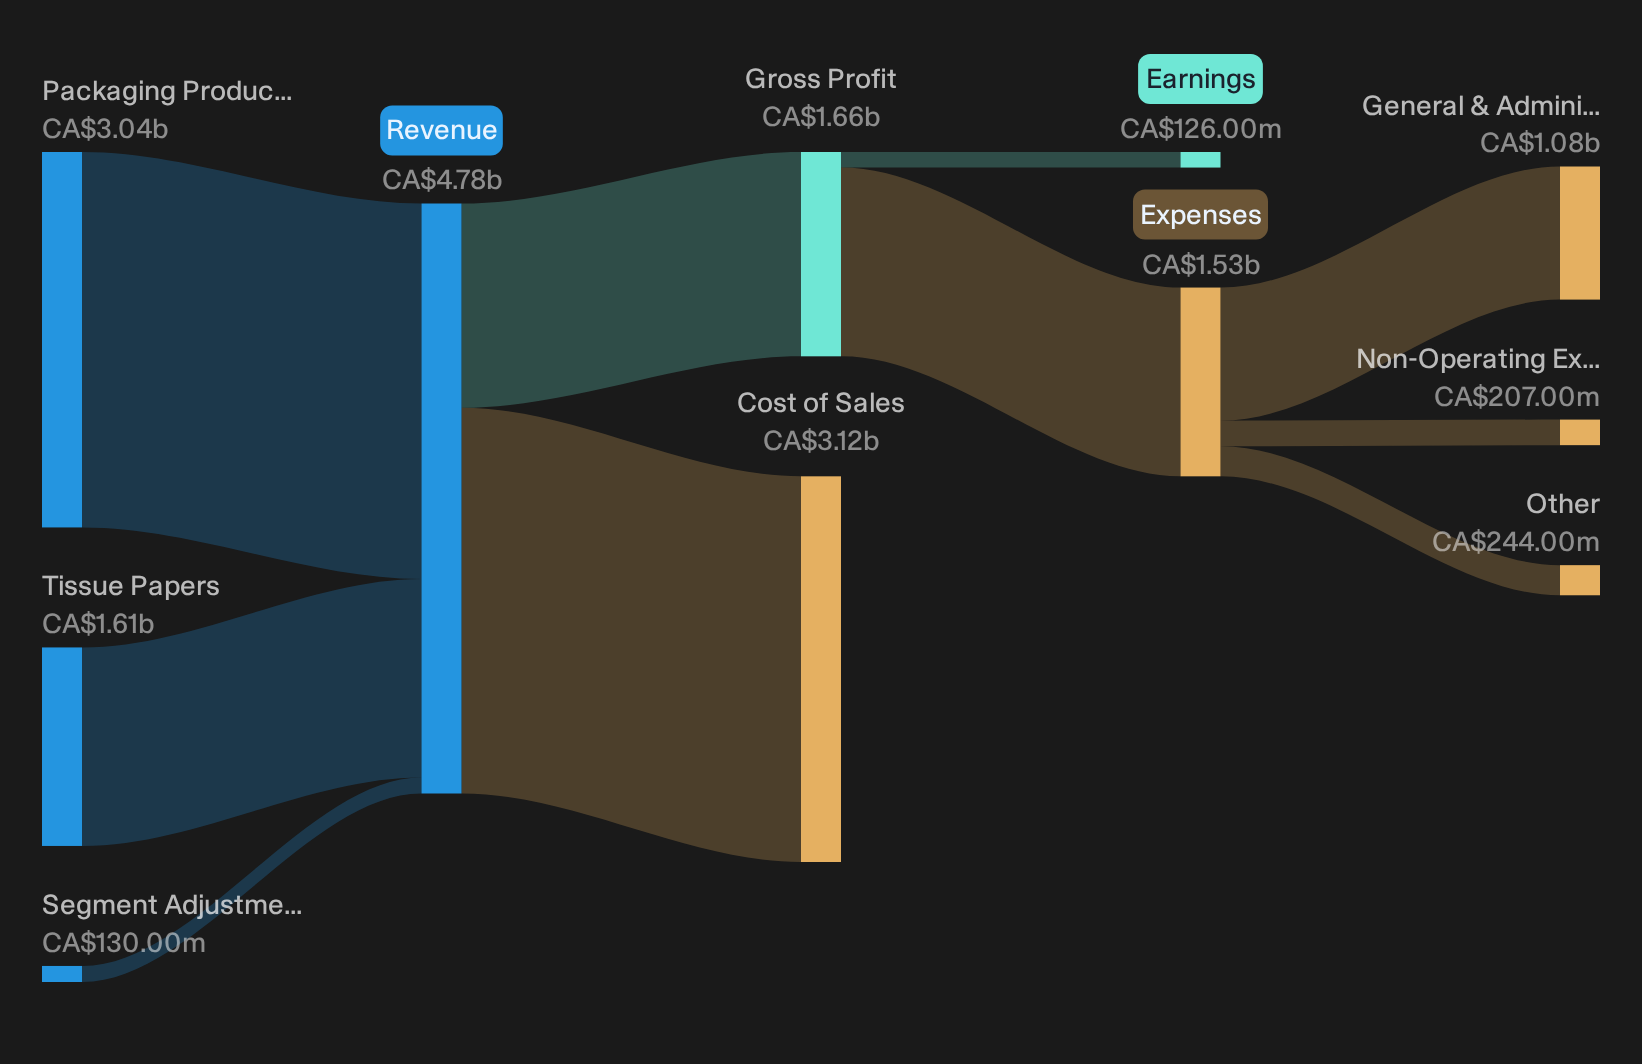
Cascades generates about CA$3.0b from Packaging Products and CA$1.6b from Tissue Papers, with a market value around CA$1.9b.
The appeal for growth focused investors is how this packaging platform, especially the e commerce solutions, is being reshaped by cost work so more of every sales dollar can drop to the bottom line.
"Ongoing profitability initiatives, already contributing roughly $10 million sequentially and targeting a $100 million run rate uplift by the end of 2026, position the company to expand earnings even in a flat demand environment through lower unit operating costs."
The key question is what happens to that earnings path if one unseen pressure on packaging demand and pricing does not break Cascades’ way.
If that risk is what worries you, the full narrative for Cascades shows how Cascades could still turn cost wins into accelerating value creation for long term holders.
Highlander Silver (TSX:HSLV)
Highlander Silver is a junior precious metals explorer focused on acquiring, exploring, and advancing silver and gold deposits in Peru, anchored by its 100% owned San Luis project, with a market value around CA$1.5b.
Highlander Silver fits into this growth and insider alignment theme because San Luis is a single, 100% owned asset that analysts expect to support earnings growth of about 67% a year and revenue growth of roughly 47% a year, depending on how one unseen pressure plays out.
That pressure cuts both ways, so check the analyst forecasts for Highlander Silver to see how bullish expectations compare with Highlander Silver’s project risk and potential operating leverage.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every chart lights up, the early entries are gone and spreads are widening. Scan under the radar for now and act now.
- Target steady compounding potential with resilient balance sheets by screening a curated list of solid balance sheet and fundamentals (7 results) before everyone else starts focusing on the same defensive stories.
- Explore the next wave of automation progress by zeroing in on hand picked industrials from the 92 robotics and automation stocks while expectations are still developing.
- Consider positioning ahead of a potential materials move by reviewing the focused 36 elite gold producer stocks and monitoring producers before short-term traders increase their activity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com