
Kimco Realty (KIM) Conference Spotlight Keeps Undervalued Narrative In Focus
Kimco Realty (KIM) is set to participate in the BofA NY Global Real Estate Conference on 15 September 2026, where CEO Conor C. Flynn is scheduled to outline the positioning of its open-air shopping center portfolio.
Recent trading tells a mixed story. Kimco Realty’s 1 month share price return is down 5.63% and its 3 month share price return is down 13.12%. However, the year to date share price return of 11.86% and 3 year total shareholder return of 47.14% point to momentum that has built over a longer period as investors weigh conference updates and the broader outlook for open air retail centers.
Scan how Kimco Realty compares with other real estate plays by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) that may appeal to investors focused on resilience and income potential.
Recent weakness in Kimco Realty contrasts sharply with its multi year gains and improving profit and revenue figures. Are investors reacting to the business on the ground, or simply resetting sentiment ahead of fresh valuation work?
Most Popular Narrative: 17% Undervalued
Kimco Realty last closed at $22.44, while the most followed narrative pegs fair value closer to $26.92. As a result, the upcoming conference arrives with sentiment implying the portfolio could be mispriced relative to its modeled earnings power.
Exceptional leasing spreads, record small shop occupancy and strong tenant demand in Kimco Realty’s centers continue to feed into a signed but not open pipeline of about US$95 million of annual base rent, which can lift revenue and same-property NOI as these leases commence and close the roughly 400 basis point gap between physical and economic occupancy.
See why 7 investors see Kimco Realty as 17% undervalued.
Result: Fair Value of $26.92 (UNDERVALUED)
Still, the Kimco Realty story can unravel if refinancing on 2026 debt bites harder than expected or if the Target-anchored redevelopment lawsuit escalates.
Find out about the key risks to this Kimco Realty narrative.
Another View on Kimco Realty’s Valuation
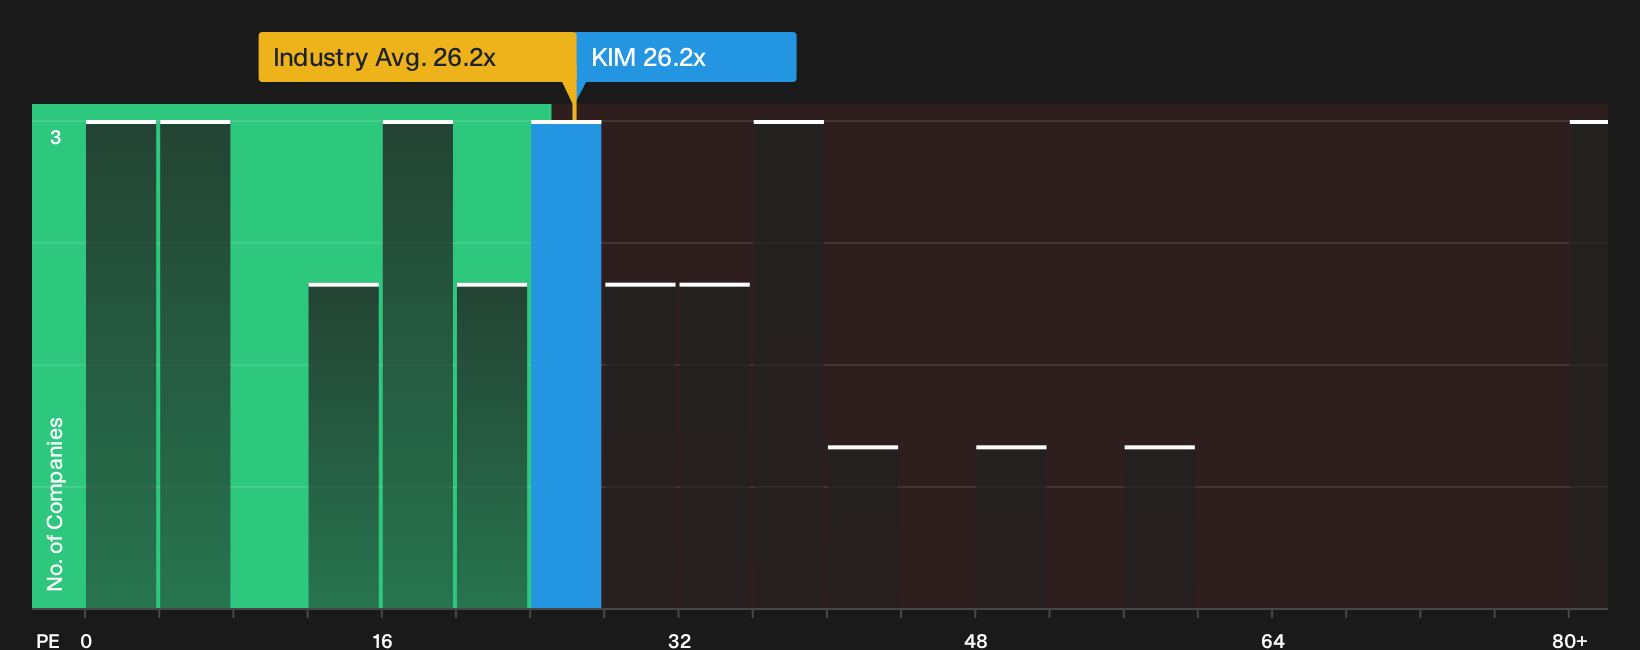
Kimco Realty looks inexpensive on cash flow, yet its earnings multiple tells a tighter story. The stock trades on a P/E of 26.2x, very close to the US Retail REITs average of 26.2x, while the fair ratio sits higher at 32.4x. That gap suggests room for re rating if earnings unfold as expected, but also raises the question of how much patience investors really have for a slower growth REIT.
See what the numbers say about this price by reviewing our valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Kimco Realty is clearly split. If you care about both the upside story and the potential hazards, review the details closely and weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Kimco Realty?
If Kimco Realty has sharpened your thinking, do not stop here. Broaden your watchlist with fresh ideas that fit clear, disciplined investing angles.
- Target resilient income by reviewing a curated set of higher yielding candidates through 8 dividend fortresses geared toward investors who care about consistent cash returns.
- Hunt for mispriced quality and scan the 32 high quality undervalued stocks that filters for stronger fundamentals at prices that may leave room for upside.
- Prioritize capital preservation and stress test your portfolio against a 30 resilient stocks with low risk scores designed for investors who want steadier rides through volatile periods.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com