
BancFirst (BANF) Dividend Meets Slower Growth On An Undervalued Narrative
BancFirst (BANF) is back in focus after the bank declared a quarterly dividend of $0.52 per share, even as recent commentary has highlighted slower revenue momentum and expectations of rising operating costs.
At a share price of $108.71, BancFirst has seen a 1-day share price return of 1.27%, while the 30-day share price return is down 1.66% and the 90-day share price return is down 3.17%. This points to cooling near-term momentum despite a positive year-to-date share price return of 2.10% and a 5-year total shareholder return of 91.80%, which still reflects a much stronger longer-run outcome.
Broaden your watchlist beyond BancFirst by scanning hand-picked banks with sturdier growth and balance sheets, using the list of solid balance sheet and fundamentals (24 results) as a starting point.
Bulls point to BancFirst’s fresh dividend and long run record, while bears focus on softer recent returns and pressure on profitability. Which story does the current valuation actually support next?
Most Popular Narrative: 13% Undervalued
The most followed valuation narrative pegs BancFirst’s fair value at $124.33, above the recent $108.71 close. This sets up a clear debate around how much of its long term compounding story is already reflected in the share price.
Top quartile to top decile returns on assets and equity create room for BancFirst to compound tangible book value beyond the current US$49.20 level. This can support growth in earnings and potential improvement in return based valuation multiples.
See why 1 investors see BancFirst as 13% undervalued.
Result: Fair Value of $124.33 (UNDERVALUED)
Still, the whole BancFirst story can wobble if Tulsa acquisitions drag on efficiency or if slower revenue trends eventually squeeze the premium P/E and valuation multiples.
Find out about the key risks to this BancFirst narrative.
Another View on BancFirst’s Valuation
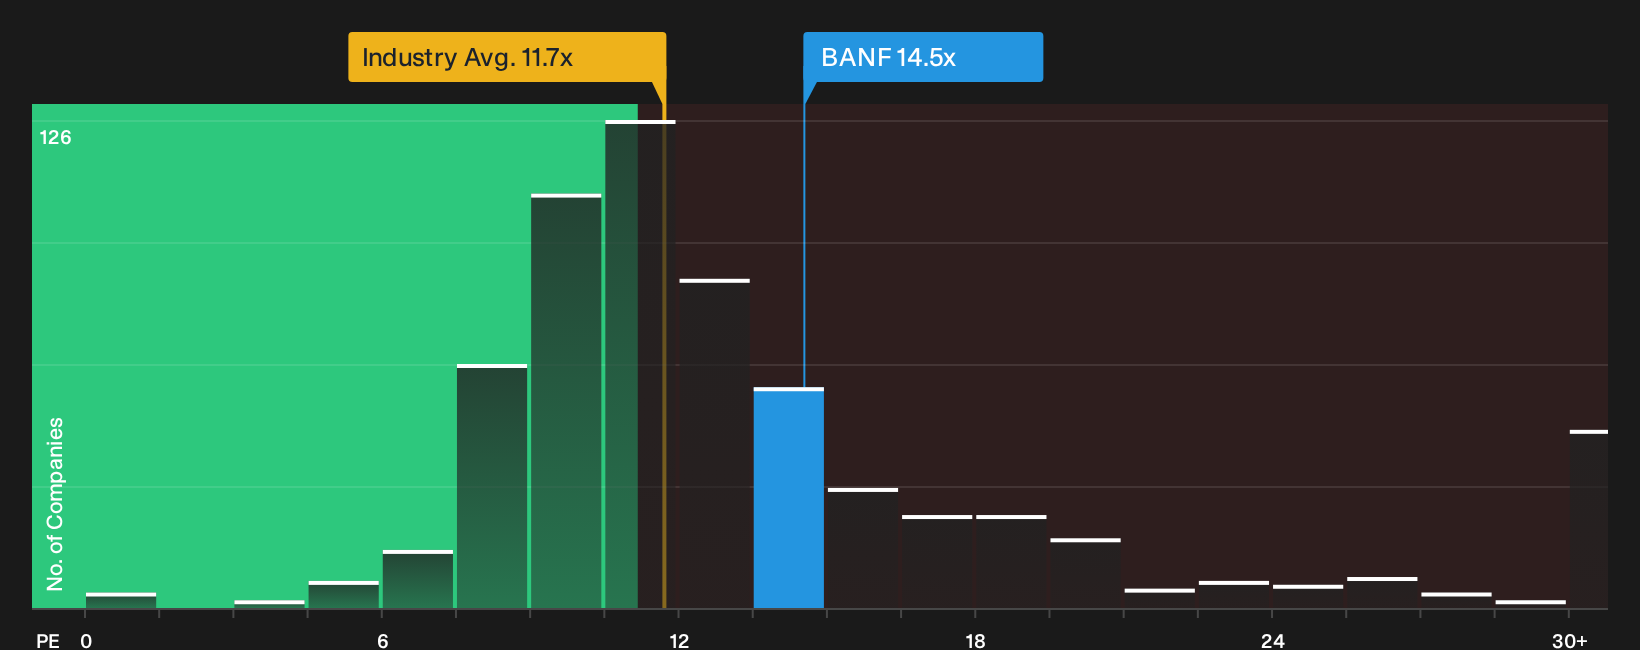
On a simple earnings multiple, BancFirst trades at a P/E of 14.5x, richer than both the US Banks industry at 11.7x and its peer average of 13.9x, and also above an estimated fair ratio of 11.6x. If sentiment cools, the share price could drift toward that lower benchmark.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around BancFirst can make the picture feel messy. Check the numbers yourself, move quickly if needed, and weigh the 4 key rewards and 1 important warning sign.
Looking for more BancFirst investment ideas?
If BancFirst has your attention, do not stop here. Fresh opportunities emerge constantly, and you risk missing them if you only watch one ticker.
- Target potential mispricing by scanning a curated set of quality candidates through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that appear in the 8 dividend fortresses.
- Dial down portfolio stress by filtering for resilient businesses using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com