
Is Cohen & Steers (CNS) Fully Priced Following Its Recent Pullback?
Cohen & Steers (CNS) has drawn fresh attention after recent price moves, with the stock closing at US$74.20. Investors are weighing this level against its recent performance and current fundamentals.
Recent trading has been choppy. The 1-day share price return slipped 1.26%, the 30-day share price return is down 10.31%, yet the year-to-date share price return of 16.72% and 1-year total shareholder return of 15.91% indicate that longer term momentum is still holding up, supported by a 30.81% total shareholder return over three years.
Scan how Cohen & Steers stacks up against other asset managers by reviewing hand picked alternatives in the list of solid balance sheet and fundamentals (24 results).
After that pullback and a value score of 1, the Cohen & Steers share price poses a simple question: Does the current risk-reward still tilt toward buyers, once you line it up against the underlying valuation?
Most Popular Narrative: 1% Undervalued
Cohen & Steers is priced at $74.20 against a narrative fair value of $75.00, which leaves only a small valuation gap but still puts the focus on what could shift assets and earnings from here.
Strategic expansion into active ETFs and broader product diversification (including the launch of integrated listed/private real estate strategies) is expected to attract new investor segments and improve client retention, supporting future AUM growth and revenue stability.
Ongoing investments in global distribution, particularly in Asia-Pacific and Europe, and recent foreign office upgrades are expected to drive international client inflows and scale, with potential for margin expansion as global business grows.
See why 4 investors see Cohen & Steers as 1% undervalued.
Result: Fair Value of $75 (ABOUT RIGHT)
Still, Cohen & Steers faces two clear pressure points: ongoing institutional outflows that unsettle fee revenue, and heavier spending on global expansion that tightens profitability.
Find out about the key risks to this Cohen & Steers narrative.
Another View On Cohen & Steers' Valuation
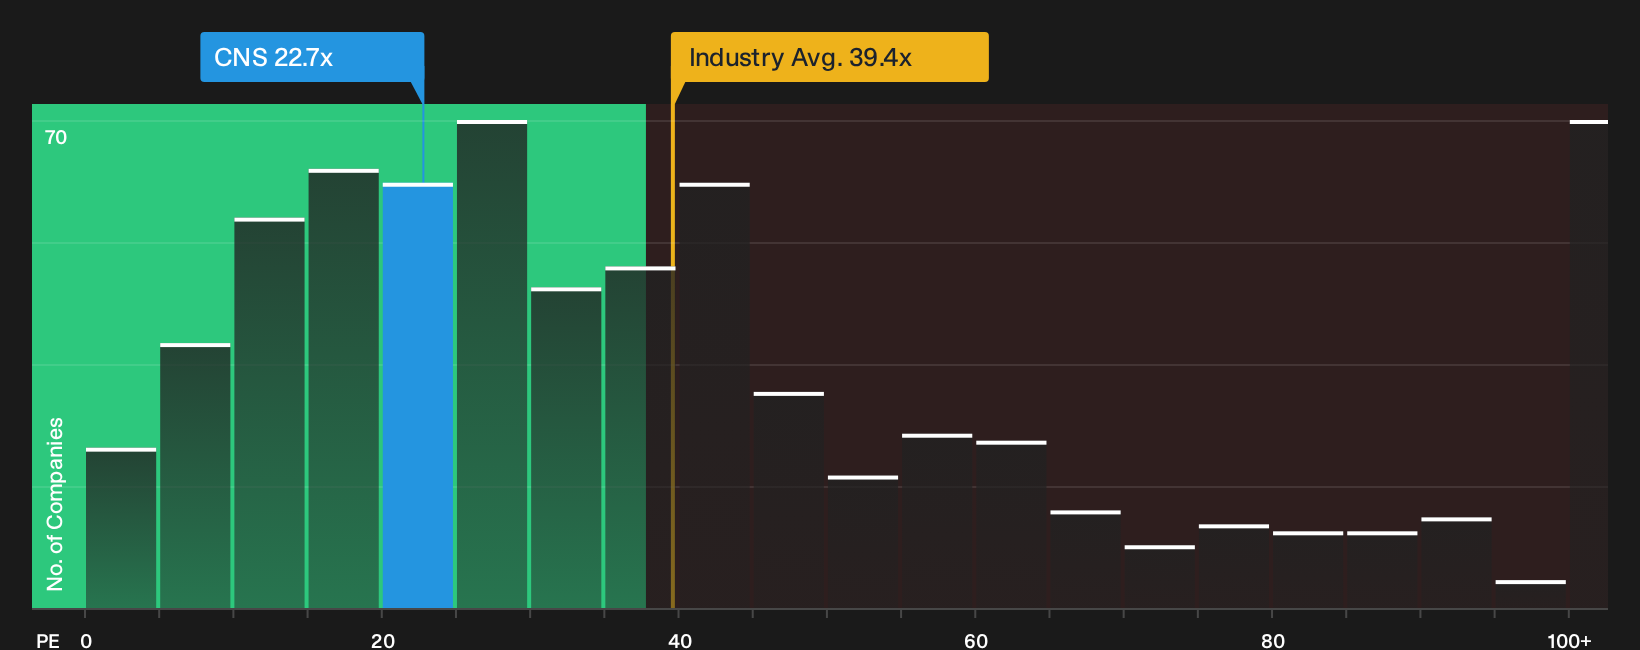
The popular story has Cohen & Steers trading close to fair value at about $75. The preferred P/E lens paints a rougher picture. The current P/E is 22.7x, while the fair ratio sits at 12.6x, and peers average just 10.2x. That is a wide gap. Is the market paying up too much for this earnings profile, or are the peers simply cheaper for a reason?
For a closer look at how this price tag compares with sector norms and where the fair ratio might pull the stock over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Cohen & Steers can be useful if you move quickly, test the narrative against the numbers yourself, and then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cohen & Steers?
Do not stop your research with Cohen & Steers. Cast a wider net with targeted screeners that help you spot opportunities before they become crowded trades.
- Target value first and hunt for quality companies trading below what their fundamentals suggest through the 32 high quality undervalued stocks.
- Build income potential into your portfolio and focus on resilient payers by reviewing the 8 dividend fortresses.
- Shift attention to stability and protect your downside by scanning the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com