
MONY Group And 2 Other British Dividend Stocks
UK inflation pressures are back in the spotlight as higher energy bills and borrowing costs squeeze household budgets, putting dependable income streams front of mind for many investors. Reliable dividend payers offering yields above 3% can help turn that squeeze into an income opportunity. This article highlights three established British dividend stocks from our high yield, well covered and steadily growing income screen.
The three stocks covered below are just a starting sample from this idea, and the full screen surfaced 64 more companies with similarly compelling income stories that are not included here. To see the wider field and identify which dividend payers best fit your own income goals, head straight into the Dividend Powerhouses (3%+ Yield) screener
MONY Group (LSE:MONY)
Overview: MONY Group runs MoneySuperMarket, MoneySavingExpert, Quidco and related UK comparison and cashback platforms that generate recurring, cash-rich leads and advertising revenues. These help underpin its role as a high yielding dividend payer.
Operations: MONY Group earned about £237 million from Insurance, £111 million from Money, £55 million from Home Services and £49 million from Cashback, with virtually all of its £448 million revenue coming from the United Kingdom in the latest reporting period.
Market Cap: £908 million
For an income investor, MONY Group matters because its MoneySuperMarket driven comparison and cashback ecosystem throws off recurring cash flows that are closely aligned with a high, covered and growing dividend profile.
"The ongoing investment in digital and AI-enabled platforms is increasing automation and operational efficiency, evidenced by a 300% improvement in tech productivity and cost reductions from replatforming, which is likely to support sustainable long-term expansion of net margins."
What happens to MONY Group’s appeal as a dividend powerhouse if one unseen pressure starts to quietly reshape its funding costs.
If that hidden pressure is on your radar, the full narrative for MONY Group explains how MONY Group’s cash engine and funding profile could be quietly decoupling.

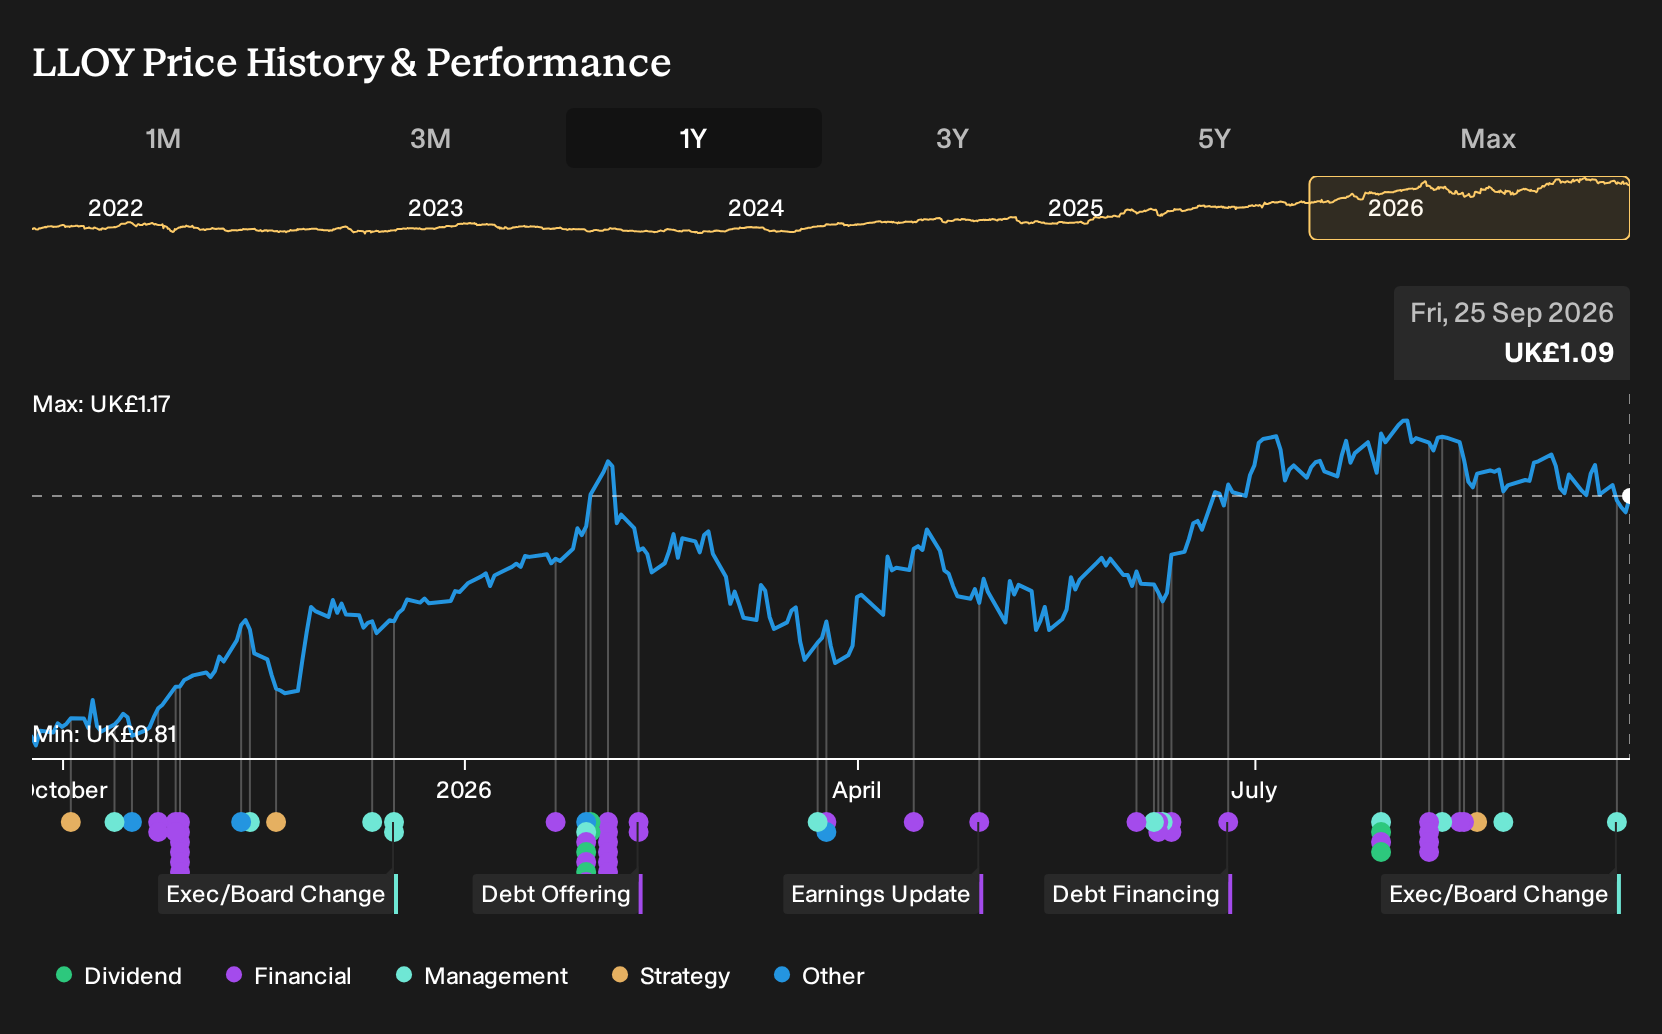
Lloyds Banking Group (LSE:LLOY)
Overview: Lloyds Banking Group runs one of the UK’s largest retail and commercial banks, using everyday accounts and lending to fund its dividend.
Operations: Lloyds generates most of its income from Retail including Wealth at about £11.9b, with £5.7b from Commercial Banking and £1.4b from Insurance, Pensions and Investments.
Market Cap: £62.6b
Lloyds Banking Group keeps showing up on income shortlists because everyday banking products, from current accounts to mortgages, are the cash engine behind its 3%+ yield. That income story is now being reshaped by a major digital overhaul.
"Digital transformation and AI adoption are reducing costs and driving efficiency, supporting margin expansion and improved earnings quality."
The real test for that dividend friendly story is what happens if a single key assumption about future credit losses starts to shift.
If that assumption is starting to shift for you, the full narrative for Lloyds Banking Group explores where Lloyds Banking Group’s earnings power could be accelerating or quietly stalling.
HSBC Holdings (LSE:HSBA)
Overview: HSBC Holdings is a global bank that earns most of its dividend supporting cash flow from long established UK and Hong Kong retail and wealth franchises.
Operations: HSBC generates about $27.5b from Corporate & Institutional Banking, $14.4b from International Wealth & Premier Banking, $15.2b from Hong Kong and $12.6b from the UK, before Corporate Centre adjustments.
Market Cap: £258.8b
For income hunters, HSBC matters because its everyday banking and wealth arms in Hong Kong and the UK throw off recurring interest and fee income that help keep a 3%+ dividend on solid footing across a very broad global footprint.
"The bank is intensifying investment in Asian wealth management and private banking, leveraging a strong brand and local presence in fast-growing wealth markets such as Hong Kong, mainland China and Southeast Asia. This strategic focus aims to capture rising affluence and middle class expansion, with the goal of growing fee income and supporting earnings and margins."
The real stress test for that income story is what happens if one unseen pressure quietly pushes credit costs off their current track.
If that risk is front of mind, the full narrative for HSBC Holdings shows how HSBC Holdings’ Asian wealth pivot could be masking both rising resilience and overlooked income torque.

Seeking Fresh Alternatives Before They Fly
Markets move fast and early signals can fade quickly as momentum builds, prices change or sentiment shifts. Consider these under the radar ideas before they become widely followed.
- Look for quality turning into momentum by scanning a curated set of underpriced compounders through the 9 high quality undervalued stocks while sentiment is still developing.
- Explore potential industrial workhorses by focusing on automation leaders surfaced in the 92 robotics and automation stocks before the theme becomes more widely recognized.
- Review infrastructure-focused companies screened in the 40 power grid technology and infrastructure stocks to analyze opportunities related to energy system build outs that may not yet be in broad focus.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com