
PropNex (SGX:OYY) Could Be 16% Below Fair Value On Its Industrial Push
PropNex (SGX:OYY) has pushed further into industrial real estate with its new “Industrial 2.0” training program and a dedicated industrial team, in preparation for a projected pipeline of more than 2,600 units in 2027.
Recent trading has been mixed for PropNex. The share price return over the past 90 days declined 4.76% and the year to date share price return is down 5.26%. The 1 year total shareholder return fell 17.14%, while the 5 year total shareholder return is up 202.92%.
Scan beyond PropNex into other real estate and property-linked stocks that have been hand-picked for their balance sheets and fundamentals with our list of solid balance sheet and fundamentals (201 results)
PropNex is leaning into industrial real estate just as its share price has been under pressure in recent months. Are investors reacting to sentiment swings, or to what this business is actually worth today?
Preferred P/E of 19.3x: Is it justified?
PropNex trades on a P/E of 19.3x, which sets the bar fairly high for a business whose earnings are forecast to grow 6.36% per year.
The P/E ratio compares the current share price to earnings per share. For a real estate services group like PropNex, this metric often reflects how confident the market is that current profit levels can be sustained and gradually built on over time.
That 19.3x multiple is below the peer average of 21.3x, which suggests investors are paying less for each dollar of earnings than the broader peer group. However, it sits above the SG real estate industry average P/E of 13.9x, which shows the market is placing a richer tag on PropNex than on the sector overall.
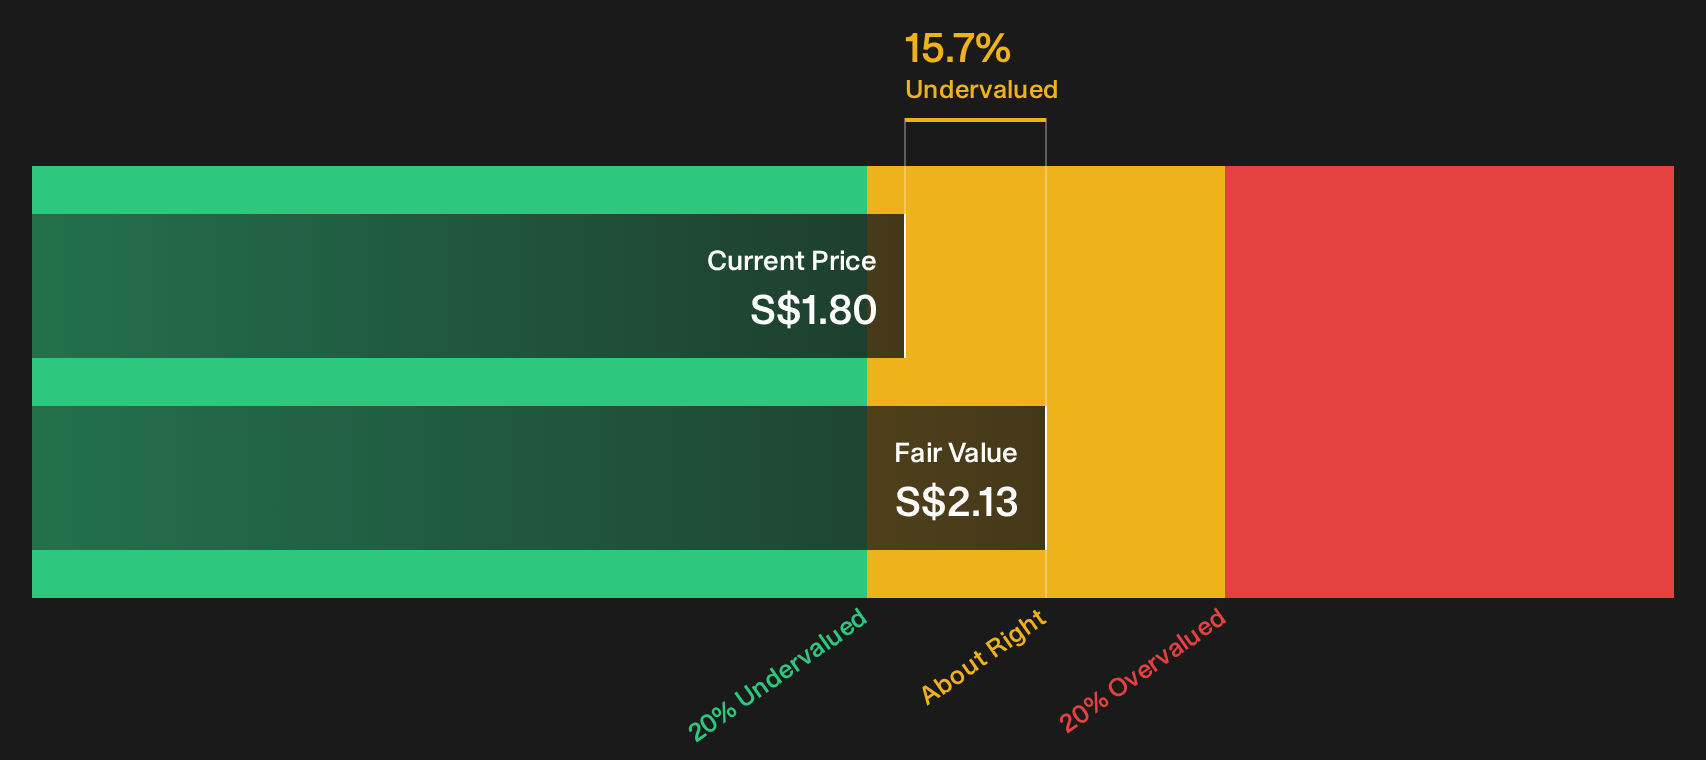
On top of that, the stock is described as trading 15.7% below an estimate of its fair value based on the SWS DCF model, while also appearing expensive versus an estimated fair P/E of 13.6x. This points to a tension between what the cash flow model implies and what the earnings multiple currently signals.
Explore the SWS fair ratio for PropNex.
Result: Price-to-Earnings of 19.3x (OVERVALUED).
Still, the PropNex story could be knocked off course if industrial project launches arrive slower than expected or if transaction volumes remain soft for a longer period.
Find out about the key risks to this PropNex narrative.
Another view on PropNex valuation
A second lens tells a different story. The SWS DCF model suggests PropNex shares at S$1.80 trade about 15.7% below an estimated future cash flow value of S$2.13. That points to a possible value gap. The real question is which signal you trust more: the earnings multiple or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PropNex for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on PropNex valuation can feel confusing, especially with both risks and bright spots in play, so move quickly and review the data for yourself. To see that balance set out in a single place, take a look at the 3 key rewards and 1 important warning sign
Looking for more PropNex style investment ideas?
If you stop with PropNex alone, you may miss other opportunities with strong balance sheets, income potential, and quieter quality that has not yet drawn attention.
- Target sturdier portfolios by scanning companies with resilient finances and consistent fundamentals through the list of solid balance sheet and fundamentals (201 results).
- Hunt for value opportunities that combine quality metrics with pricing that still looks reasonable using the 184 high quality undervalued stocks.
- Strengthen your cash flow with income focused ideas that offer higher yields and robust payout profiles via the 159 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com