
Learn Why The Bull Case For Veidekke (OB:VEI) Could Change Following New Housing Contracts
- Veidekke ASA reported two design and build wins in September 2026, securing a NOK 190 million Bryggebyen phase 4 contract in Arendal and a SEK 98 million Cederhuset apartment project in Mölndal. Both contracts are to be added to its third quarter 2026 order backlog.
- The Bryggebyen and Cederhuset awards expand Veidekke’s residential pipeline across Norway and Sweden, add long-dated projects with completion targets in 2028, and indicate ongoing client demand for design and build execution in urban housing developments.
- This development helps shape Veidekke’s investment narrative through the addition of new Scandinavian residential design and build contracts.
What Is Veidekke's Investment Narrative?
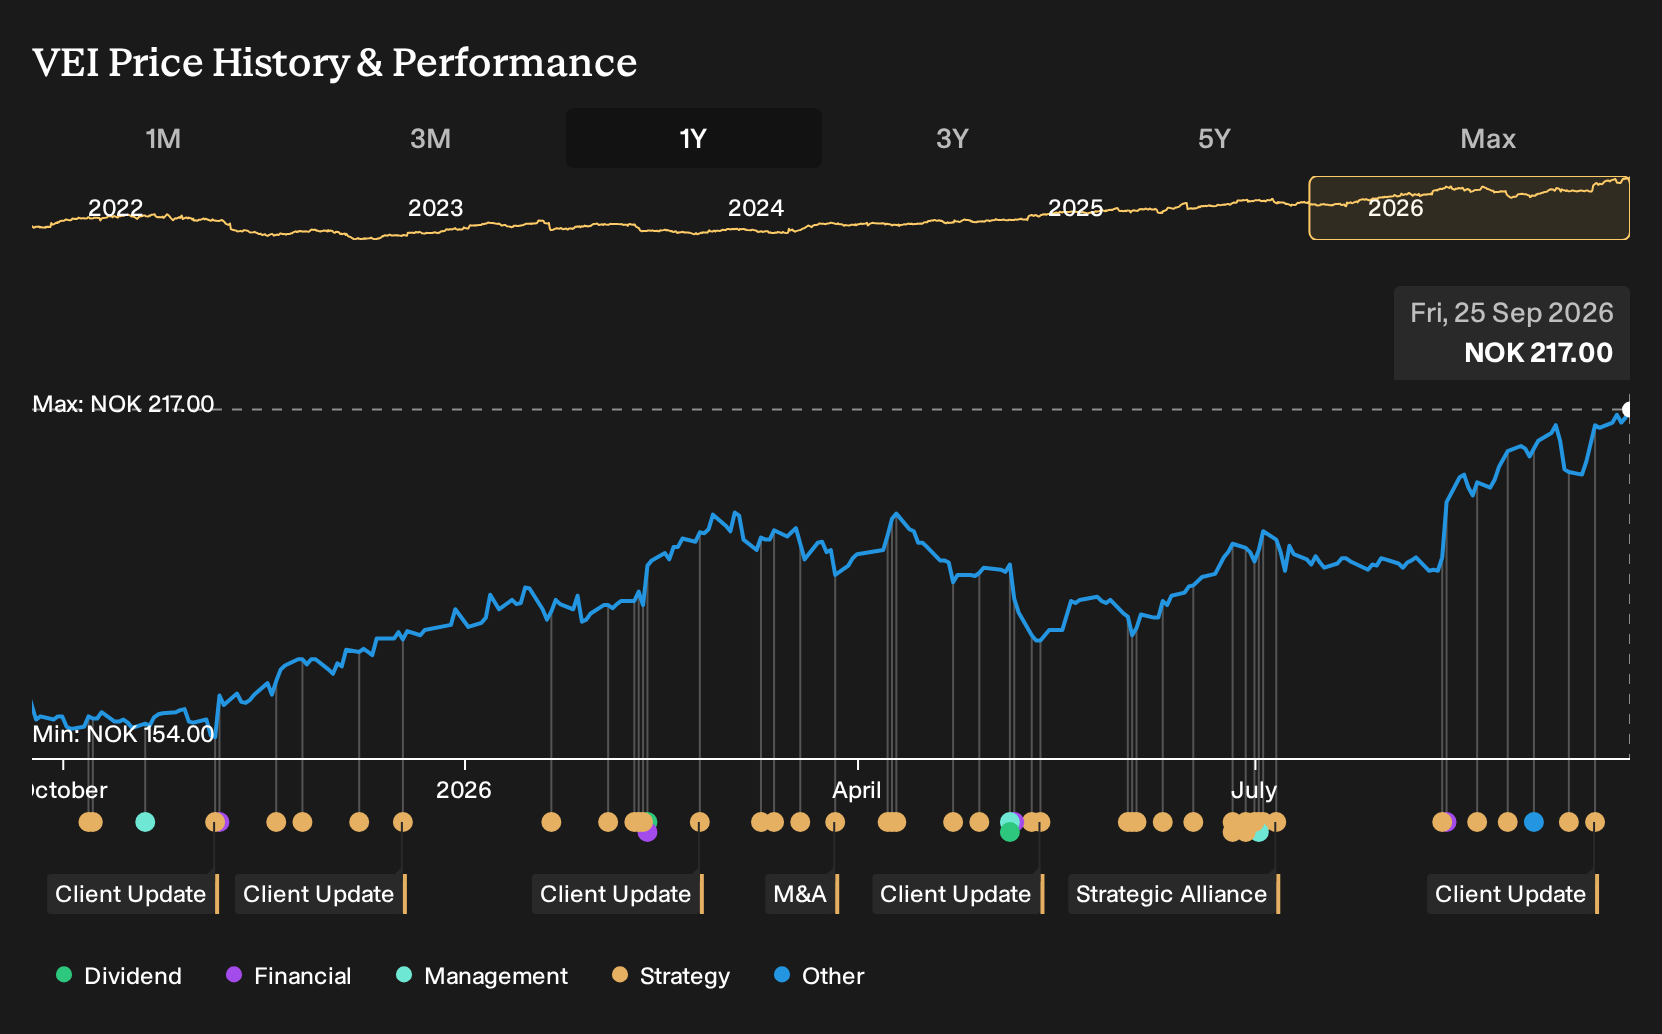
To back Veidekke, you need to be comfortable with a construction group where the story lives in execution quality, order intake and disciplined use of capital rather than big headline swings. The Bryggebyen and Cederhuset design and build contracts fit that logic. They extend visibility on residential activity into 2028 and reinforce the impression that clients still want Veidekke to take full project responsibility. In the near term, the main operational question is less about these two jobs individually and more about whether similar work keeps replenishing the order book.
Short term catalysts relate to how effectively the business converts its recent earnings and revenue progress into cash, while managing a capital intensive project pipeline and a dividend that is not well covered by profits. A P/E of 17.4x, above both fair value and industry reference points, indicates that expectations are not low. The new Scandinavian housing contracts add support to the demand story but do not remove the need for tight project selection and cost control.
Even so, there is a less comfortable angle to the Veidekke thesis that only really comes into focus once you look at ...
There's only one way to know the right time to buy, sell or hold Veidekke. Head to Simply Wall St's company report for the latest analysis of Veidekke's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster tightly between NOK 210 and about NOK 228.65 per share. This still leaves plenty of room for disagreement on Veidekke once you factor in the fresh Bryggebyen and Cederhuset contracts. Treat this as a prompt to compare several community viewpoints before deciding how you see the company.
Explore another Veidekke fair value estimate, including one that suggests it could be worth just NOK210.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Veidekke research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Veidekke. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veidekke's overall financial health at a glance.
Looking For More Investment Ideas Beyond Veidekke?
If Veidekke has sharpened your interest in construction and infrastructure, it can be useful to widen the field and benchmark it against other businesses with different balance sheet strength, risk profiles and income characteristics. The Simply Wall St Screener lets you do that quickly by filtering for traits that matter most to your approach.
- For investors who want income with fewer balance sheet surprises, consider companies screened for resilience and payout potential through 160 dividend fortresses.
- If capital preservation and steadier risk scores are a priority, compare Veidekke with businesses surfaced via 226 resilient stocks with low risk scores.
- When you want to see which other stocks combine solid finances with less market attention, scan for opportunities using 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com