
Is Daiichi Sankyo Company (TSE:4568) Undervalued On Its FDA Filing Withdrawal?
Daiichi Sankyo Company (TSE:4568) moved back into focus after it and Merck voluntarily withdrew their U.S. accelerated approval filing for ifinatamab deruxtecan in extensive-stage small cell lung cancer.
At a share price of ¥2,929.0, Daiichi Sankyo Company has seen a 12.05% 90 day share price return, while the year to date share price return is down 17.03%, and the 1 year total shareholder return has declined 10.26%. This suggests that momentum has cooled despite recent dividend news and ongoing trial activity around ifinatamab deruxtecan.
Capitalize on the renewed focus on Daiichi Sankyo Company by scanning a handpicked set of pharma and biotech opportunities starting with 74 high quality undiscovered gems.Daiichi Sankyo Company now trades at a steep discount to both analyst targets and intrinsic value estimates. Does that gap reflect cautious pricing after the ifinatamab setback, or an opportunity the market is misreading ahead of any valuation work?
Most Popular Narrative: 29% Undervalued
Daiichi Sankyo Company’s most followed valuation narrative points to a fair value of ¥4,146, which sits well above the latest close at ¥2,929. That gap puts the spotlight on how much of the oncology story and guidance reset is already baked into the current share price.
Pipeline depth in antibody-drug conjugates (ADCs) supported by ongoing R&D investment and multiple upcoming pivotal data readouts and regulatory submissions (e.g., for breast, gastric, lung, and gynecological cancers) positions the company to capture higher-margin opportunities as precision medicine gains traction, which could further boost future net margins and earnings.
See why 8 investors see Daiichi Sankyo Company as 29% undervalued.
The prevailing thesis uses a ¥4,146 fair value estimate and a 4.91% discount rate, with expectations for revenue of ¥2.64b and earnings of ¥330.7b by 2029 underpinning that view. The roughly 29% discount to this narrative fair value, alongside Daiichi Sankyo Company’s 7.4% forecast annual revenue growth and 12.6% expected earnings growth, frames the current price as a debate about execution on a concentrated oncology portfolio rather than a simple reaction to the ifinatamab deruxtecan news.
Result: Fair Value of ¥4,146 (UNDERVALUED)
Still, the bullish case for Daiichi Sankyo Company hinges on a narrow set of oncology blockbusters and assumes no major regulatory or pricing setbacks that could quickly challenge this position.
Find out about the key risks to this Daiichi Sankyo Company narrative.
Another View: What Daiichi Sankyo Company’s P/E Is Telling You
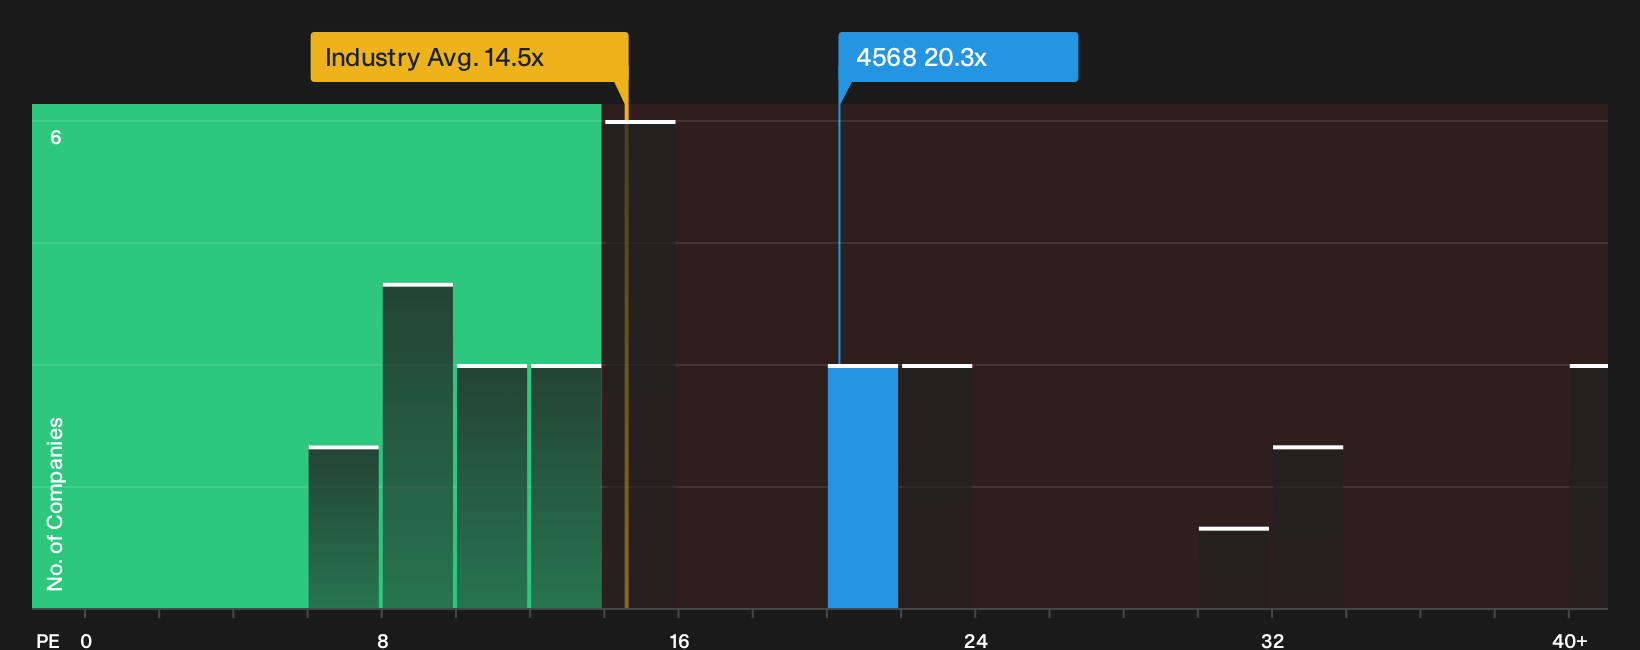
The story looks less straightforward once you switch from fair value estimates to the current P/E. Daiichi Sankyo Company trades on 20.3x earnings, which is richer than both the JP Pharmaceuticals average of 14.5x and its own fair ratio of 33.1x that our model suggests the market could move toward over time. That mix points to a stock that already carries a premium tag versus peers, yet still screens as cheap against its fair ratio. This leaves you to decide whether this signals valuation risk if sentiment cools or headroom if the market leans into the oncology story.
To dig into how this P/E premium, peer gap, and fair ratio fit together in practice, and what that might mean for future upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Daiichi Sankyo Company so far. If you want to move fast and build your own conviction, start by weighing its 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Daiichi Sankyo Company?
If Daiichi Sankyo Company has sharpened your focus on pricing, pipelines, and risk, you can keep that momentum going by widening your watchlist with data driven stock ideas.
- Explore potential opportunities in mispriced businesses by scanning a curated set of quality candidates through 19 high quality undervalued stocks.
- Support your portfolio’s foundation by reviewing companies with robust finances using the list of solid balance sheet and fundamentals (22 results).
- Limit portfolio shocks by focusing on steadier performers with 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com