
Ball (BALL) Could Be 22% Undervalued Following Its Recent Pullback
Ball (BALL) has drawn investor attention after recent trading left the share price at $56.83, with mixed short term moves and a positive longer term total return profile shaping sentiment around the packaging group.
Recent trading has cooled, with the 7 day share price return down 5.52% and the 30 day share price return down 10.88%. However, Ball still shows a year to date share price gain of 6.52% and a 1 year total shareholder return of 16.46%, pointing to momentum that has softened in the short term but remains positive over a longer window.
Contrast Ball's mixed recent swings with other packaging and materials stocks by scanning our hand picked list of solid balance sheet and fundamentals (24 results) for potential ideas to research next.
Ball now trades well below some valuation estimates after a sharp pullback, which leaves a simple question hanging. Has most of the easy upside already been taken, or is the stronger return potential still ahead from here?
Most Popular Narrative: 22% Undervalued
At a last close of $56.83, the most followed narrative pegs Ball's fair value near $72.57. This frames the recent pullback as a sizeable discount that rests on specific growth and margin assumptions rather than sentiment alone.
The shift in consumer behavior toward ready-to-drink beverages and energy drinks is supporting ongoing volume expansion, particularly across North America and EMEA, positioning Ball to grow at or ahead of market rates, favorably impacting top-line revenue and capacity utilization rates. Tight industry supply and new capacity investments (e.g., new Northwest facility, asset acquisition in Florida) are aligning Ball to capture incremental share in high-growth regions while enhancing geographic footprint, underpinning long-term revenue growth and improved fixed-cost absorption.
See why 9 investors see Ball as 22% undervalued.
Result: Fair Value of $72.57 (UNDERVALUED)
Still, that upside story for Ball can unravel quickly if input costs stay volatile or if key customers in regions like South America pull back or push for tougher terms.
Find out about the key risks to this Ball narrative.
Another View on Ball's Valuation
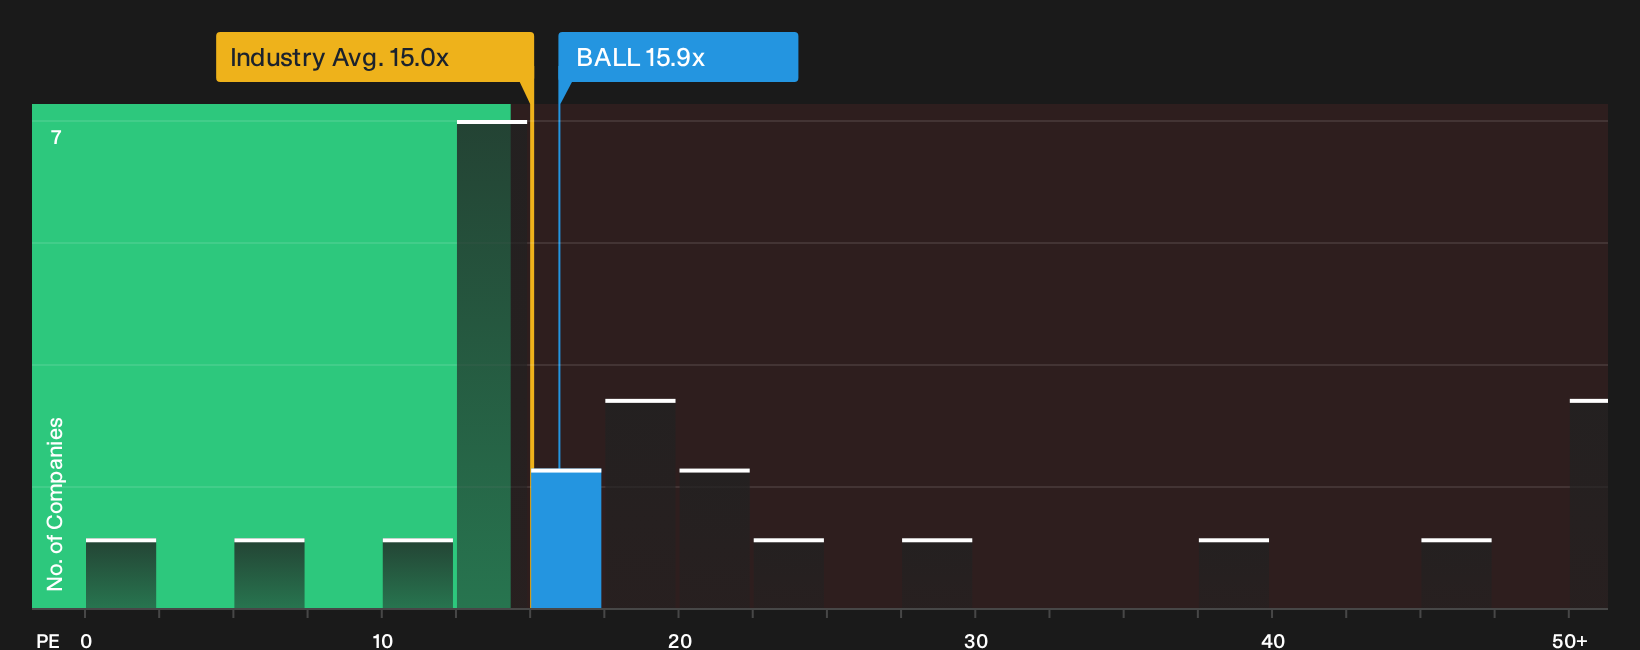
The fair value work around $72.57 presents Ball as underpriced, but the market is telling a more cautious story. At a P/E of 15.9x, the stock trades slightly richer than the global packaging group on 15x, yet below a fair ratio of 20.1x that the market could move toward. That mix points to some valuation support, but also to the risk that investors are already paying a premium for quality in a slower growth profile.
See what the numbers indicate about this price in our valuation breakdown, and how it compares with peers and that fair ratio view, by going through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Ball's recent pullback and valuation story are only a starting point, so move quickly, stress test the data yourself and weigh both sides of the argument by checking the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ball?
Do not stop your research with Ball. Use the Simply Wall Street Screener to quickly surface other stocks that might fit your return goals and risk comfort.
- Target stronger downside resilience by scanning companies that show consistent balance sheet strength through the 30 resilient stocks with low risk scores.
- Hunt for potential mispricing by reviewing a curated pool of quality companies trading below their estimated worth in the 32 high quality undervalued stocks.
- Stack your watchlist with underfollowed opportunities that pair fundamentals with quieter coverage using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com