
Is Natural Resource Partners (NRP) Cheap Or Fully Valued At $108.78?
Natural Resource Partners (NRP) has drawn fresh attention after its units closed at US$108.78, with recent returns ranging from a decline over the past month to a gain over the past 3 months.
Over a longer stretch, Natural Resource Partners has combined a softer 30-day share price return of 3.5% with a stronger 90-day share price gain of 9.3%. At the same time, the 1-year total shareholder return of 7.6% and very large 5-year total shareholder return signal momentum that has built over time rather than faded.
Scan beyond Natural Resource Partners and compare its long-run returns with a curated group of income and quality names using the 8 dividend fortresses.
Natural Resource Partners has already rewarded patient holders, which leaves new buyers weighing a quick entry against waiting for a cheaper pullback. The answer sits in the current valuation workup that follows.
Price-to-Earnings of 13.8x: Is it justified?
Natural Resource Partners currently trades on a P/E of 13.8x, while the last close sits at $108.78 and the valuation signals point in different directions when you compare peers, intrinsic value and recent earnings trends.
The P/E ratio links the partnership’s unit price to its earnings, so a higher figure usually means holders are paying more today for each dollar of profit. For a mineral rights and soda ash royalty business like Natural Resource Partners, that matters because earnings are tied to commodity-linked contracts and royalty streams rather than straightforward volume growth.
On one side, Natural Resource Partners is described as good value when set against a peer average P/E of 33.7x, which suggests the market is not paying the same premium for its earnings as it is for comparable stocks. At the same time, the units are trading about 48.1% below an internal fair value estimate based on the SWS DCF model, which pegs future cash flow value at $209.41 per unit. Those signals both point to a market price that does not fully reflect the cash flows implied by the current royalty base.
The picture is more mixed when you line that 13.8x P/E up against the broader US Oil and Gas industry, where the average sits at 12.7x. That premium suggests investors are paying slightly more than the sector average even though reported earnings fell 26.1% over the past year and return on equity of 16.4% is described as low. The combination of lower recent profit growth and a P/E above the industry average means the valuation leans on future cash flow strength and the quality of past earnings rather than recent momentum.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 13.8x (ABOUT RIGHT)
Still, the thesis around Natural Resource Partners can be knocked off course if commodity royalty volumes disappoint or if unit prices move well away from cash flow support.
Find out about the key risks to this Natural Resource Partners narrative.
Another View on Natural Resource Partners’ Value
There is a second lens here. Natural Resource Partners screens as good value on simple P/E comparisons, yet our DCF model points to the units trading about 48.1% below an estimated future cash flow value of $209.41 per unit. Which signal carries more weight for you as a holder or prospective buyer?
Look into how the SWS DCF model arrives at its fair value.
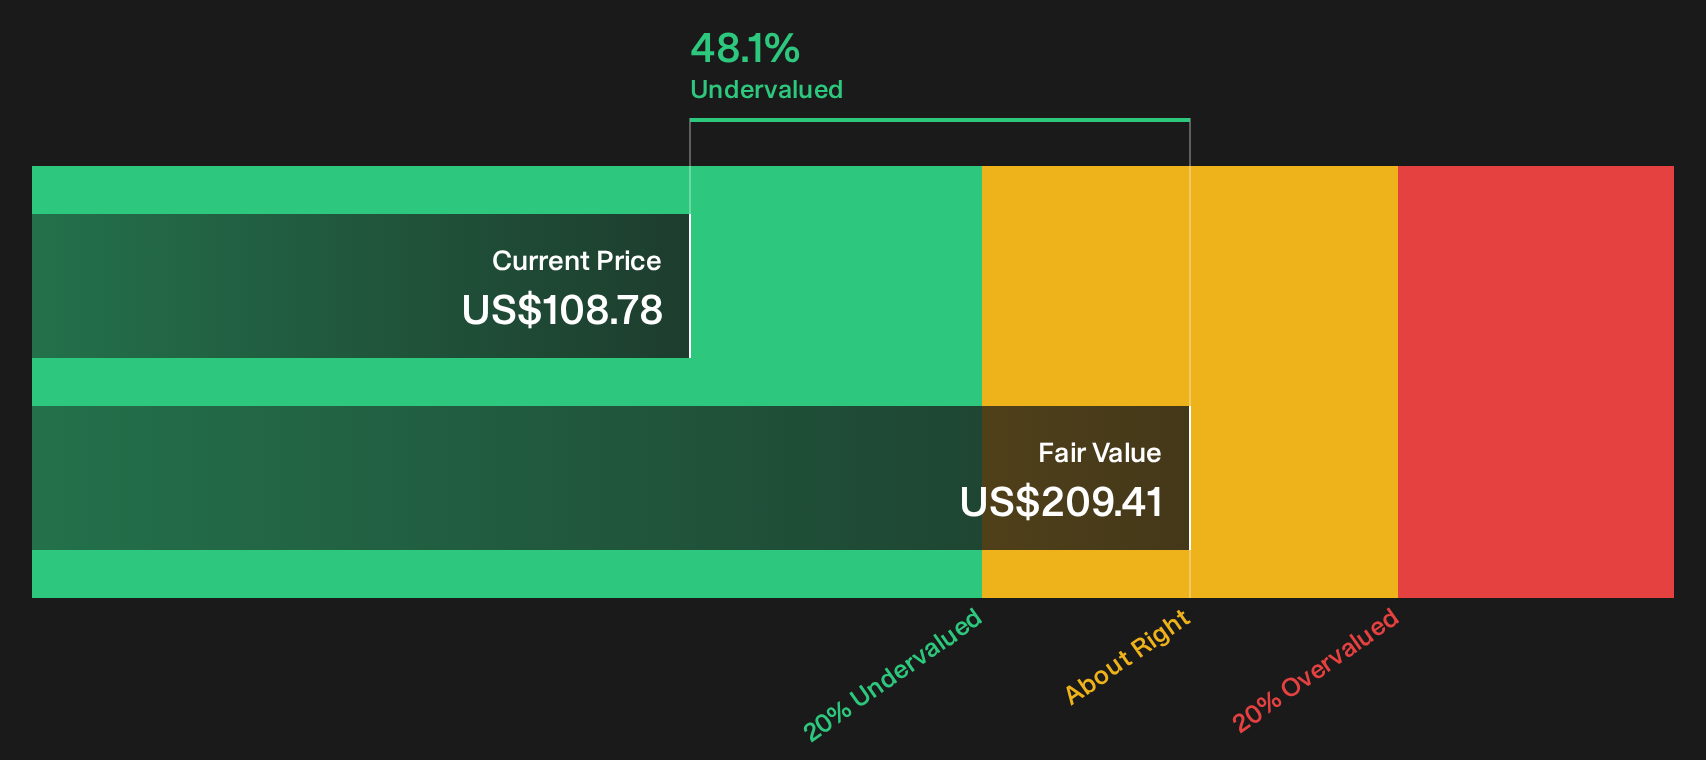
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Natural Resource Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There are mixed signals on Natural Resource Partners so far. Act while the data is fresh and stress test the story yourself by weighing its 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Natural Resource Partners?
Do not stop with Natural Resource Partners. Use the Simply Wall Street Screener to surface fresh opportunities that fit your style before the next move gets away.
- Target resilient balance sheets and steady fundamentals through a curated list of solid balance sheet and fundamentals (24 results) that can help you focus on financial strength first.
- Spot potential mispricings early by scanning a 32 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Zero in on stability and defensiveness with a 30 resilient stocks with low risk scores that highlights companies scoring well on risk factors that matter to long term holders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com