
Broadcom And 2 Top Undervalued Stocks
The Federal Reserve’s latest 25 basis point rate hike to 3.75% to 4% has pushed borrowing costs higher just as growth and earnings feel more uncertain. That mix often punishes weaker balance sheets and rewards investors who quietly collect solid cash flows at sensible prices. This article walks through three high quality, potentially mispriced US stocks that combine financial strength with value appeal.
The three examples covered below are only a sample set, as the full screen on Simply Wall St surfaced 29 more high quality undervalued companies with equally compelling narratives that are not included here. To identify and analyze those additional ideas in detail, head straight into the High Quality Undervalued Stocks screener
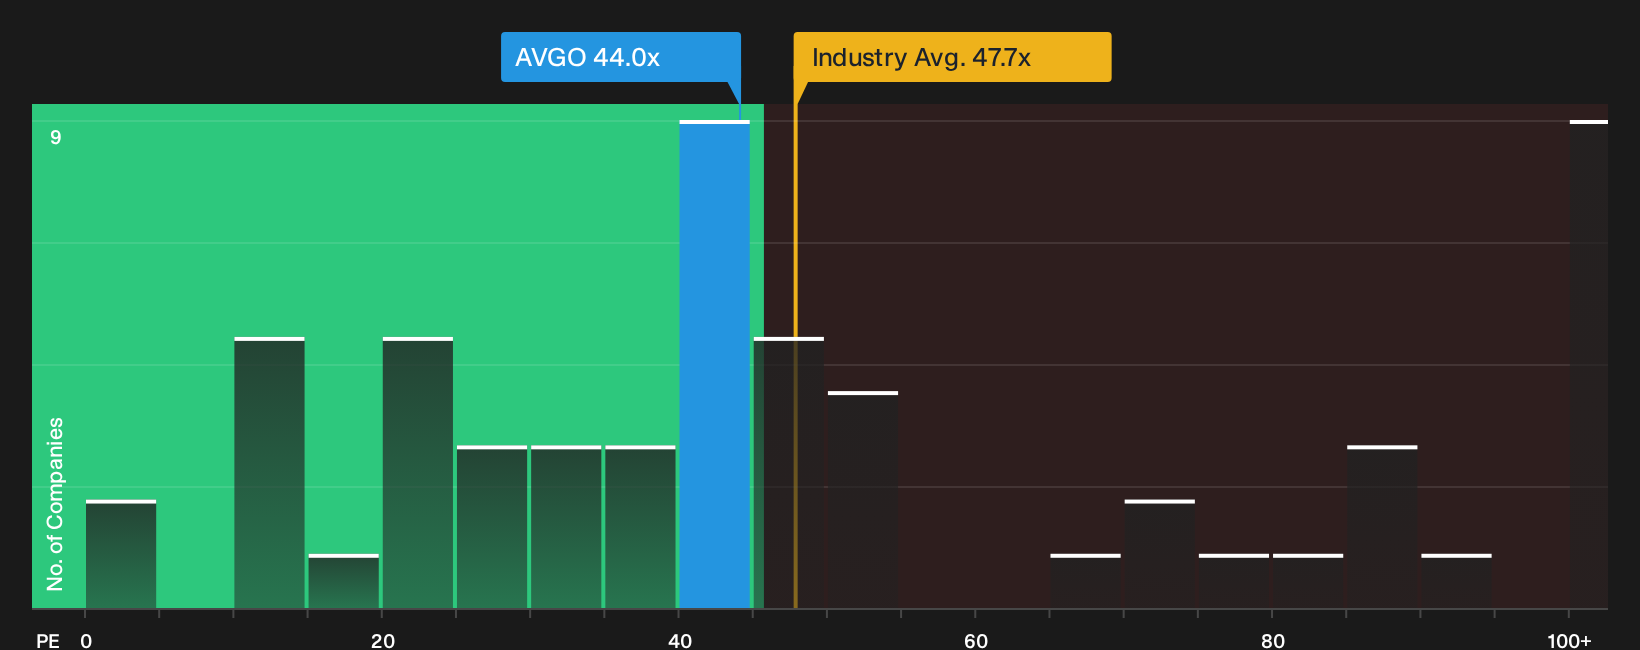
Broadcom (AVGO)
Overview: Broadcom is a global digital infrastructure supplier, providing data center networking chips, storage controllers, and infrastructure software that power AI and enterprise computing.
Operations: Broadcom generates about US$59.4b from Semiconductor Solutions, including IP licensing, and around US$29.7b from Infrastructure Software.
Market Cap: US$1.68t
Broadcom matters for this High Quality Undervalued Stocks screen because its data center semiconductors and infrastructure software turn AI demand into large recurring cash flows.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
The key variable is how one evolving pattern in AI infrastructure spending shapes Broadcom’s ability to continue monetizing its technology edge.
That hinges on how quickly that demand pattern shifts into Broadcom’s next phase of monetization. The full narrative for Broadcom unpacks this with scenarios, pressure points, and overlooked upside.
Coherent (COHR)
Overview: Coherent supplies high volume photonics gear for AI datacenters and communications networks, alongside industrial lasers and engineered materials.
Operations: Coherent generates about US$5.3b from Datacenter & Communications and roughly US$1.9b from Industrial, with most revenue coming from North America.
Market Cap: US$57.9b
Coherent matters for this High Quality Undervalued Stocks screen because its datacenter and communications photonics can turn AI bandwidth demand into substantial cash generation, while the wider industrial laser franchise adds diversification.
"The ongoing expansion of AI datacenter infrastructure and high-performance computing is propelling structural growth in demand for advanced optical transceivers (800G, 1.6T, and beyond), optical circuit switches, and related photonics components. This is fueling robust sequential order growth and sustained revenue momentum in Coherent's datacom and communications business."
What investors will keep coming back to is how a single shift in high value product mix could ripple through margins and free cash flow.
That shift is where the real torque sits, and the full narrative for Coherent explains how Coherent’s mix, pricing power, and capital needs could be quietly decoupling from headline demand cycles.

Oracle (ORCL)
Overview: Oracle provides cloud software, databases, and infrastructure that help large organisations run finance, HR, operations, and data workloads globally.
Operations: Oracle generates about US$62.8b from Cloud and software, US$5.8b from Services, and US$3.2b from Hardware.
Market Cap: US$415.6b
Oracle matters for this High Quality Undervalued Stocks screen because its Fusion Cloud applications and Oracle Cloud Infrastructure bundle subscription contracts, data workloads, and AI services into recurring cash flows backed by a sizeable installed base.
"OpenAI began leveraging OCI Superclusters, which are capable of scaling up to 32,768 Nvidia GPUs per cluster."
The key consideration is how a sustained shift in AI driven contract demand may affect free cash flow and long term margins.
That contract shift is where Oracle’s story can really accelerate, and the full narrative for Oracle maps how AI demand, capital intensity, and cash generation could quietly reshape the whole business.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities move first, then the crowd notices. Use this moment while it matters, before the best entries get caught in momentum. Get in early.
- Hunt for early-stage momentum where balance sheets still look robust by scanning the curated 16 high quality undiscovered gems that analysts are only starting to talk about.
- Target dependable income streams before yields start dropping by reviewing a focused 8 dividend fortresses that highlights businesses built around consistent cash returns.
- Position for structural shifts in energy and infrastructure by tracking a refined 19 nuclear energy infrastructure stocks that flags potential long term beneficiaries of the nuclear build out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com