
Alphabet (GOOGL) Pushes Deeper Into AI Following Gemini 4 As Valuation Debate Builds
Alphabet (GOOGL) has pushed deeper into AI this month, lining up the Gemini 4 model, an early Project Suncatcher satellite launch, and a fresh Experian integration inside Gemini’s consumer finance experience.
Alphabet’s recent AI announcements land against a backdrop of mixed near term trading and powerful longer term wealth creation. The share price is up 9.1% year to date and the stock’s 1 year total shareholder return of 39.9% and 3 year total shareholder return of about 2.7x suggest the bigger trend has been strong, even as the 90 day share price return declined 2.8% while investors weigh fresh AI spending, regulatory fines and new partnerships, such as Experian’s Gemini integration, against those gains.
Scan how Alphabet’s AI push compares with other potential breakouts in the sector by reviewing our hand picked list of 85 AI infrastructure stocks.
Alphabet now appears to be caught between fresh AI bets and a share price that has already moved significantly. Do you lean into the current valuation, or sit tight and wait for a cheaper entry point?
Most Popular Narrative: 70% Overvalued
Alphabet last closed at $343.92, while the most followed narrative pegs fair value at $202.62, which points to a wide gap between enthusiasm in the market and the underlying valuation work that has been done according to tripledub.
The arithmetic of waiting, which is where this gets uncomfortable. Suppose the middle road is roughly right and you buy today anyway. What do you actually collect? On the middle road the shares are worth $272.54 in three years, $313.86 in five, and $395.49 in ten. Against $356.13 today, that is down about twenty four percent, down about twelve percent, and finally up about eleven percent. Read the last column again. Eleven percent in total after a decade. Call it one percent a year, for owning what may well be the best business of this generation, through ten years of headlines and lawsuits and product cycles.
See why 232 investors see Alphabet as 70% overvalued.
Result: Fair Value of $202.62 (OVERVALUED)
Still, this narrative could crack if Alphabet's heavy AI capital spending earns weaker returns than expected, or if regulatory penalties materially reshape its dominant search and ads model.
Find out about the key risks to this Alphabet narrative.
Another View on Alphabet’s Valuation
Tripledub’s fair value work frames Alphabet as roughly 70% overvalued at $343.92, yet the SWS DCF model comes out in a very different place. On that methodology, the stock trades about 29.1% below an estimated future cash flow value of $485.36, which points to upside instead of downside risk.
The gap between those two approaches raises a practical question for you. Which feels more realistic: a cautious narrative that leans on demanding return assumptions, or a cash flow model that says the current price already bakes in a margin of safety, at least on those inputs?
Look into how the SWS DCF model arrives at its fair value.
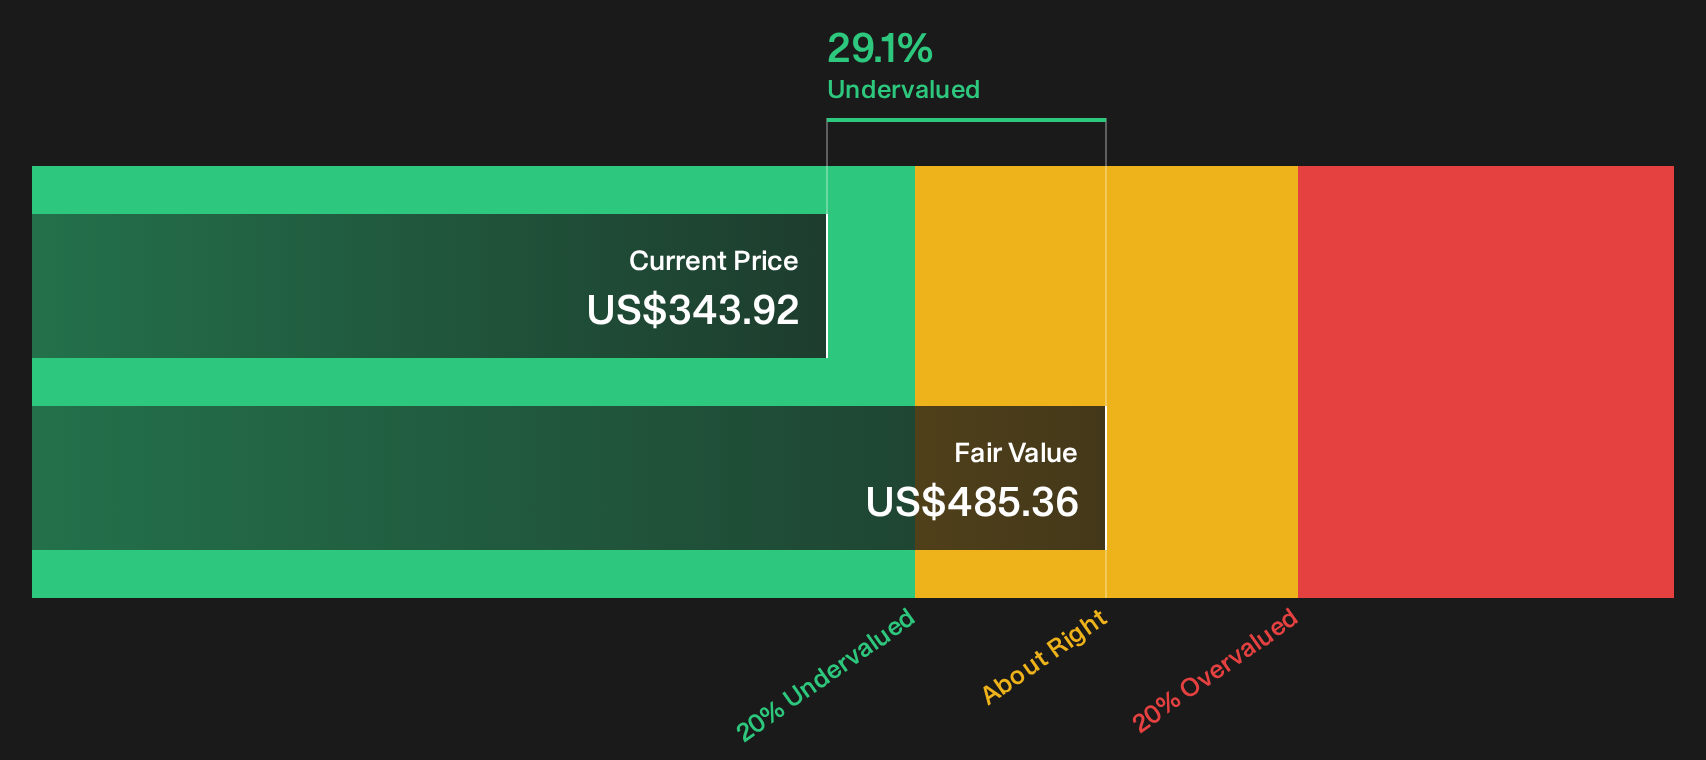
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alphabet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Alphabet's valuation can feel uncomfortable, so move quickly, review the full data set, and then judge the balance of 4 key rewards and 2 important warning signs.
Looking for more Alphabet investment ideas?
If Alphabet now feels fully priced to you, broaden your watchlist with fresh opportunities that match your style before the next wave of money moves first.
- Target strong upside potential in smaller companies by scanning the 6 elite penny stocks with strong financials that clear tough financial quality checks.
- Find value focused ideas by reviewing the 32 high quality undervalued stocks that combine solid cash flows with disciplined balance sheets.
- Prioritise resilience and capital preservation by filtering for the 30 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com