
What Is Behind BorgWarner (BWA) Stock's Latest Move?
BorgWarner (BWA) is back in focus after a recent move in its share price, with the stock closing at US$61.32. Investors are weighing that action against solid year-to-date and 1 year total returns.
The latest 1-day share price return of 4.86% comes after a softer patch, with the stock down 4.32% over 30 days and 6.94% over 90 days. However, BorgWarner still carries strong momentum when viewed against its 31.48% year to date share price return and 40.91% 1-year total shareholder return.
Scan how BorgWarner’s move compares with other auto suppliers showing similar price action by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results) in this corner of the market.
Bulls point to BorgWarner’s strong recent total returns and valuation discount, while bears focus on softer near term price action. Which side does the current pricing actually support as you look at what you are paying for the business?
Most Popular Narrative: 23% Undervalued
BorgWarner’s most followed thesis puts fair value at $79.93 per share, comfortably above the recent $61.32 close. This frames the current pullback as a potential valuation gap rather than a broken story.
Expansion into data center power through the turbine generator program, supported by a 2 GW plant in North Carolina and expected revenue of about US$300 million in 2027 at mid teens incremental margins, adds a new earnings stream that is not fully tied to light vehicle cycles and could support operating margin and EPS resilience.
See why 23 investors see BorgWarner as 23% undervalued.
Result: Fair Value of $79.93 (UNDERVALUED)
Still, BorgWarner’s reliance on combustion products and the drag from its restructuring battery activities could both work against that upside story if conditions change.
Find out about the key risks to this BorgWarner narrative.
Another View on BorgWarner’s Valuation
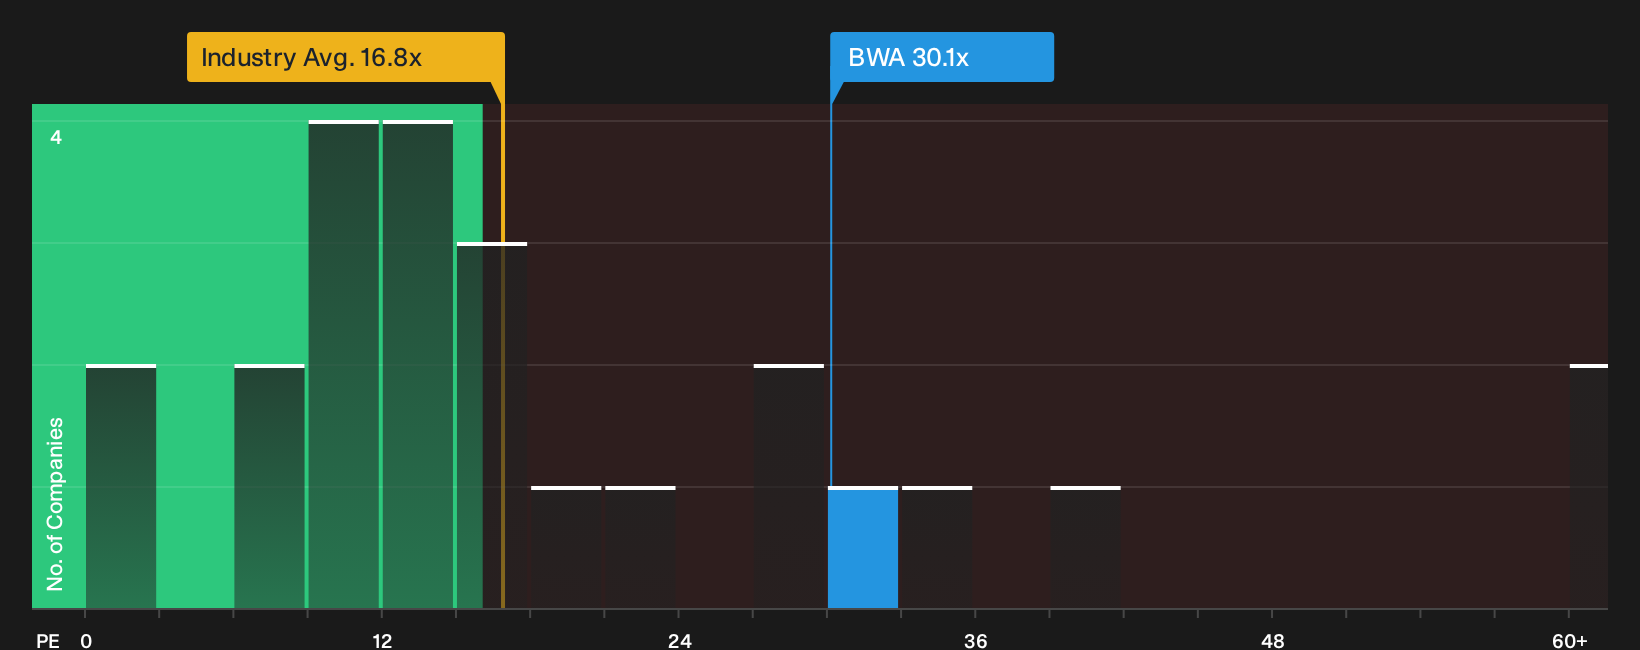
The first argument for BorgWarner being undervalued leans heavily on a fair value of $79.93 per share. A simple P/E check paints a rougher picture. The stock trades on about 30.1x earnings, compared with 16.8x for the US Auto Components group and a fair ratio estimate of 19.9x. That gap points to richer pricing on current earnings, which raises a practical question for you: Is this a margin of safety, or are you paying up today for forecasts that still need to play out?
See what the numbers say about this price in our valuation breakdown, then compare it with peers to stress test your own view of BorgWarner’s upside and downside See what the numbers say about this price — find out in our valuation breakdown.
Put the current multiple into context by reviewing how BorgWarner’s P/E stacks up against the wider sector and our fair ratio view in one place
Next Steps
Mixed signals around BorgWarner’s valuation and recent share moves make this a judgment call that sits with you, not the market. If you want a fuller picture before deciding how you feel about the balance of risk and reward here, start by weighing the 4 key rewards and 2 important warning signs.
Looking for more BorgWarner-like investment ideas?
Once you have a view on BorgWarner, do not stop there. Use the Simply Wall Street Screener to spot fresh opportunities before they move without you.
- Target resilience by focusing on businesses with sturdy finances and clear fundamentals through a curated list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by zeroing in on companies that combine strong fundamentals with appealing valuations using the 32 high quality undervalued stocks.
- Prioritise capital protection by concentrating on companies with steadier profiles and tempered risk scores via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com