
Is Oriental Land (TSE:4661) Still Undervalued Or Is Fantasy Springs Already Priced In?
Oriental Land (TSE:4661) has recently drawn investor attention after a period where the share price declined about 5% over the past month, even as the past 3 months show a gain.
Short term momentum for Oriental Land has cooled, with the share price down 4.7% over the past month and 4.6% over the last week. Even after a 16.3% gain on a 90 day share price return and a 1 year total shareholder return that is down 17.8%, this signals that investors have been reassessing both growth potential and risk for some time.
Scan how Oriental Land compares to other consumer-focused opportunities by reviewing the hand-picked 74 high quality undiscovered gems that may be slipping under the radar.
After that mix of recent gains and longer term declines, the question around Oriental Land now is simple: Is most of the opportunity already priced in, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 10.5% Undervalued
Against a last close of ¥2,896.5, the most followed narrative pegs Oriental Land’s fair value at ¥3,236, which frames the current pullback as a potential valuation gap rather than a clear verdict on the business.
The opening of Fantasy Springs and new attractions has increased guest attendance, which is expected to boost net sales and operating profit through higher theme park revenues. Merchandise and food and beverage sales are projected to grow due to new product offerings and the opening of new restaurants in Fantasy Springs, positively impacting net sales per guest and overall revenue.
See why 1 investors see Oriental Land as 11% undervalued.
The narrative is based on a 6.6% revenue growth assumption, a 17.5% profit margin and a 41.9x future P/E multiple. These are all discounted at 6.58% to arrive at the ¥3,236 figure. Any personal view on Oriental Land’s upside therefore depends on how comfortable you are with those inputs and the execution risks around new attractions, pricing and cost inflation.
Result: Fair Value of ¥3,236 (UNDERVALUED)
Still, the bullish Oriental Land story can quickly soften if higher personnel and raw material costs squeeze margins or if weather and event timing weaken guest attendance.
Find out about the key risks to this Oriental Land narrative.
Another View On Oriental Land’s Valuation
The headline narrative presents Oriental Land as about 10.5% undervalued relative to a ¥3,236 fair value. Yet on simple earnings yardsticks, the picture looks very different.
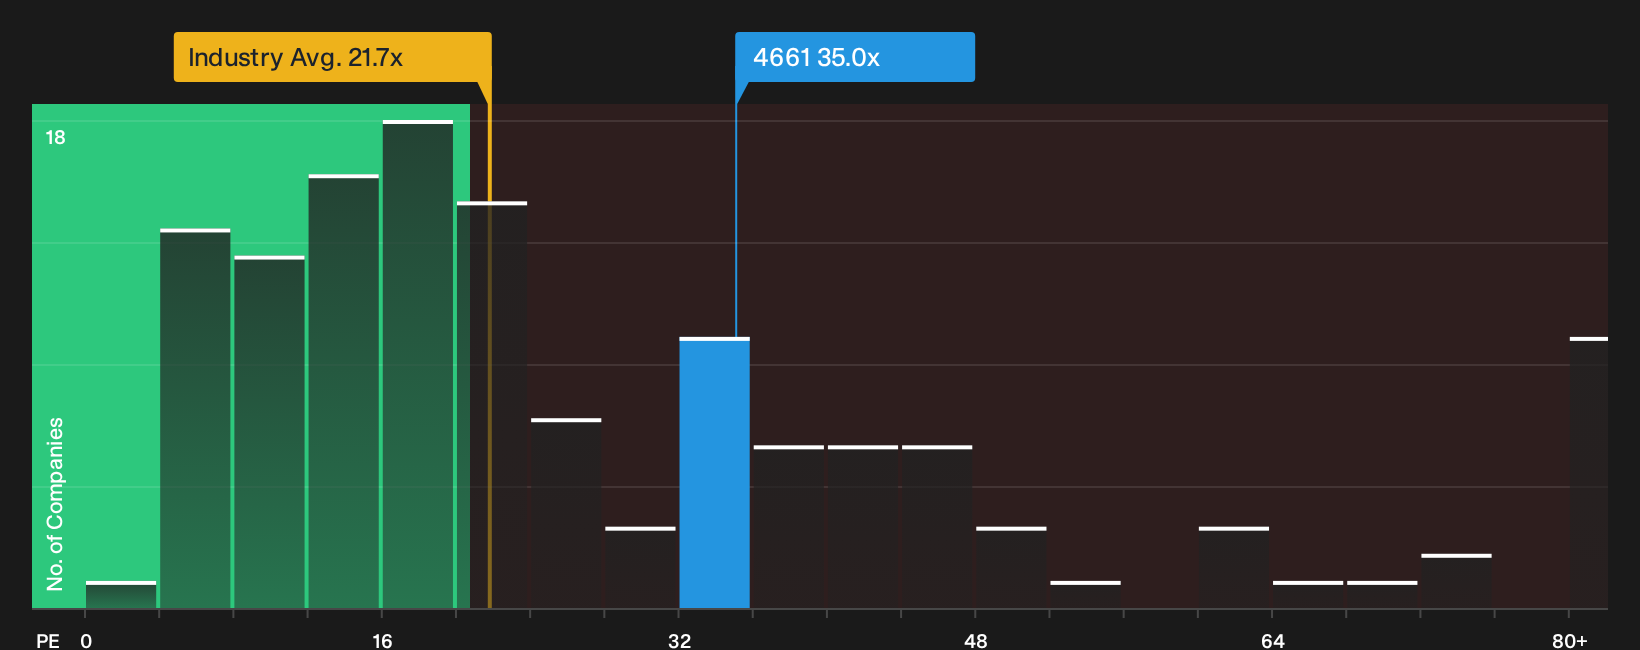
The stock trades on a P/E of 35x. The estimated fair ratio is 28.7x. The JP Hospitality industry sits around 21.7x and close peers average 18.6x. That is a sizeable premium which suggests meaningful valuation risk if expectations fade, rather than a straightforward bargain.
If earnings growth only tracks the current forecasts and sentiment cools, the share price could drift toward that lower fair ratio instead of the optimistic narrative target.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Oriental Land is clearly mixed, so it helps to move quickly, test the assumptions, and pressure check the positives that have investors interested in the first place. To see what optimistic holders are focused on, review the 2 key rewards.
Looking for more investment ideas beyond Oriental Land?
Do not stop your research with Oriental Land. Fresh opportunities often sit just outside your watchlist, and a few minutes of smart screening can surface very different risk reward profiles.
- Target potential mispricings by checking companies that feature in the 17 high quality undervalued stocks and see which ones match your preferred fundamentals and risk tolerance.
- Prioritise resilience by scanning the list of solid balance sheet and fundamentals (22 results) and focus on businesses with financial structures that may better support tougher conditions.
- Secure potential cash income streams by reviewing the 16 dividend fortresses and compare yields, payout histories, and balance sheet support in one place.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com