
Companies Like Arovella Therapeutics (ASX:ALA) Are In A Position To Invest In Growth
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
So, the natural question for Arovella Therapeutics (ASX:ALA) shareholders is whether they should be concerned by its rate of cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
How Long Is Arovella Therapeutics' Cash Runway?
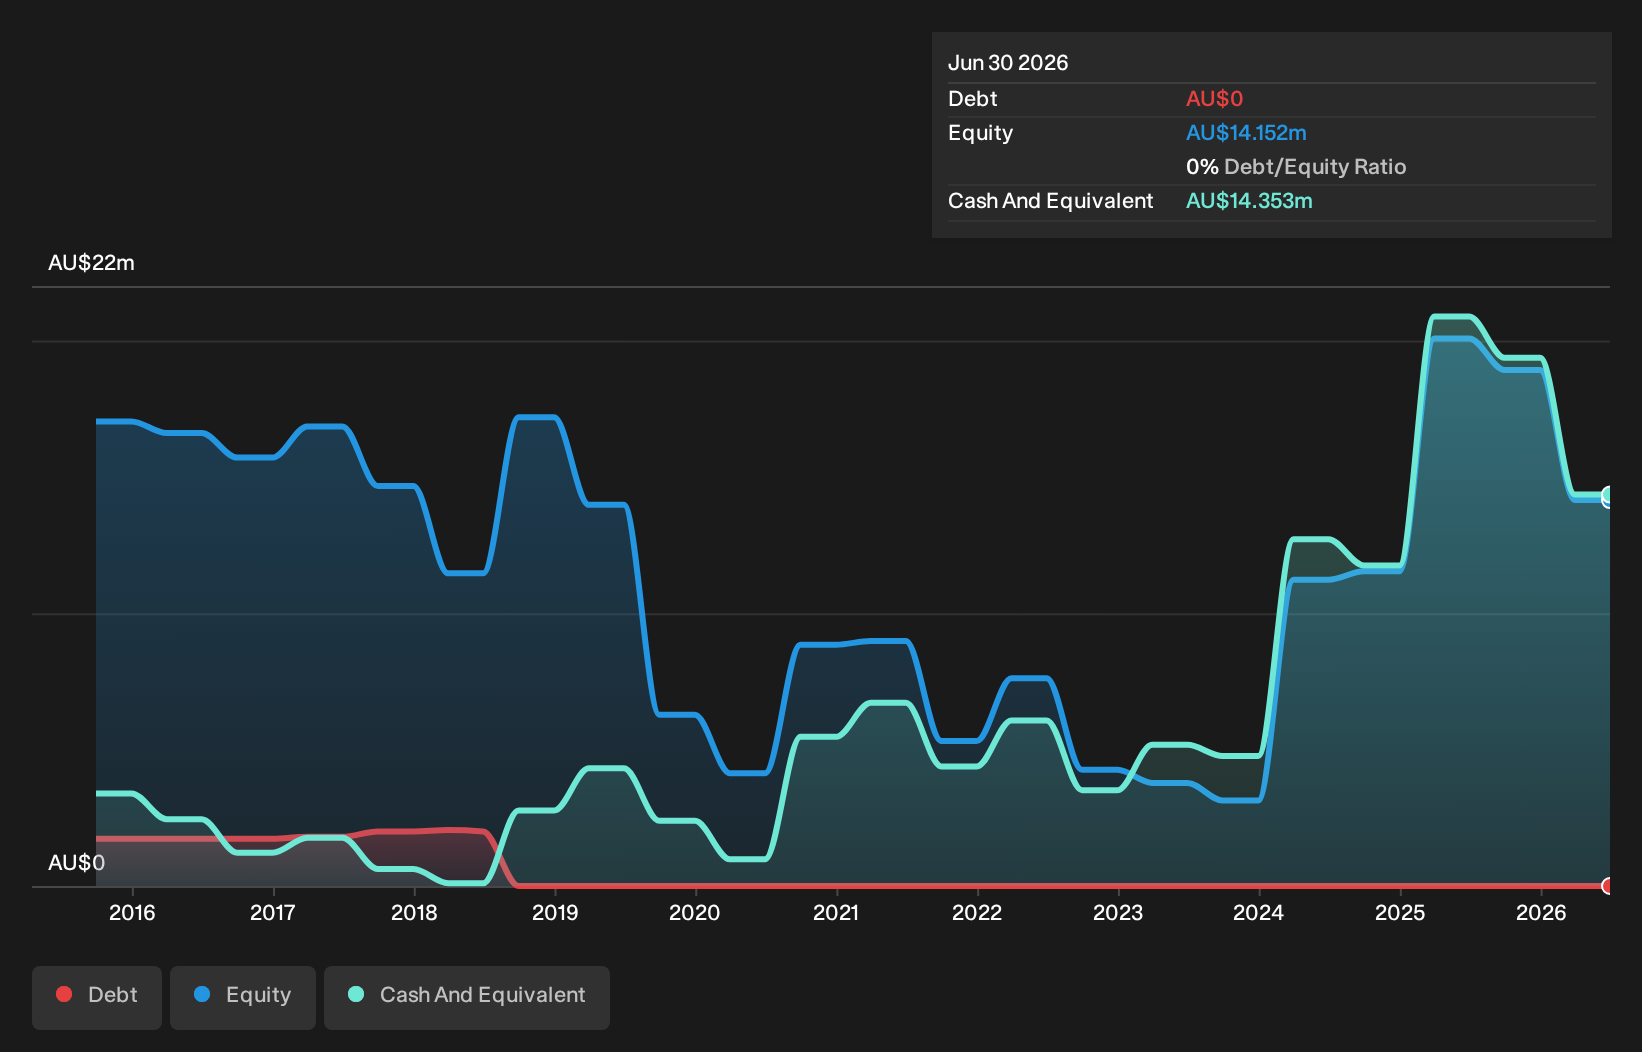
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. As at June 2026, Arovella Therapeutics had cash of AU$14m and no debt. Looking at the last year, the company burnt through AU$6.9m. Therefore, from June 2026 it had 2.1 years of cash runway. Arguably, that's a prudent and sensible length of runway to have. You can see how its cash balance has changed over time in the image below.
See our latest analysis for Arovella Therapeutics
How Is Arovella Therapeutics' Cash Burn Changing Over Time?
While Arovella Therapeutics did record statutory revenue of AU$3.5m over the last year, it didn't have any revenue from operations. To us, that makes it a pre-revenue company, so we'll look to its cash burn trajectory as an assessment of its cash burn situation. As it happens, the company's cash burn reduced by 5.4% over the last year, which suggests that management are maintaining a fairly steady rate of business development, albeit with a slight decrease in spending. Admittedly, we're a bit cautious of Arovella Therapeutics due to its lack of significant operating revenues. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
How Hard Would It Be For Arovella Therapeutics To Raise More Cash For Growth?
Even though it has reduced its cash burn recently, shareholders should still consider how easy it would be for Arovella Therapeutics to raise more cash in the future. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Arovella Therapeutics has a market capitalisation of AU$59m and burnt through AU$6.9m last year, which is 12% of the company's market value. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
How Risky Is Arovella Therapeutics' Cash Burn Situation?
The good news is that in our view Arovella Therapeutics' cash burn situation gives shareholders real reason for optimism. One the one hand we have its solid cash burn relative to its market cap, while on the other it can also boast very strong cash runway. Considering all the factors discussed in this article, we're not overly concerned about the company's cash burn, although we do think shareholders should keep an eye on how it develops. On another note, we conducted an in-depth investigation of the company, and identified 3 warning signs for Arovella Therapeutics (1 shouldn't be ignored!) that you should be aware of before investing here.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.