
3 British Founder Backed Stocks With Earnings Growth Over 13%
Global markets have been swinging as geopolitical risks and new regulations unsettle sectors that rely heavily on policy support. In that kind of uncertainty, many investors are looking for businesses where the founder still calls the shots and has personal capital on the line. This article walks through three founder-led UK stocks from our screener and explains why their long term mindset may appeal right now.
The three founder-led stocks in this article are just a sample, and the full screen surfaced 60 more companies with equally compelling stories that are not covered here. To go deeper into the data, identify your own favourites, and analyze founder-backed opportunities side by side, head straight into the Founder-Led Companies screener.
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks develops and sells premium mixer drinks under the Fever Tree brand, led by its co founder leadership that still shapes strategy and brand building today. The business has a market value of about £936 million.
Fevertree Drinks is a pure play on founder driven brand building, where the same leaders who created the Fever Tree mixers still influence how capital, partnerships and product decisions get made.
"The transformational long-term partnership with Molson Coors provides Fevertree with guaranteed royalty profits and significantly reduces U.S. working capital requirements, likely leading to improved earnings quality, consistent cash generation, and a stronger balance sheet over the coming years."
What matters next for Fevertree Drinks is how one quiet pressure on its profitability trajectory plays out over the coming years.
That quiet squeeze on profits is exactly what the full narrative for Fevertree Drinks unpacks, showing how Fevertree Drinks could see earnings quality and capital intensity decouple over time.

Computacenter (LSE:CCC)
Computacenter runs large scale IT services and outsourcing contracts for corporate and public sector clients, with founder era leadership continuity closely tied to long running managed services. The business reports about £12.1b from computer services and has a market value of roughly £5.7b.
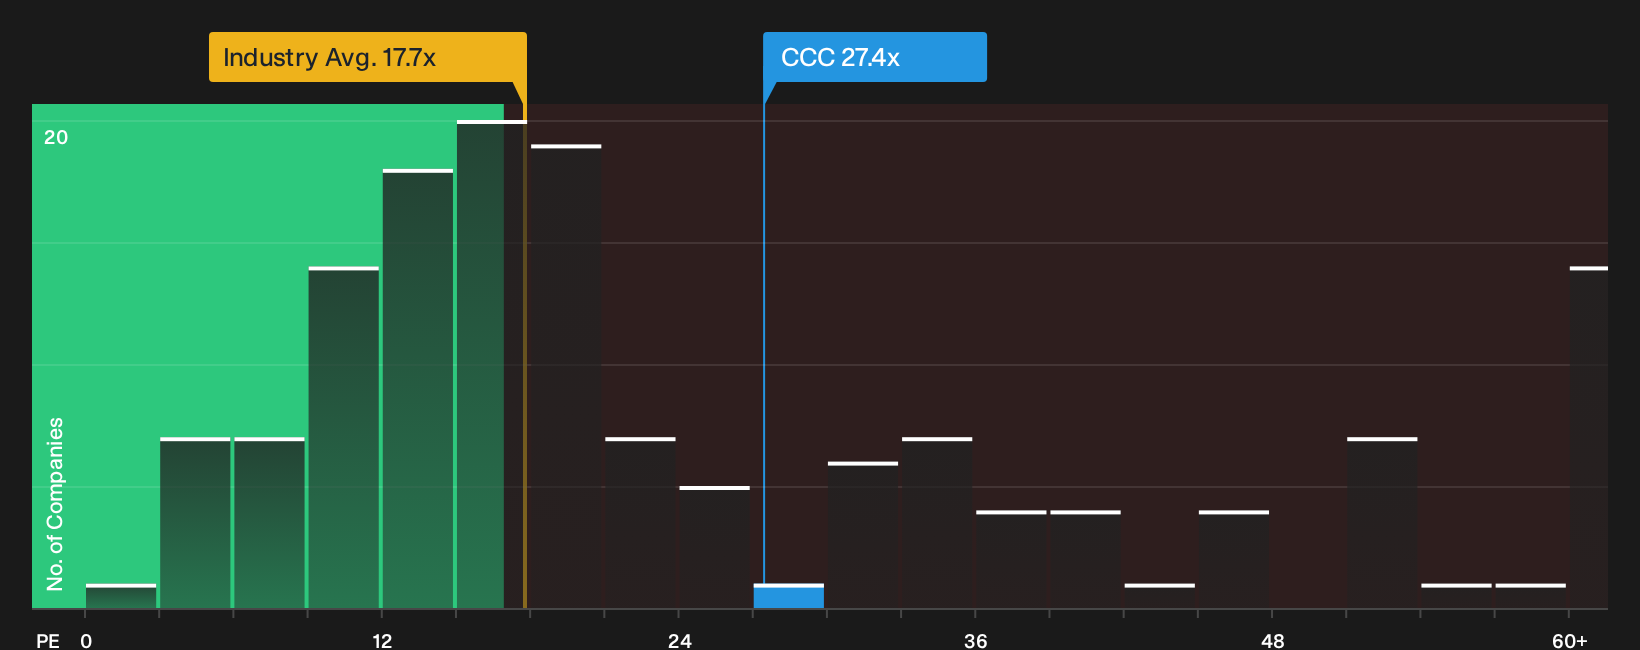
Computacenter appeals to founder led investors because long serving leadership is tightly linked to multi year outsourcing deals, supported by a P/E of 27.4x that sits below the wider IT industry. Its track record of rising earnings and dividends still hinges on how far margins can stretch before contract economics become more challenging.
That margin ceiling question is where things get interesting, so read the analysis report for Computacenter to see whether Computacenter's valuation is masking pressure or fresh upside.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings manages infrastructure, real assets and private equity, with a strong link to the Founder-Led Companies theme through its early venture and emerging growth investing where it often takes majority stakes in founder-originated firms. The group earns about £114.8 million from Real Assets and £50.1 million from Private Equity, and has a market value near £476 million.
Foresight Group gives you an indirect way to back committed founders, since its private equity and venture capital funds often support leaders who stay in charge while outside capital scales their ideas.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really matters for Foresight Group now is how one unresolved shift in fundraising momentum shapes fee margins and long term earnings power.
That shifting fundraising mix is exactly what the full narrative for Foresight Group Holdings unpacks, separating temporary fundraising noise from the areas where Foresight Group’s fee power could be quietly accelerating next.

Seeking Alternatives Before Everyone Else?
Fresh ideas move first. By the time momentum is flying, the easy entry points can be gone. Scan these under the radar lists while it still matters and act now.
- Spot income workhorses early by reviewing our hand picked 1 dividend fortresses before yields get caught in broader buying momentum.
- Track the next potential AI breakout phase by scanning curated 84 AI infrastructure stocks, while these enablers of data and compute demand are still under the radar for now.
- Hunt for resilient operators by filtering the 4 resilient stocks with low risk scores to see which businesses keep compounding even when headlines are dropping every week.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com