
Is Coinbase Global (COIN) Cheap After Its Citi Payments Deal?
Coinbase Global (COIN) is back in focus after a fresh collaboration with Citi that links its crypto payments rails to Citi’s Virtual Account Wallet and Spring by Citi platforms.
For investors watching Coinbase Global, the Citi deal arrives after a mixed share price stretch, with the stock down 4.61% over the past week but still showing a 31.19% 90-day share price return.
That near term pullback sits alongside a 1-year total shareholder return that is lower by 42.58%, even as the 3-year total shareholder return is higher by 154.67%, suggesting that momentum has recently cooled following a strong multi year period.
Surf 19 cryptocurrency and blockchain stocks that, like Coinbase Global, are working to connect traditional finance rails with crypto payments and stablecoin infrastructure.After that pullback and with Coinbase Global changing hands below the average analyst target yet above some intrinsic estimates, the gap between price and fair value looks wide enough to question which side has it right next.
Most Popular Narrative: 22% Undervalued
Against a last close of $191.79, the most followed narrative pegs Coinbase Global’s fair value nearer $247, which frames the current slide as a potential valuation gap rather than a clear verdict on the crypto business model.
I think Coinbase is best understood as a leveraged bet on long-term crypto adoption, rather than a normal operating business with smooth, predictable growth.
What matters most is not whether next year looks clean, but whether crypto becomes a meaningfully larger asset class over time. If that happens, Coinbase should benefit through higher trading activity, higher asset values on the platform, and growth in its custody and subscription businesses.
See why 24 investors see Coinbase Global as 22% undervalued.
Result: Fair Value of $247.39 (UNDERVALUED)
Still, the Coinbase Global narrative can break if crypto trading activity stays muted for long periods or if regulators restrict key revenue lines such as custody and stablecoins.
Find out about the key risks to this Coinbase Global narrative.
Another View on Coinbase Global Valuation
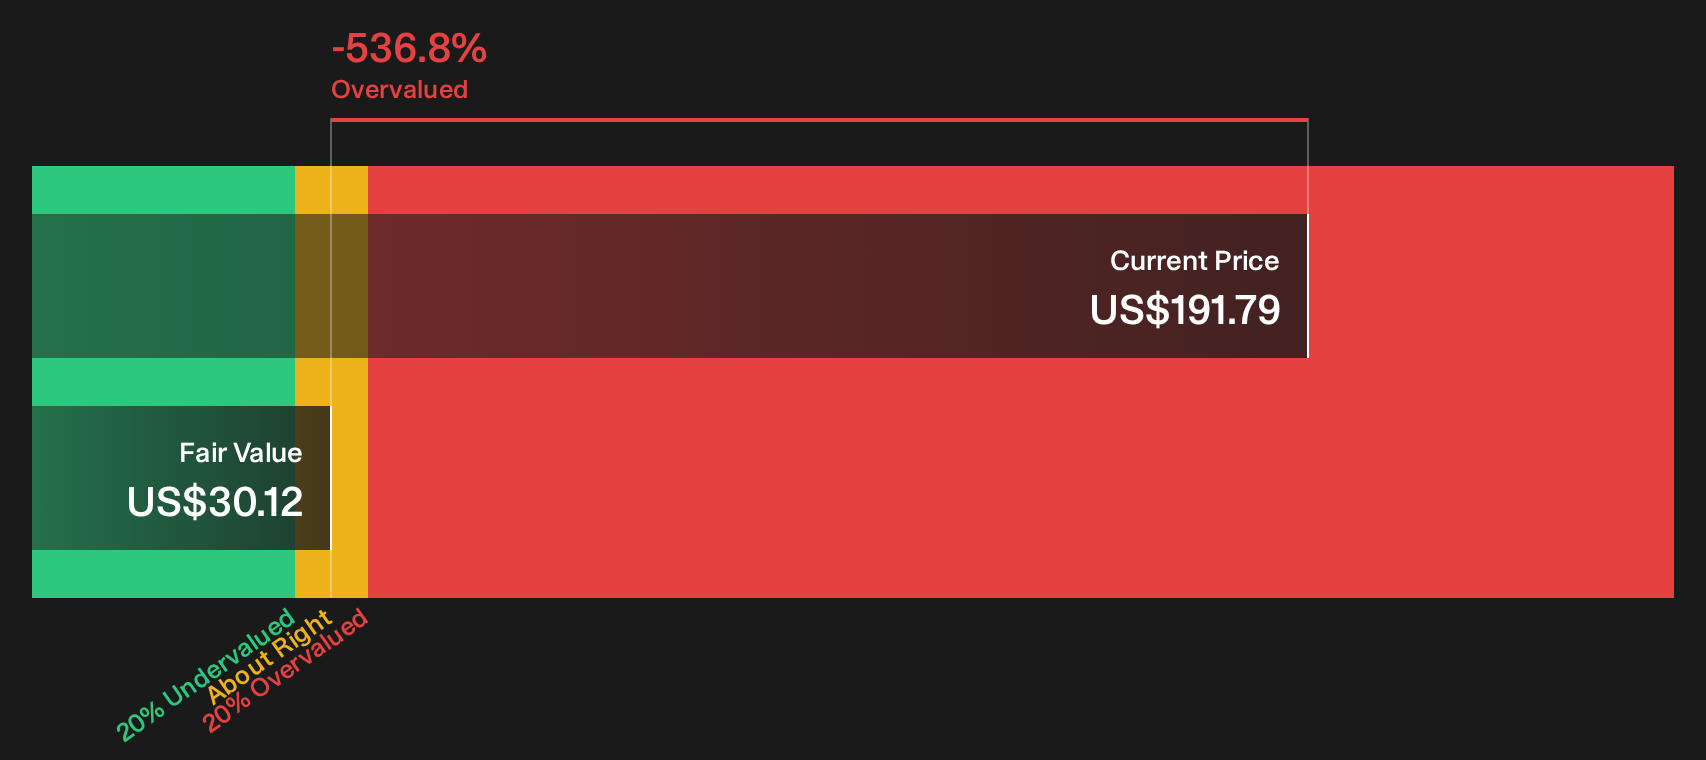
A different lens tells a harder story for Coinbase Global. Our DCF model puts the future cash flow value nearer $30.12 per share, which sits far below the current $191.79 price and points to an overvalued outcome. That kind of gap raises a blunt question for you: Which narrative feels more credible?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or clear message? If you think Coinbase Global is sending a more nuanced signal than a simple bull or bear label, move quickly, study the full risk and reward profile, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Coinbase Global?
Do not stop at a single ticker. Broaden your watchlist with structured ideas so you can keep finding opportunities that match your risk tolerance and return goals.
- Target potential mispricings by scanning for quality companies that screens flag as trading below estimated value through the 33 high quality undervalued stocks.
- Prioritise resilience and capital preservation by filtering for businesses highlighted in the 30 resilient stocks with low risk scores.
- Hunt for lesser known opportunities by reviewing the 16 high quality undiscovered gems before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com