
How Falling Unit Sales At Hormel Foods Has Changed Its Investment Story
- Hormel Foods has recently faced pressure from falling unit sales, flat sales projections, and gross margins that sit below key packaged food competitors.
- The combination of softer demand and structurally weaker profitability raises questions about how much flexibility Hormel Foods has to reinvest behind its brands.
- We will now look at how this weaker demand backdrop for Hormel Foods could reshape the investment narrative that investors have been using.
Balance out Hormel Foods' demand and margin pressures by reviewing a curated 33 high quality undervalued stocks that pairs stronger profitability with more flexible reinvestment potential.
Hormel Foods Investment Narrative Recap
To own Hormel Foods, you need to be comfortable with a packaged food group where the near term story is about repair, not acceleration. Softer unit trends and gross margins that lag peers put the focus on whether pricing, mix, and cost actions can stabilize earnings while input costs and consumer price sensitivity remain in flux.
The key short term catalyst is execution on cost efficiency and supply chain modernization to relieve margin pressure and fund brand support. The biggest risk is that commodity volatility and slower pricing pass through keep profitability compressed, which could limit flexibility on marketing, capacity upgrades, and dividend funding.
With no fresh company announcements since the recent read on weaker demand, the most relevant corporate signal remains management’s Transform and Modernize program. That effort targets automation, a sharper manufacturing footprint, and process improvements that are intended to lower structural costs and support margins over time.
For you as a shareholder, the question is whether Hormel Foods can push those efficiency projects far enough and fast enough to offset falling unit volumes and below peer gross margins. Execution on that program, and how it flows through to earnings quality and reinvestment capacity, will likely anchor the next leg of the story.
Hormel Foods' current analyst storyline points to revenue of US$12.9b and earnings of US$865.7m by 2029. That profile assumes 2.1% yearly revenue growth and an earnings increase of about US$523m from the US$342.7m reported today.
Uncover why Hormel Foods' fair value indicates a 31% potential upside to its current price that could narrow quickly.
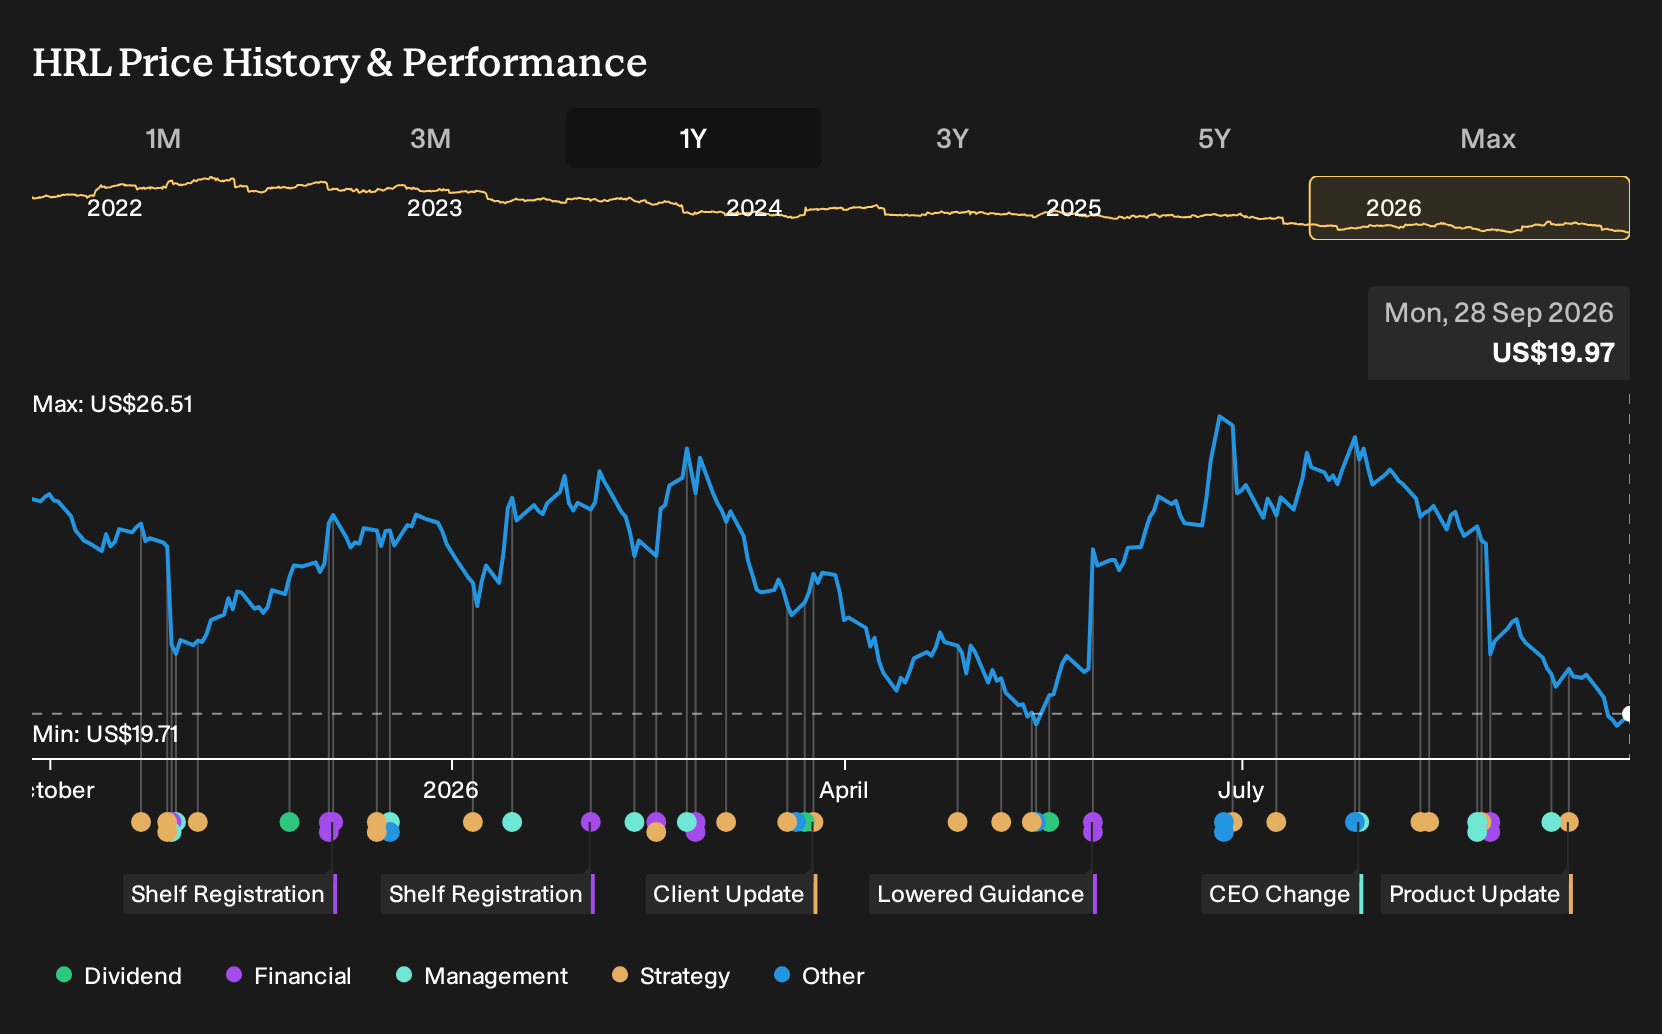
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$26.13 and US$48.48, which shows how far opinions on Hormel Foods can stretch. These views predate the latest margin and demand pressures. Weigh them against risks around commodity costs, brand relevance, and foodservice softness, then explore several alternative viewpoints.
Explore 2 other Hormel Foods fair value estimates, including one that suggests as much as 143% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hormel Foods research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hormel Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hormel Foods' overall financial health at a glance.
Looking For More Ideas Beyond Hormel Foods?
If Hormel Foods raises questions about demand resilience and reinvestment headroom, it can help to compare it with other businesses that score differently on value, balance sheet strength, and risk. The Simply Wall St Screener lets you filter for exactly the traits you care about so you can build a watchlist that matches your own comfort zone.
- If you want high quality combined with pricing that still looks reasonable, scan through a curated 33 high quality undervalued stocks that filter for stronger fundamentals.
- If resilience and financial strength matter most to you, focus on companies with robust finances using a list of solid balance sheet and fundamentals (25 results) that can better support future investment.
- If you prefer businesses with steadier profiles and fewer red flags, narrow your research with a 30 resilient stocks with low risk scores that targets more defensive characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com