
MasTec (MTZ) Could Be 51% Undervalued As FTSE All World Inclusion Draws Focus
MasTec (MTZ) was added to the FTSE All-World Index (USD) on 19 September 2026, putting the construction and infrastructure contractor on the radar of more global index and fund investors.
Recent trading has been rough for MasTec, with the share price down 4.1% over the last day, 8.4% over the past week and 15.3% across the month. The 1-year total shareholder return is slightly lower at 2.6%, while the 3-year total shareholder return is up about 3x, suggesting long-term holders have still seen strong overall gains even as near-term momentum has faded ahead of the FTSE All-World inclusion.
Scan MasTec alongside other infrastructure focused construction firms that are showing sharp inflections in sentiment with our curated list of 39 power grid technology and infrastructure stocks.
MasTec now trades at a steep discount to both analyst targets and estimated fair value after a sharp pullback into its FTSE All-World debut. Is that caution grounded in fundamentals, or has sentiment simply swung too far?
Most Popular Narrative: 51% Undervalued
MasTec's most followed valuation framework points to a fair value of about $416.95 versus the recent $204.09 close, framing the current pullback as a gap between long-term project visibility and short-term price pressure.
Rapid acceleration in utility grid modernization, data center build-outs, and renewable energy investment is associated with double-digit revenue growth and record backlog in MasTec's Power Delivery and Clean Energy & Infrastructure divisions. The company's position and customer relationships are cited as factors supporting expectations for continued top-line expansion over the next multi-year cycle.
See why 26 investors see MasTec as 51% undervalued.
Result: Fair Value of $416.95 (UNDERVALUED)
Still, the bullish MasTec narrative hinges on big project pipelines and on policy support not stalling, while customer concentration leaves earnings exposed if large contracts slip or shrink.
Find out about the key risks to this MasTec narrative.
Another View On MasTec's Valuation
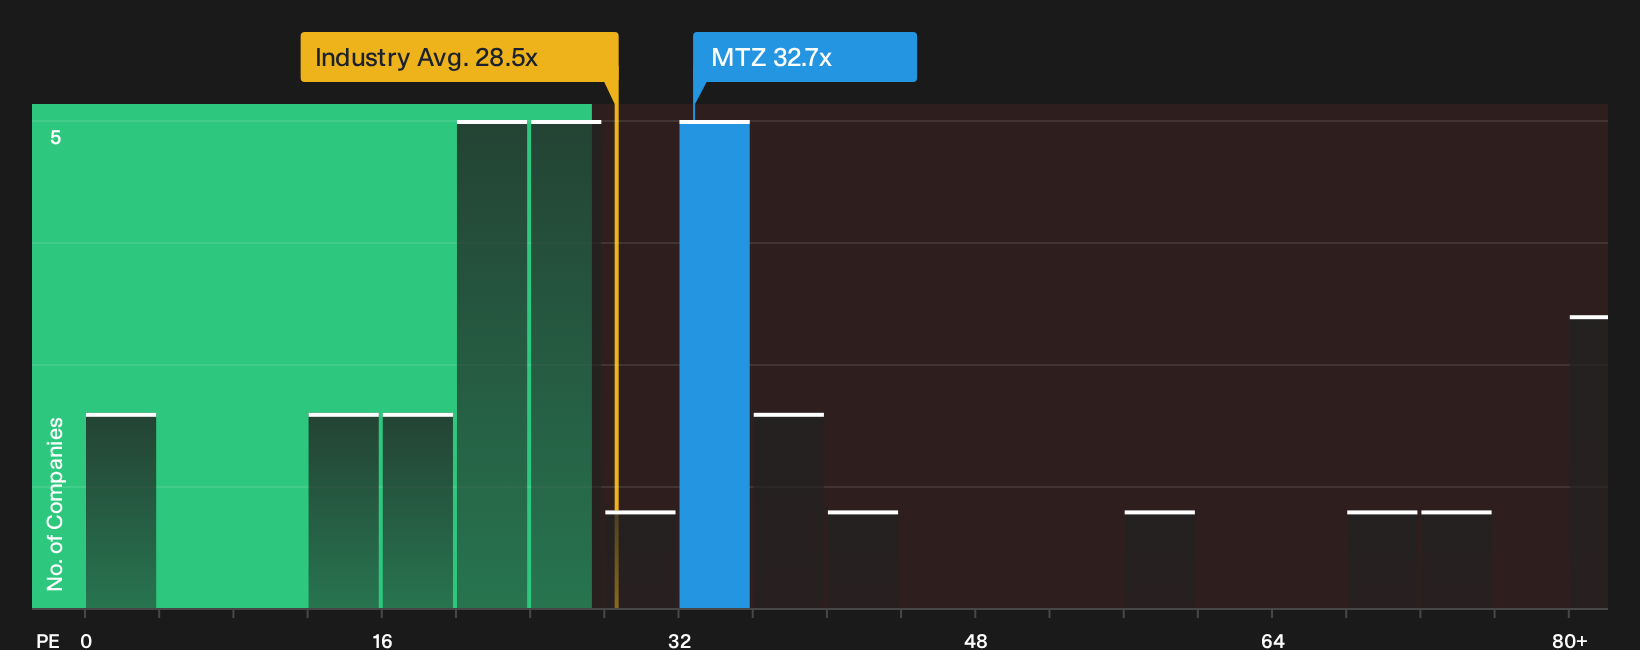
On the flip side of that bullish 51% discount story, MasTec trades on a P/E of 32.7x compared with 28.5x for the wider US Construction group and 27.9x against peers. The fair ratio is estimated at 39.9x, which suggests some valuation cushion but also real multiple risk if sentiment weakens.
To see how this earnings multiple stacks up against the drivers behind it, including growth, quality and peer benchmarks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around MasTec's valuation and price swings can feel messy, so move quickly. Review the data and weigh both sides for yourself with 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond MasTec?
If MasTec has sharpened your focus on pricing and fundamentals, do not stop here. Tap into other ideas so you are not leaving potential opportunities untouched.
- Hunt for quality at a discount by scanning our curated pool of 33 high quality undervalued stocks that pair stronger fundamentals with appealing valuations.
- Build a steadier foundation for your portfolio by zeroing in on companies from the list of solid balance sheet and fundamentals (25 results) that prioritize financial resilience.
- Get ahead of the crowd by filtering for 16 high quality undiscovered gems that combine solid numbers with lower investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com